
Sorry, you need to enable JavaScript to visit this website.
Skip to main content

Developed Countries

Optimism about the future continues to boost investor confidence in the Euro Area.  The ZEW Expectations series for the Eurozone (+10.4 to 43.9) and Germany (+11.2 to 42.9) surged and are now both at their highest in 26 months. Although investors’…
UK stocks posted one of the largest positive abnormal returns (z-score) among the major financial markets we tracked in March. The MSCI UK index has gained 2% relative to Eurozone stocks since late February. However, the relative performance of UK equities…

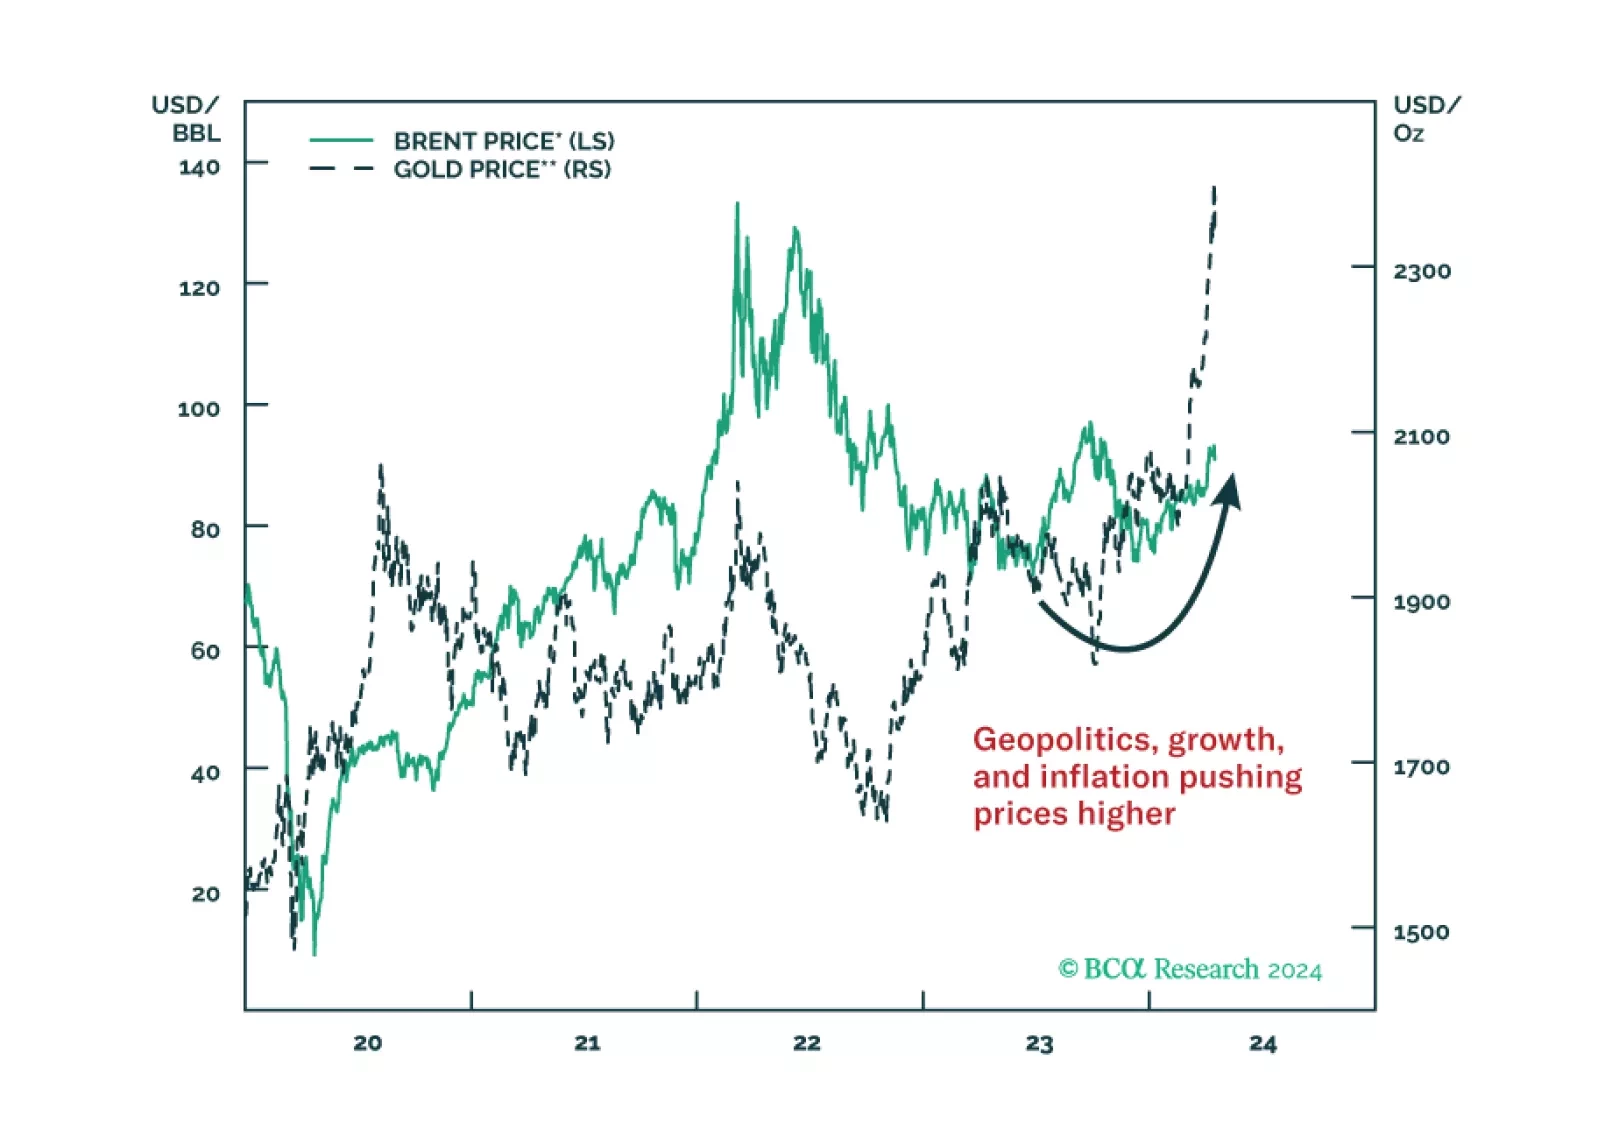
In the near term, favor oil and oil producers outside the Gulf Arab states. Over a 12-month horizon, favor US and North American equities, defensive sectors over cyclicals, and safe-assets. Within cyclicals, stick to energy and defense.
According to BCA Research’s European Investment Strategy service, a tactical buying opportunity for EUR/USD is approaching. However, this will not lead to a renewed bull market, only to a bounce toward 1.10-1.12.  Sentiment toward the euro is becoming…
The preliminary reading of the University of Michigan gauge of consumer sentiment slid from 79.4 to 77.9 in April from 79.4, below expectations. Although both current conditions and expectations disappointed, the deterioration in expectations came against the…
Headline inflation in Sweden came in at 4.1% in March. Lower food prices as well as lower inflation for recreation and culture were the main contributors to the drop. The biggest positive contributor was housing due to higher mortgage costs. The CPIF…
Advanced estimates for retail sales in the US grew by 0.7% m/m in March, down from an upwardly revised 0.9% m/m in February, but meaningfully outperforming expectations of 0.3% m/m. Retail sales ex autos also surprised to the upside, coming in at 1.1% m/m…
Special Report

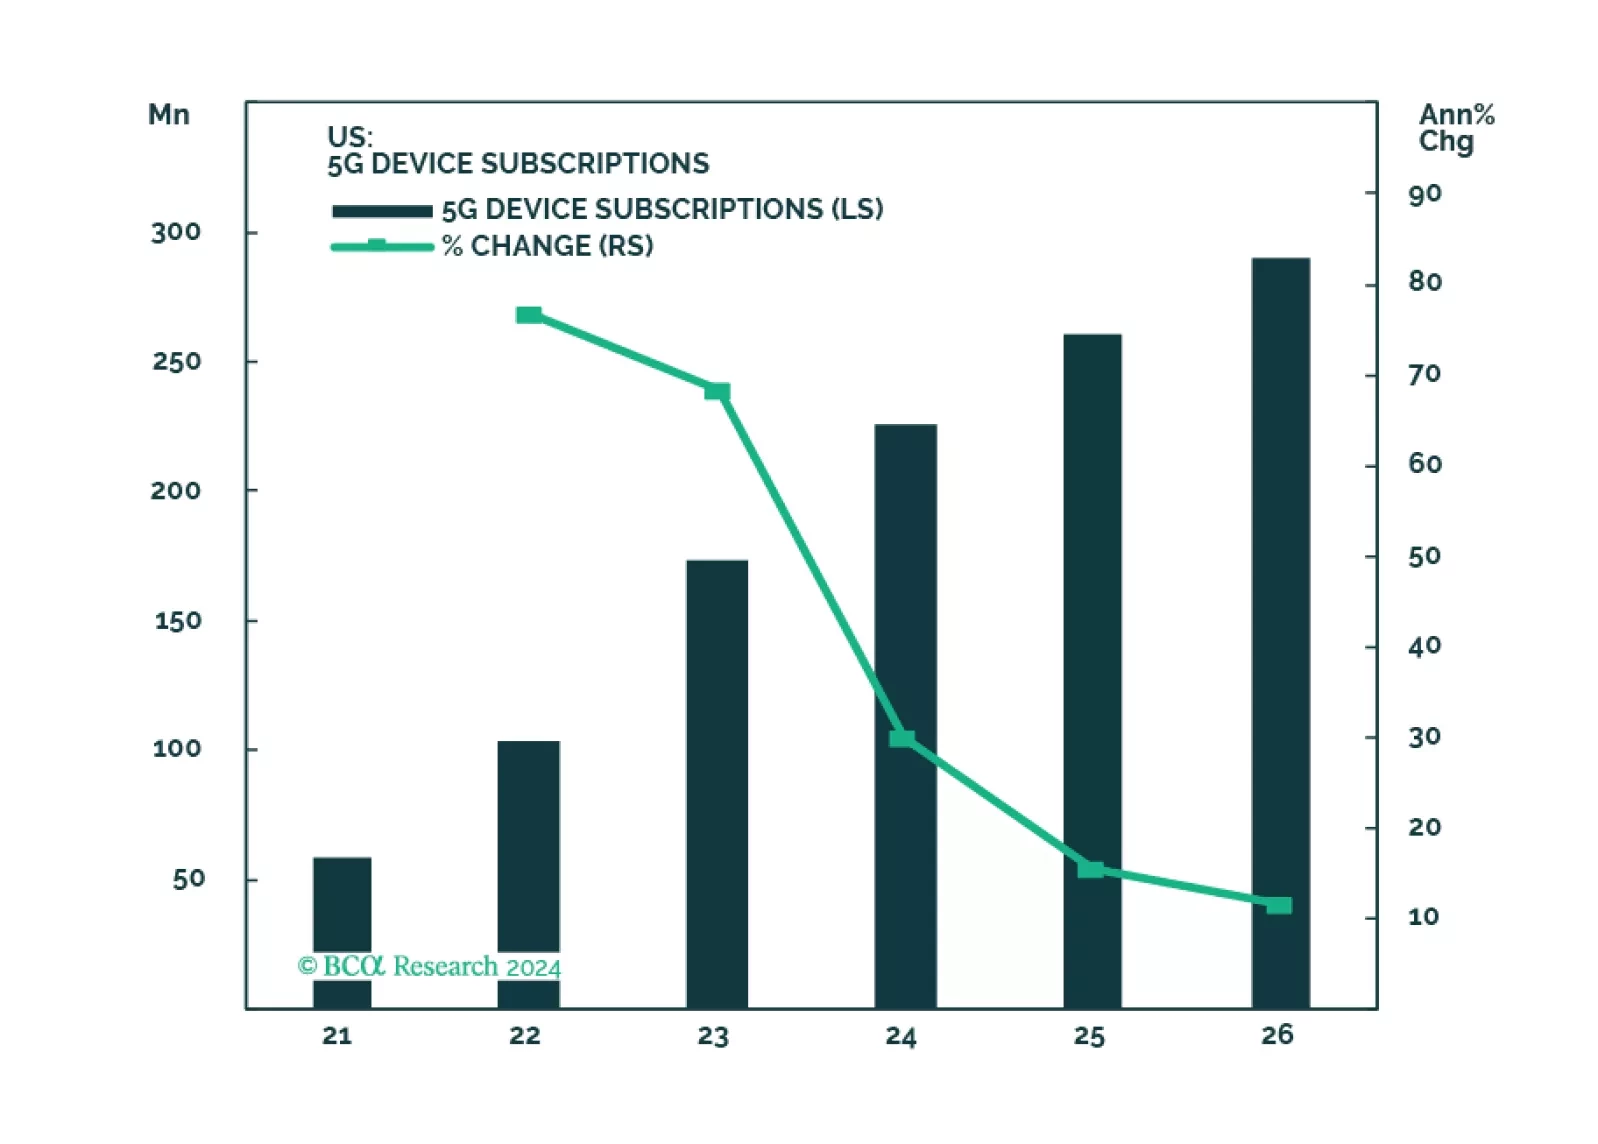
The Telecoms industry is highly concentrated, and carriers compete on price and quality of service in a slow growing market. Demand for capex is relentless. The roll out of 5G has disappointed. Recently, capex outlays have slowed, and operating cash flow has rebounded. Further, Telecoms is a quintessential defensive industry that will outperform during a market pullback.
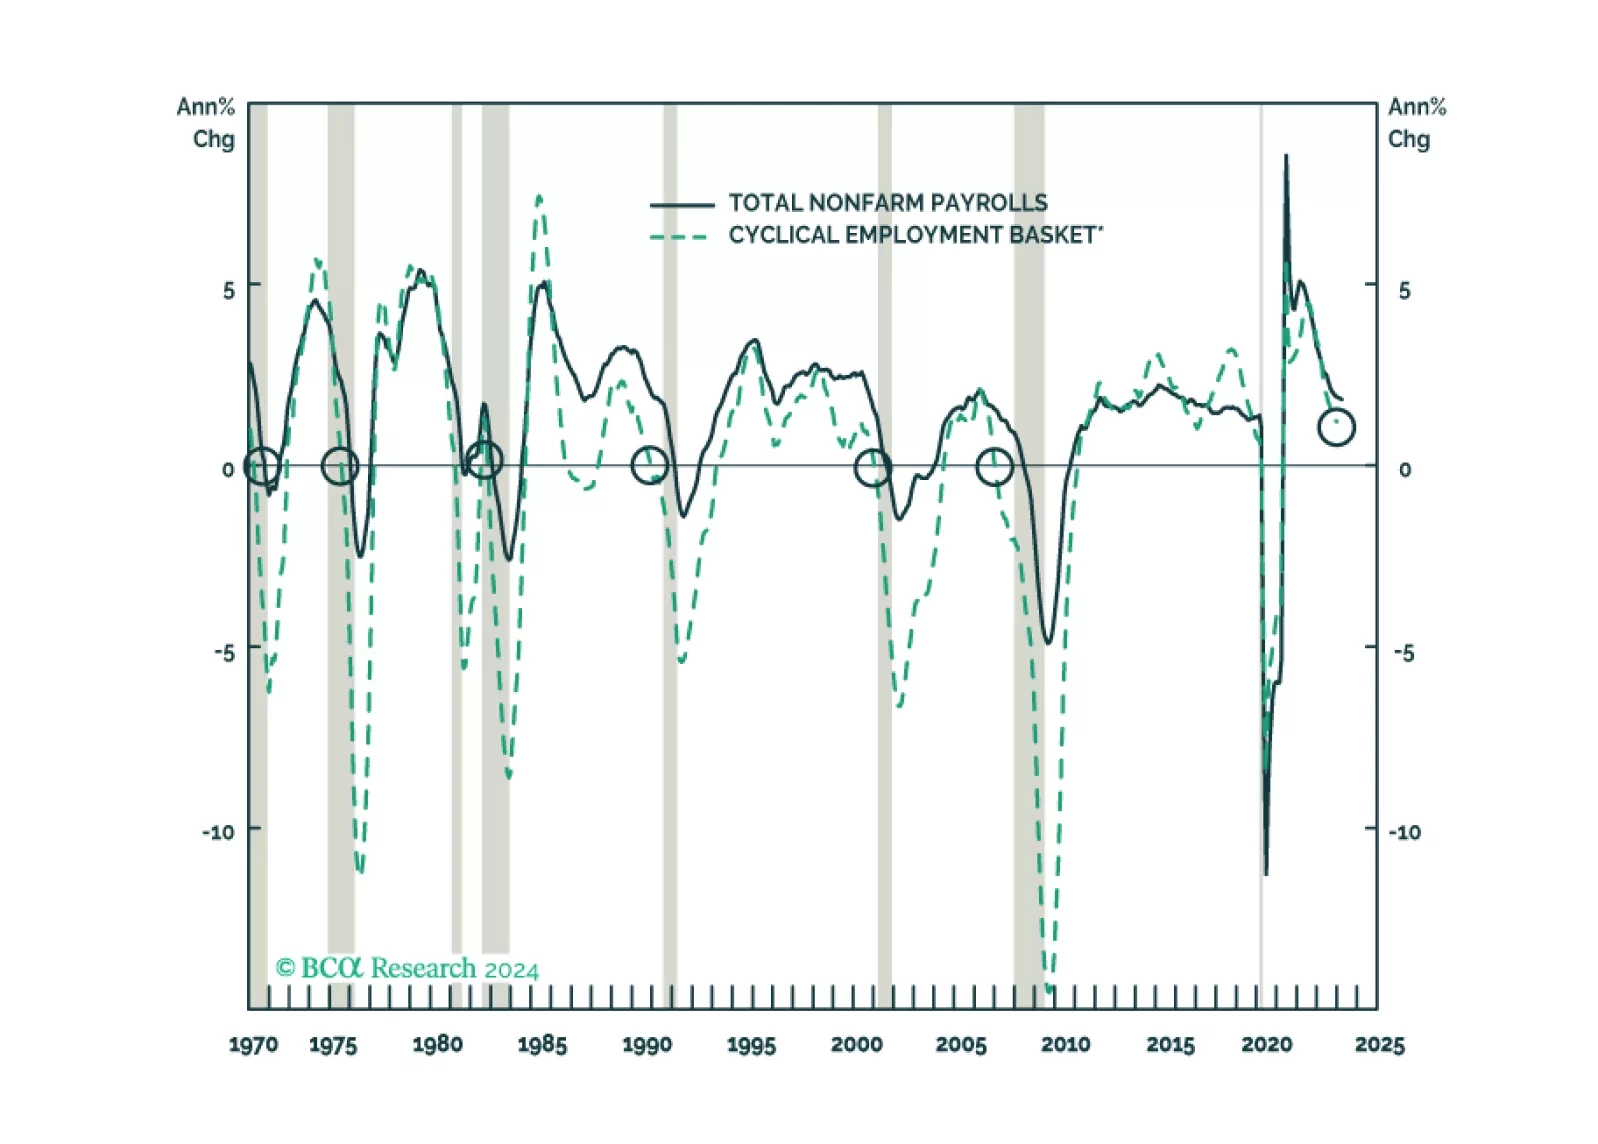
We look beneath headline data to assess the state of the labor market in cyclical goods-producing industries that have previously led overall nonfarm payrolls and in the services segments that have recently been leading the charge. The bottom-up view looks a lot like the top-down view: the labor market is softening, but very slowly, and offers no indications that a recession is at hand.
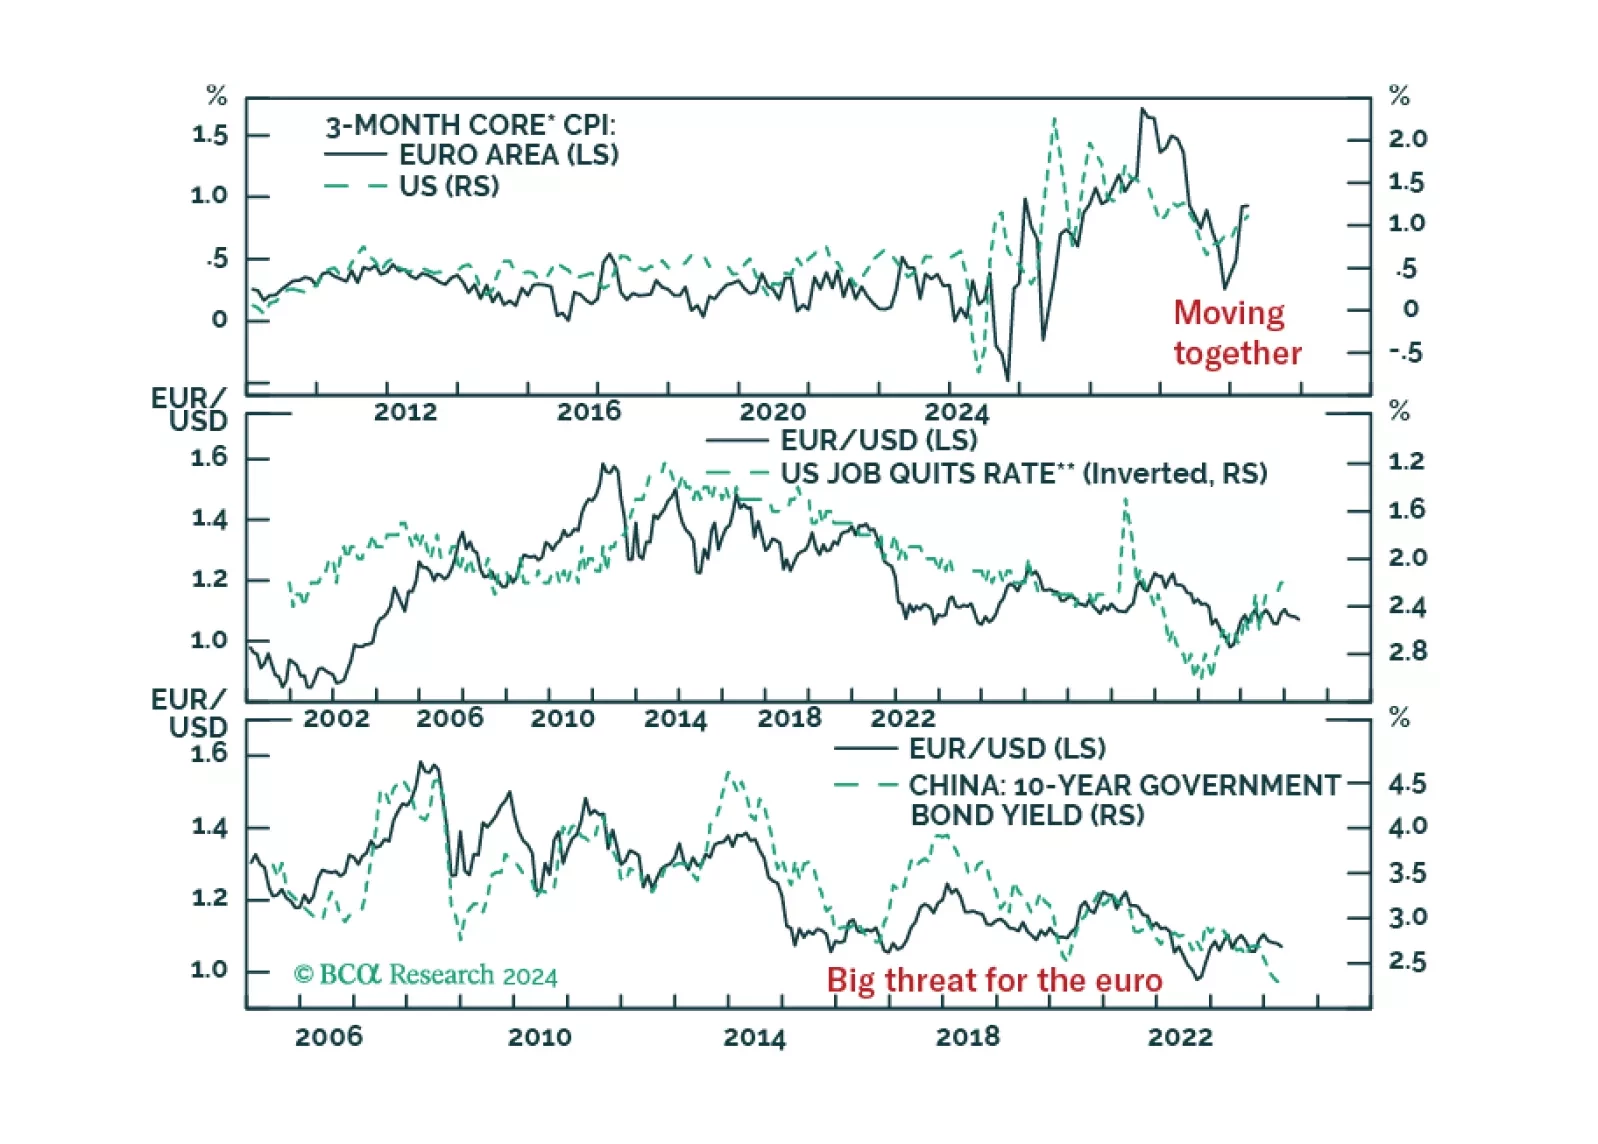
EUR/USD collapsed in the wake of last week’s hotter-than-expected US CPI report. Is this pessimism warranted and will the euro’s trading range that has prevailed since 2023 breakdown?