
Sorry, you need to enable JavaScript to visit this website.
Skip to main content

Developed Countries

The ZEW survey of investor sentiment continues to send an optimistic signal. German sentiment jumped from -1.1 to +9.8 in November – its highest level since March and beating expectations of a smaller improvement to 5.0. Similarly, expectations for the Euro…
To the extent that US small businesses are typically more exposed to domestic economic conditions than larger firms, results of the NFIB Small Business Economic Trends survey are instructive. One important trend is that the October survey results…
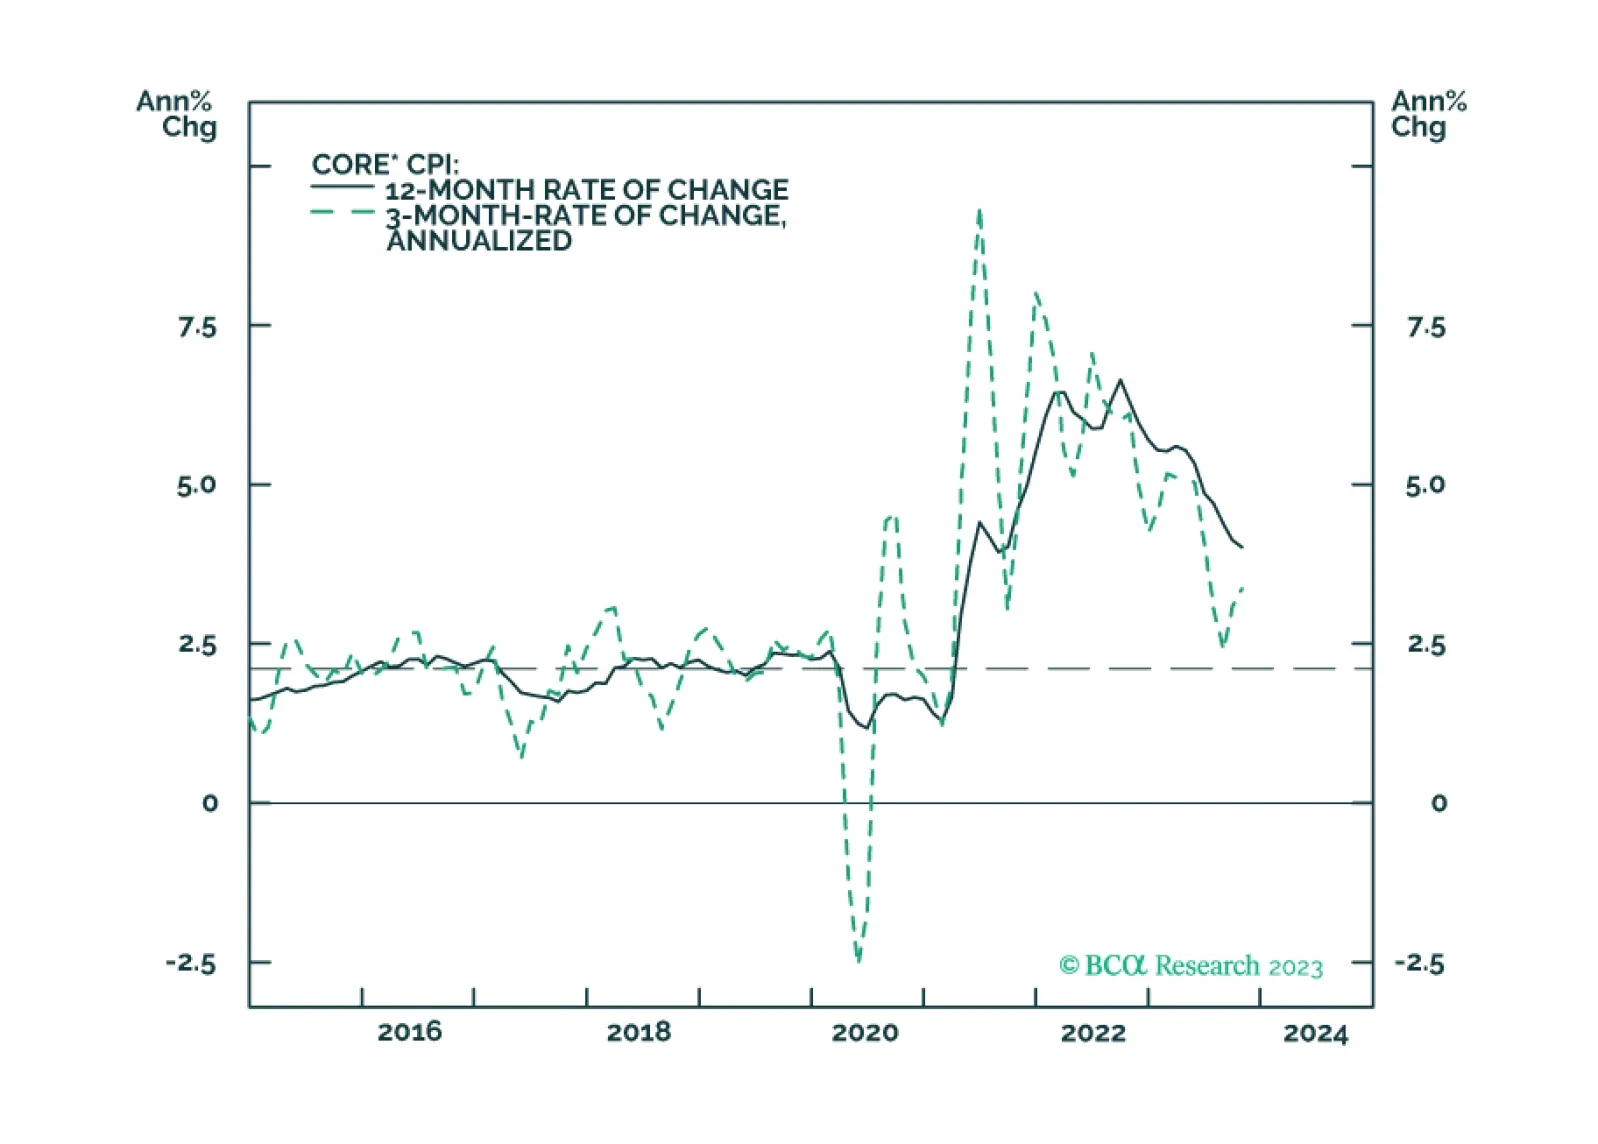
US Treasury yields fell sharply following yesterday’s soft October CPI report, and investors have now officially priced out all remaining rate hikes from the yield curve. In fact, the fed funds futures curve is priced for a 25 basis point rate cut by next…

Our thoughts on this morning’s CPI print and the bond market’s reaction.
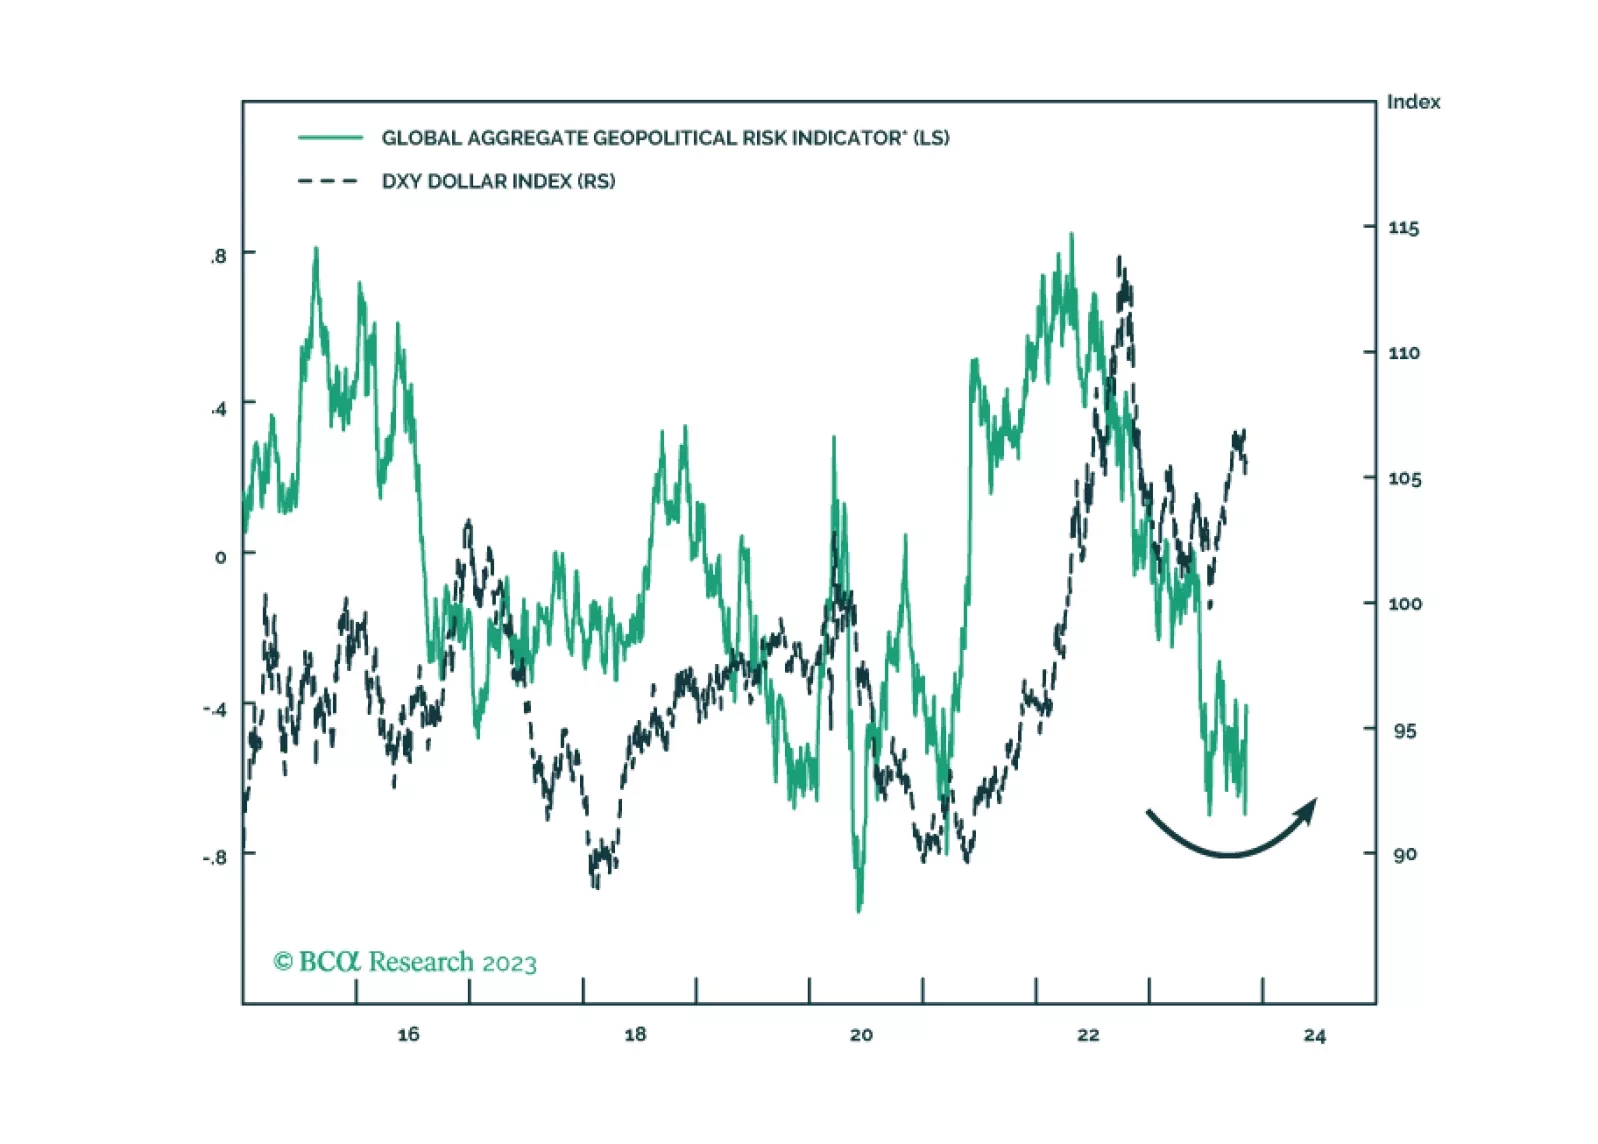
Amid a range of geopolitical narratives, what matters is that the US strategy of economic engagement with its rivals is failing, giving rise to a new strategy of containment that will reinforce the secular rise in geopolitical risk. Our market-based quantitative indicators of geopolitical risk are set to rise in the coming year.
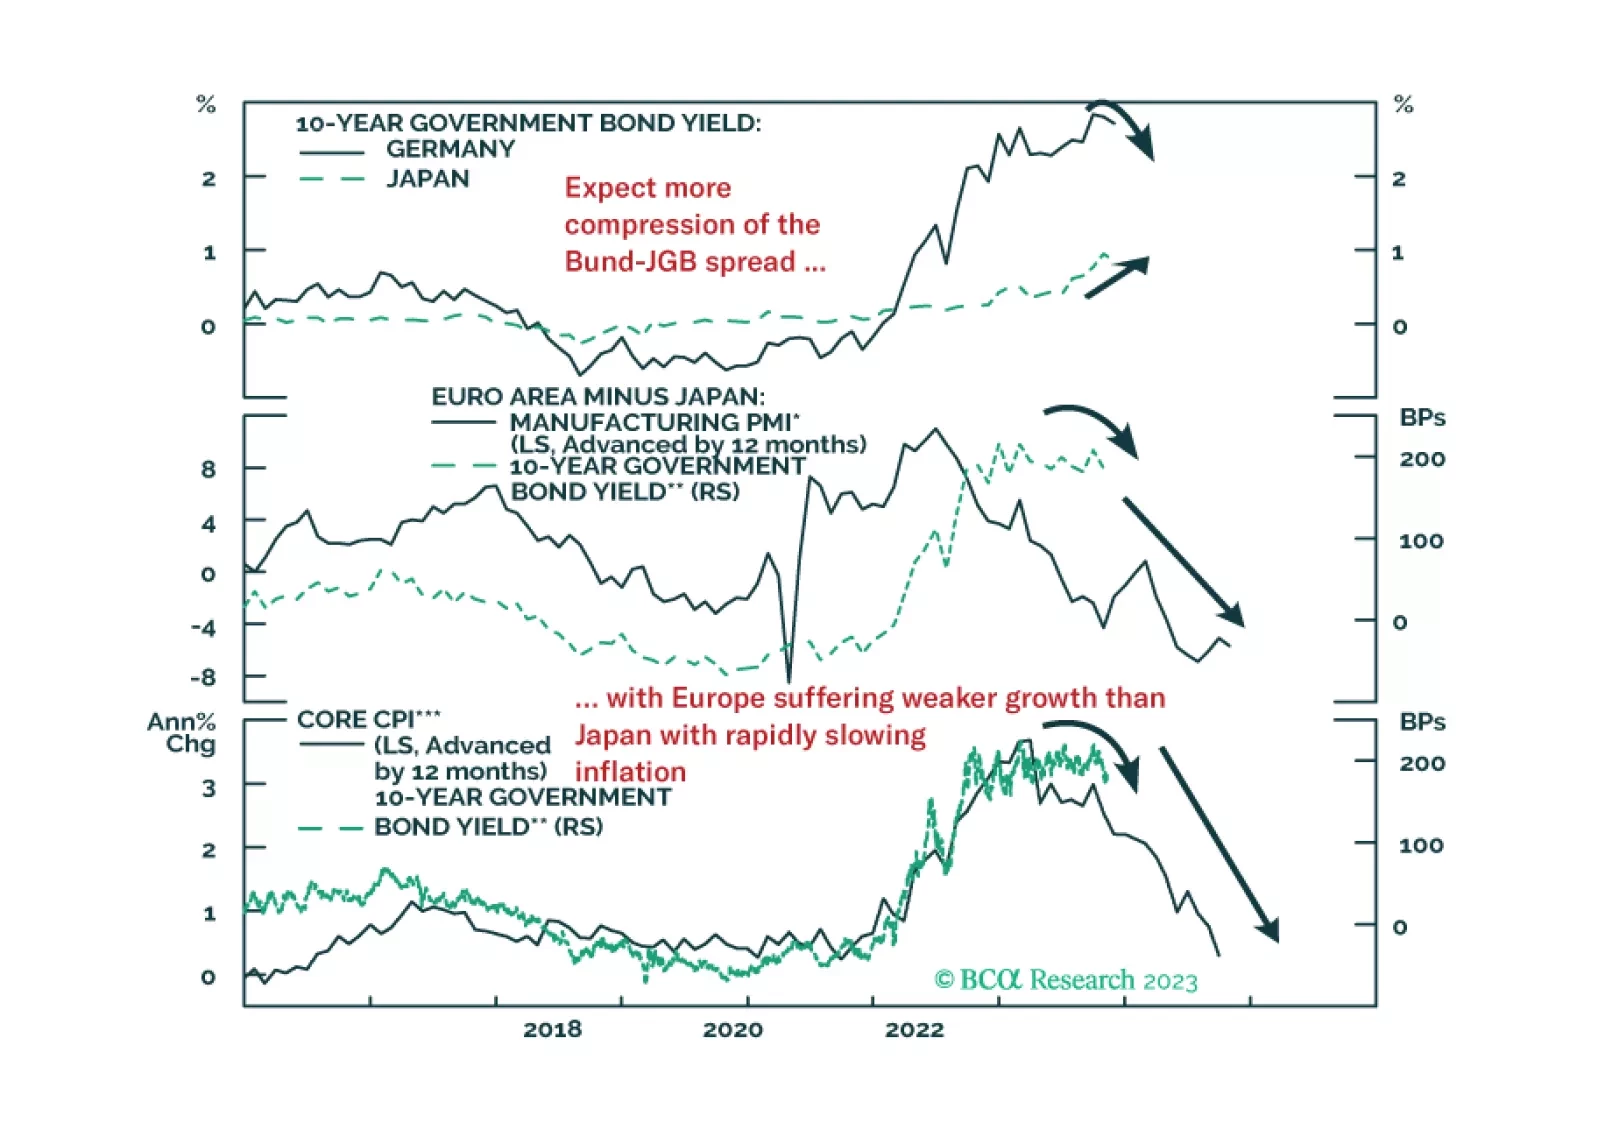
In this Insight, we review the performance and rationale for our current set of tactical fixed income trade recommendations. Our highest conviction positions also happen to be our most successful trades: positioning for a narrowing of the German bund-JGB spread and wider Japanese inflation breakevens.
Investors should not get their hopes up about this week’s US-China summit. Chinese President Xi Jinping and US President Joe Biden will meet on the sidelines of the Asia Pacific Economic Cooperation (APEC) summit in San Francisco on November 15. The two…
Our equally weighted global cyclical equity index has outperformed equally weighted defensives for most of this year. By October 17, this outperformance stood at about 12.6%. This outperformance is consistent with US Treasury market dynamics. The relative…
BCA Research's Global Investment Strategy service assigns 25% odds of the recession starting in 2025 or later.  Our colleagues continue to think that the US will succumb to a recession in 2024, probably in the second half of the year. They see the…

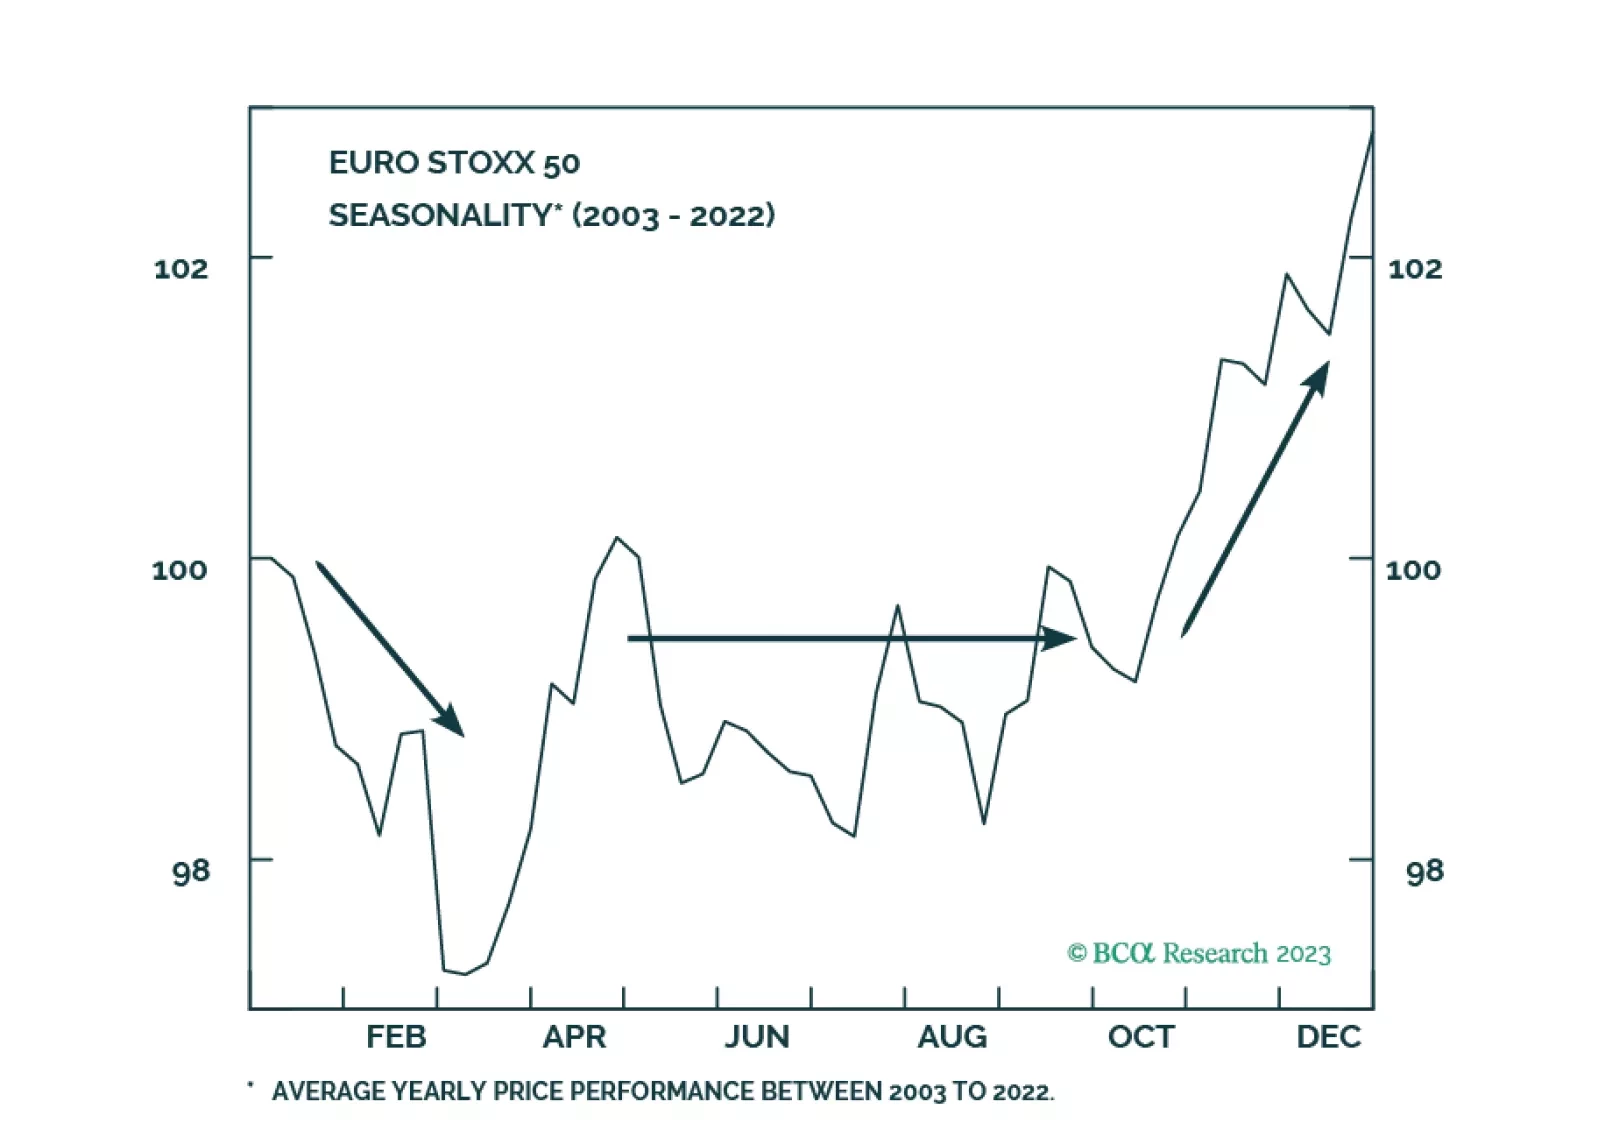
European markets have room to rebound in the coming weeks, however, a recession looms. What are the lessons from history that investors can use to position themselves under these conditions?