Sorry, you need to enable JavaScript to visit this website.
Skip to main content

Equities

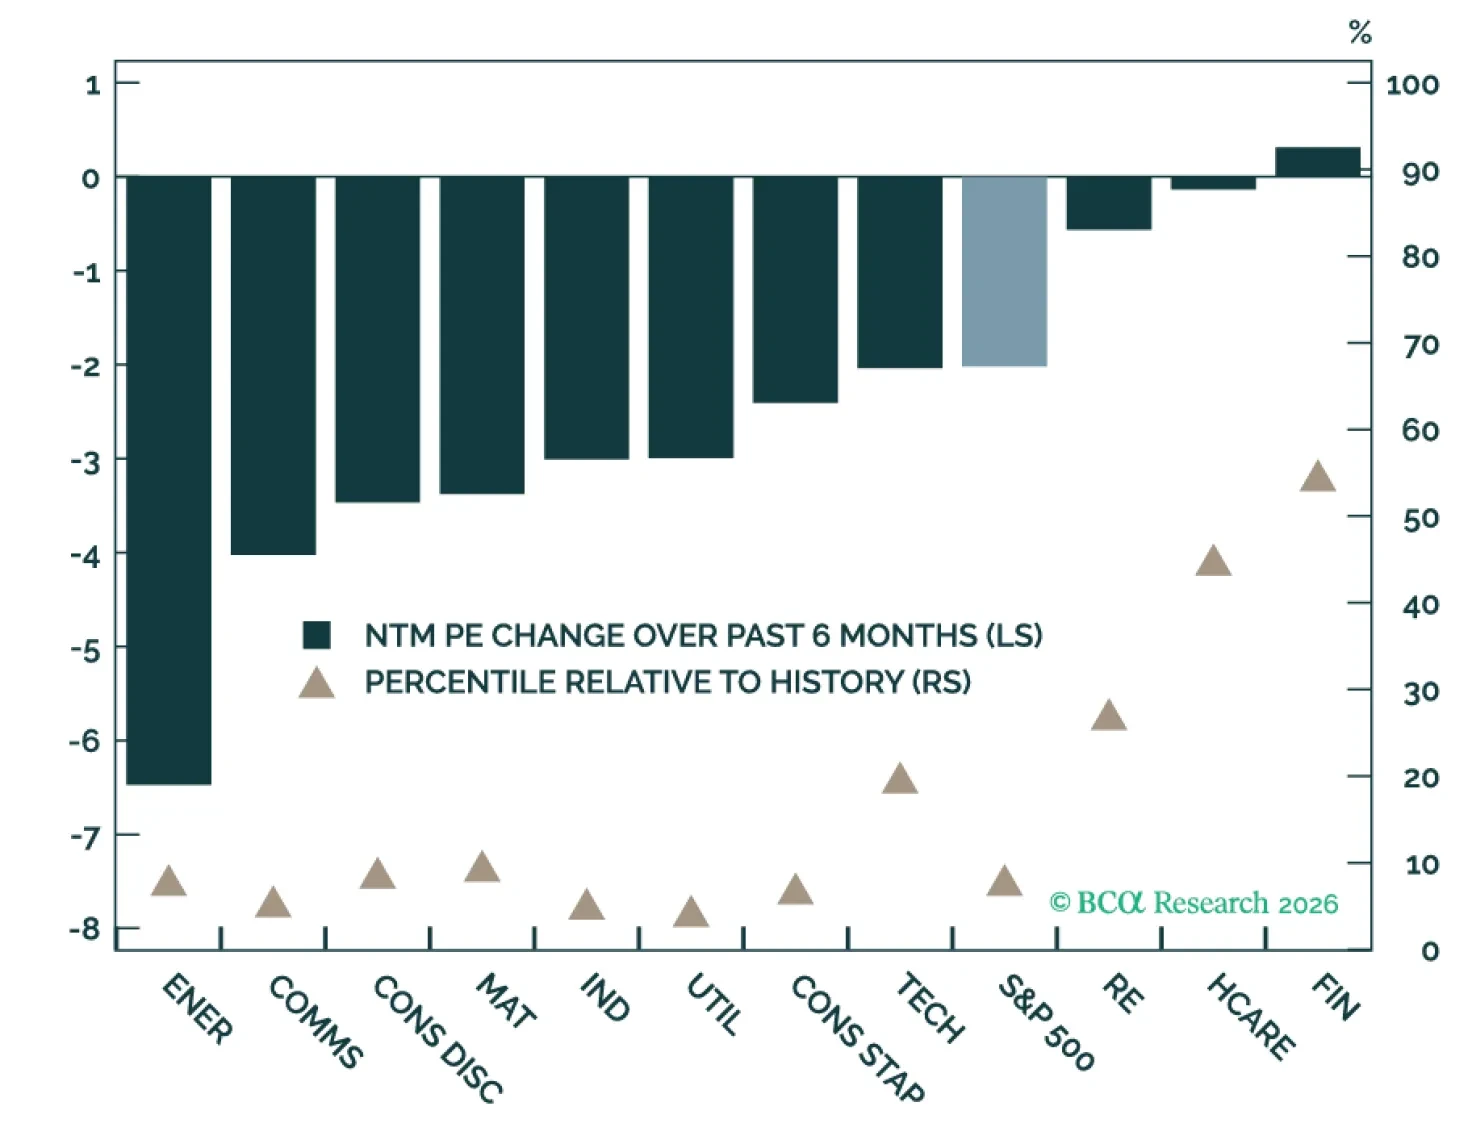
We remain constructive on US equities, but higher yields, slower EPS growth and heavy IPO issuance remain significant risks to valuations, leaving the path to our year-end target increasingly dependent on earnings. Tactically, there has already been a significant, but benign, compression in multiples, as earnings have outpaced prices. A well-communicated Fed hike could ease rather than intensify bond-market uncertainty. 
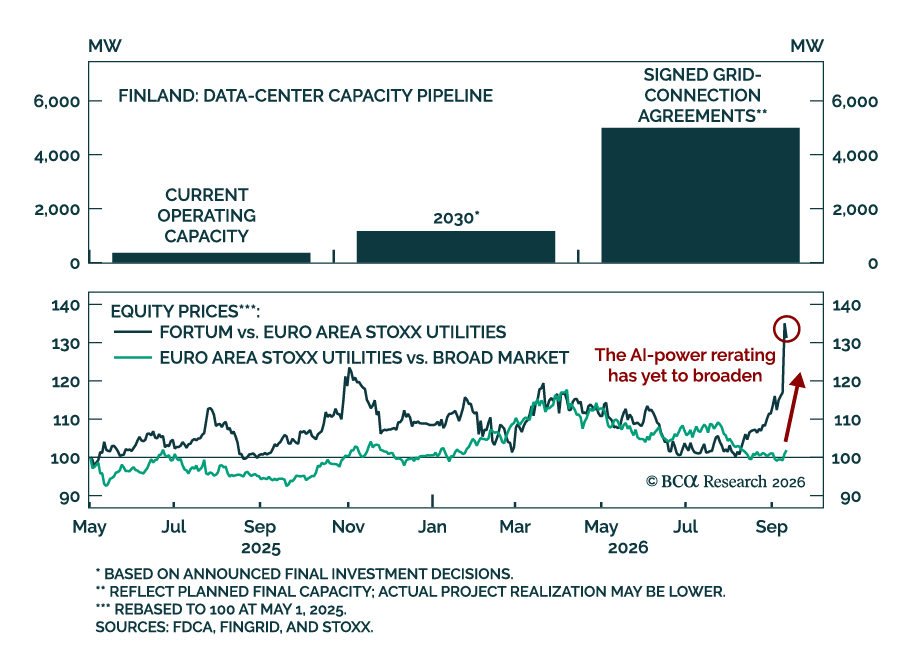
Europe’s AI buildout is creating a new source of structural power demand. Our Chart Of The Week comes from our analyst Eugenia Pan, and shows why this trend is favoring utilities with reliable low-carbon power. Finland offers an early example. While its…
Special Report

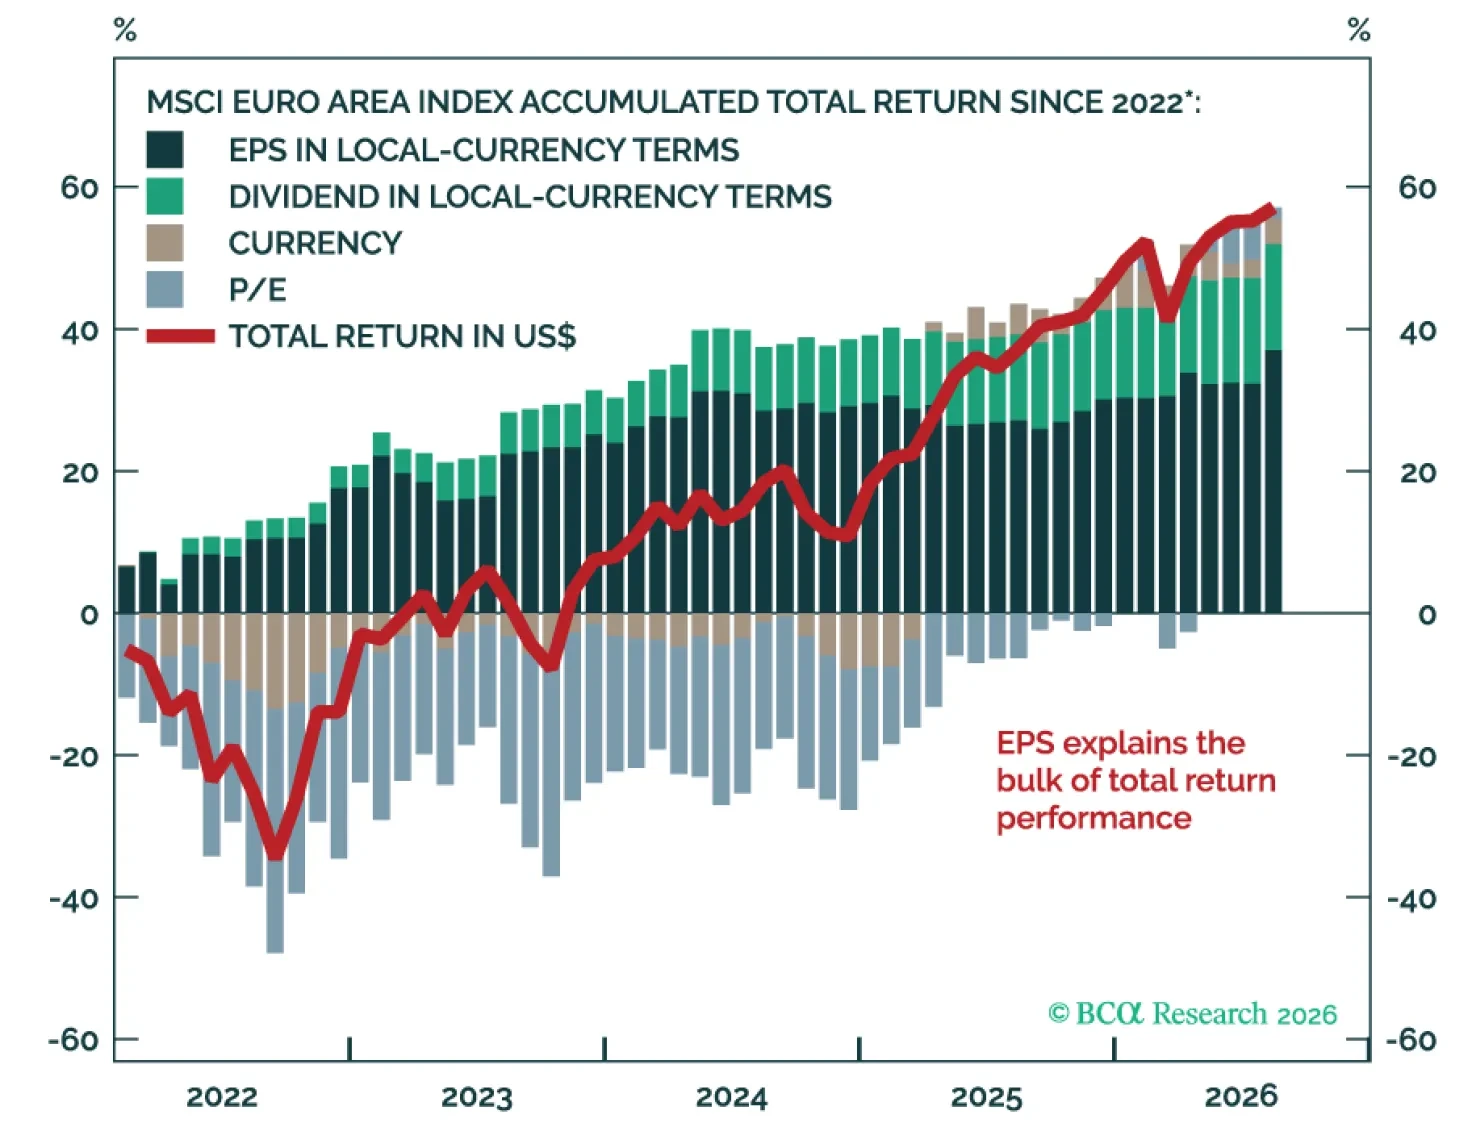
Europe’s earnings recovery is increasingly difficult to dismiss. Margins, ROE, ROIC, and capital efficiency have all improved, while banks have re-emerged as an earnings engine. Cyclical conditions remain supportive, and the structural picture continues to improve: higher investment, improving productivity, and EU reforms could give the recovery staying power.
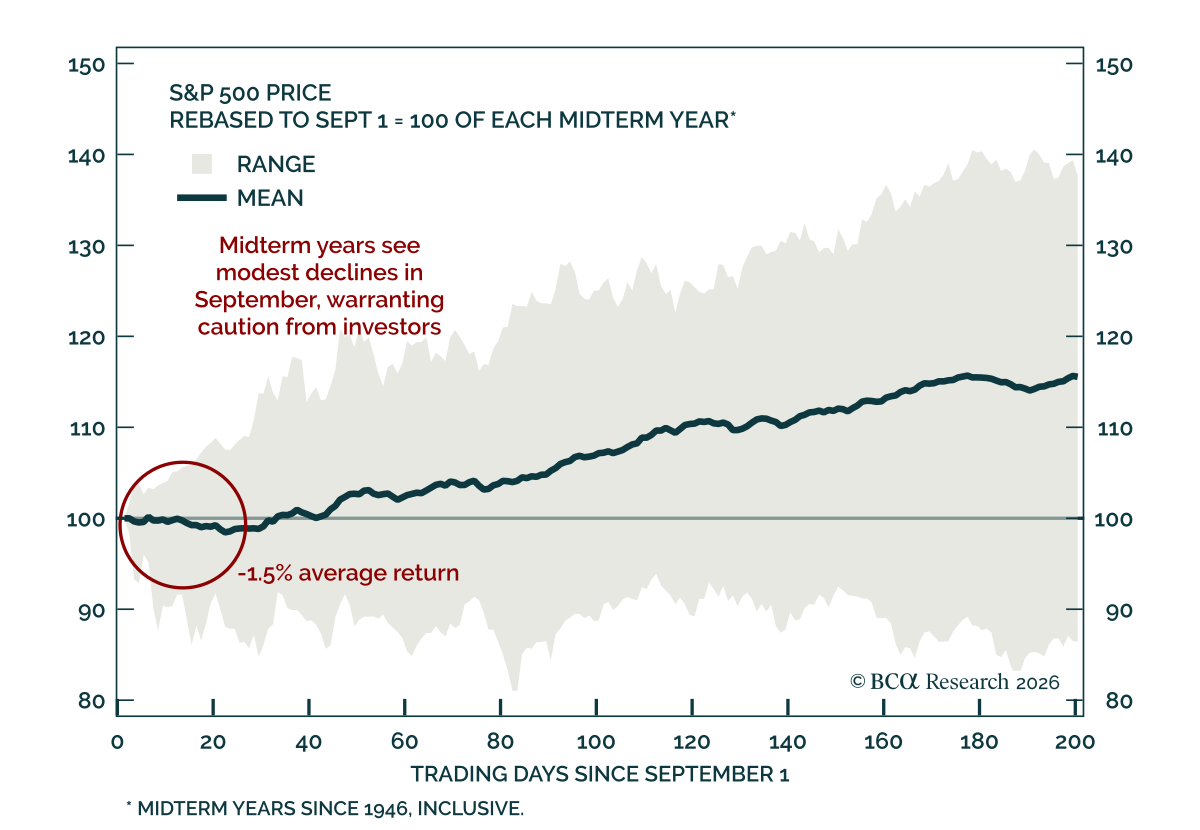
Historically, midterm years have been rough on equities. Investors should approach September with heightened caution. Since the end of WWII, the S&P 500 has averaged a 1.5% decline from September 1 to its low point, which typically lands in early October.…

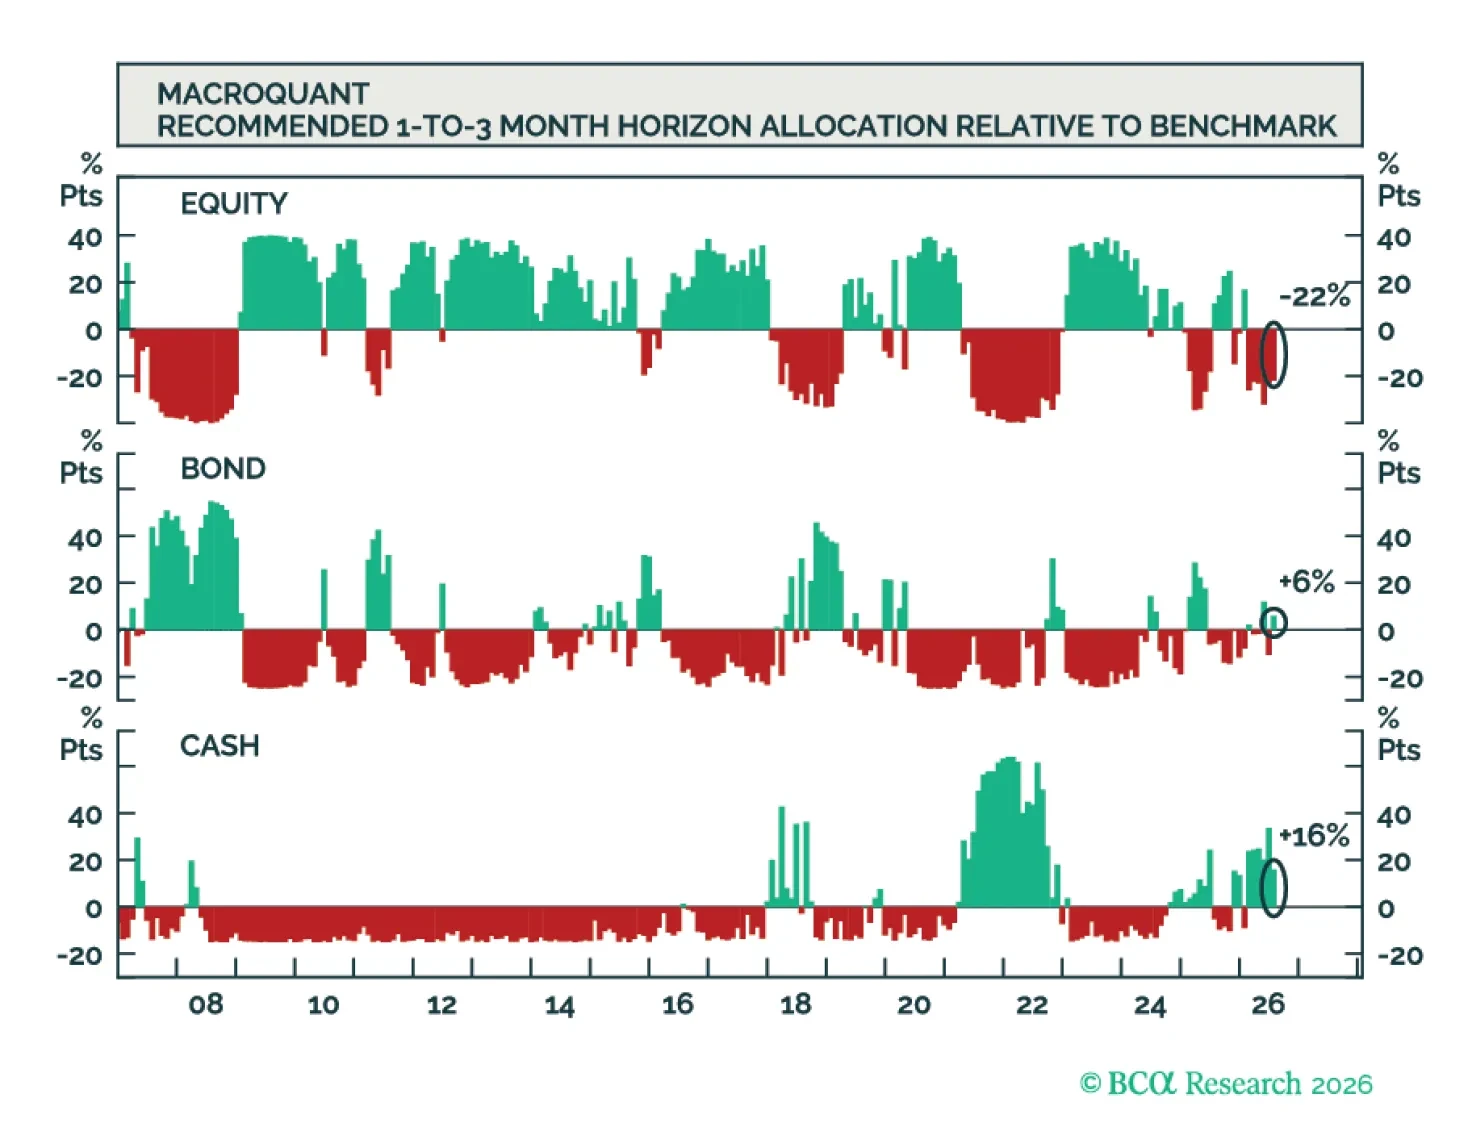
MacroQuant recommends a slight underweight position in equities, counterbalanced by a slight overweight to bonds, and a significant overweight to cash. The model is positive on the US dollar, modestly negative on gold, and bullish on copper and oil.
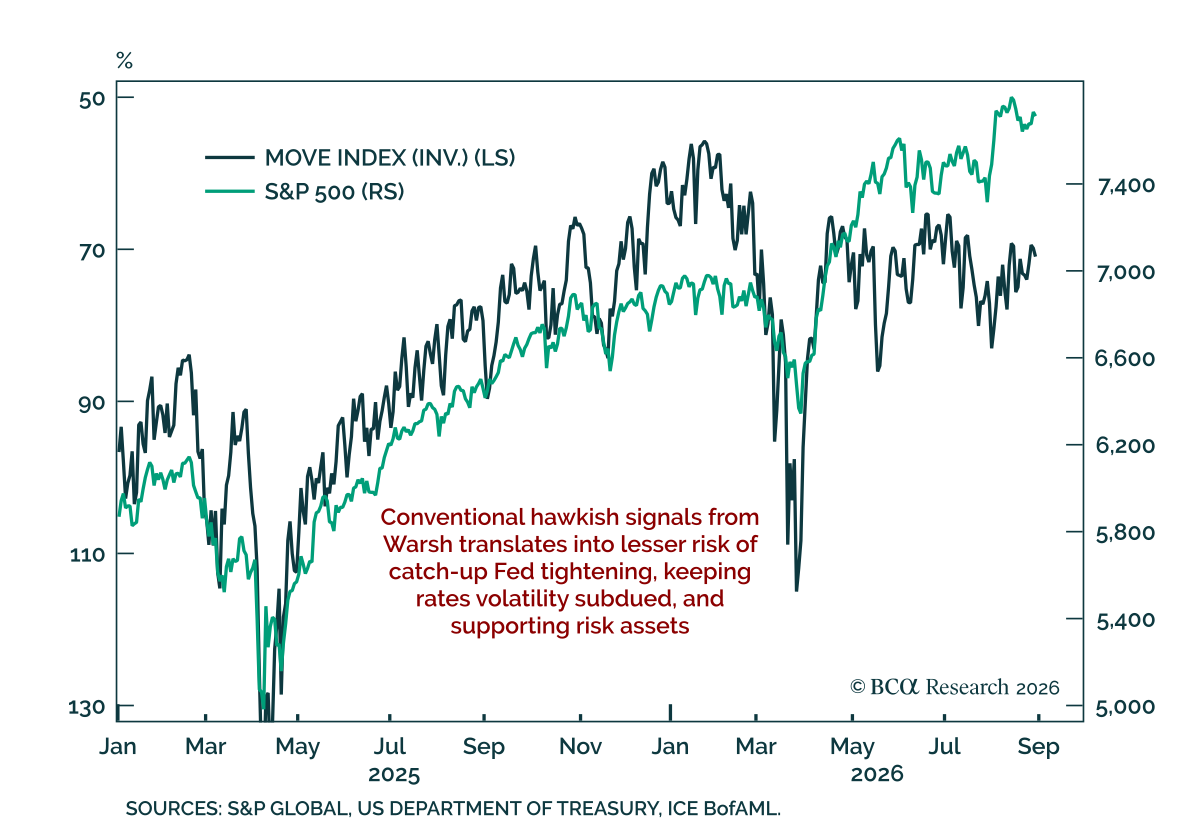
The level of yields matters less for equities than how quickly rates move, making implied rates volatility the more useful gauge of equity risk. Stocks have delivered positive returns across different rate regimes, with both rising and falling yields. The key…
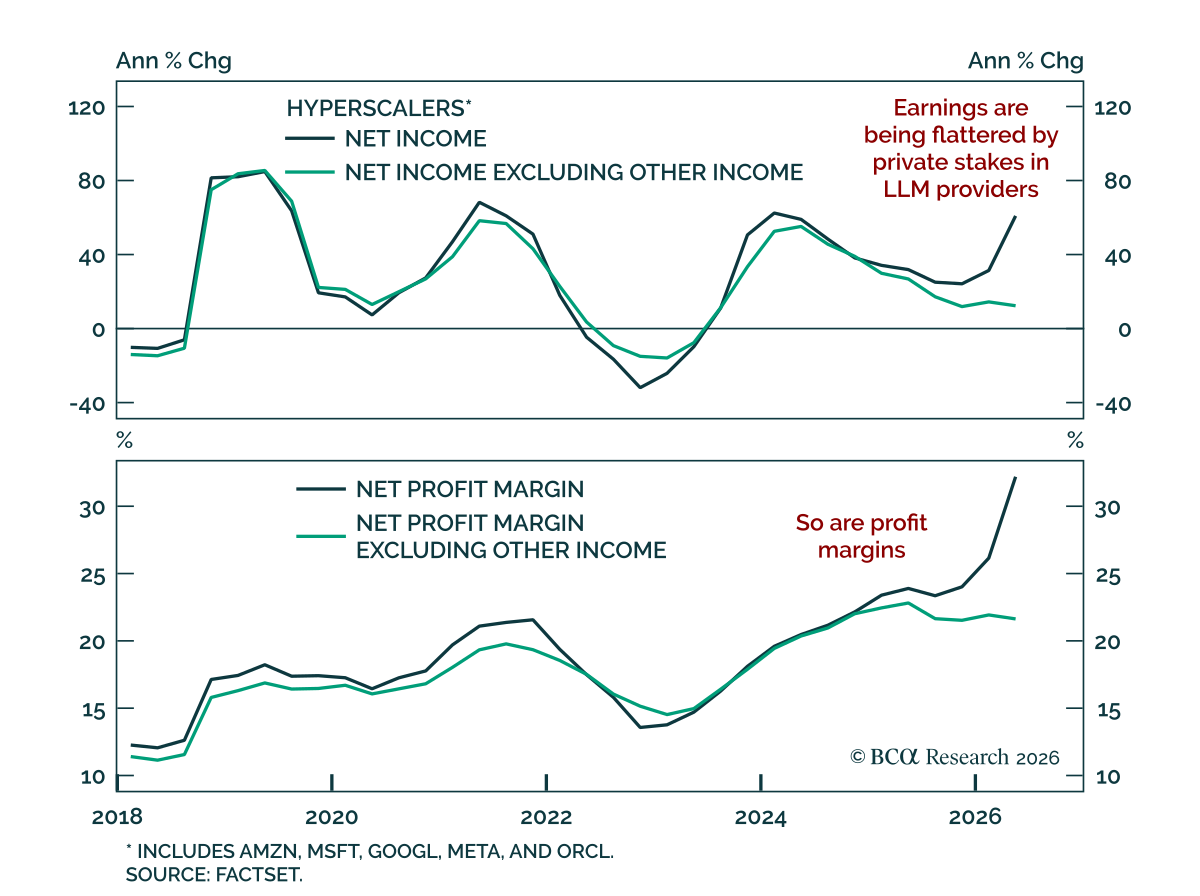
Hyperscaler earnings are increasingly flattered by AI cross-ownership gains, while the same AI ecosystem is facing rising pressure from cheaper Chinese models. The latest hyperscaler results show how large the accounting distortion has become. Other income,…
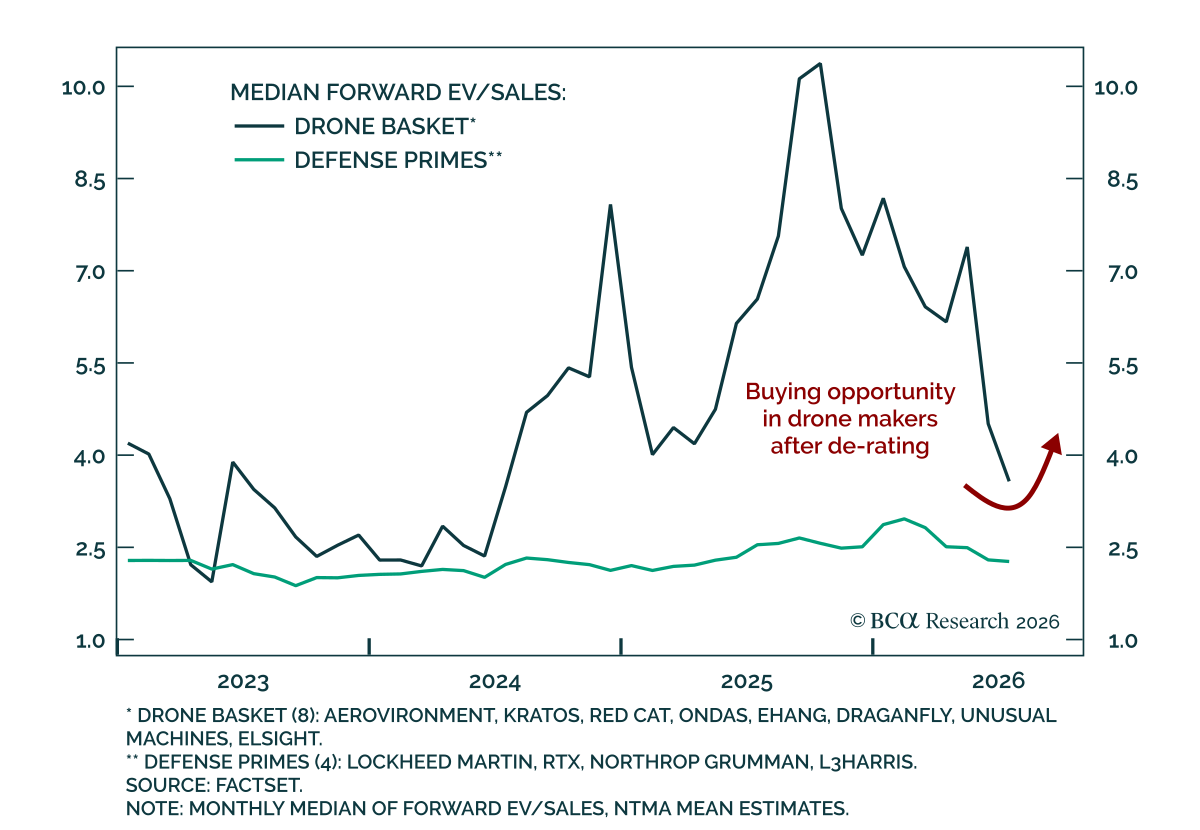
Our GeoMacro strategists are neutral on large-cap aerospace and defense and overweight drone makers. Multipolarity, international insecurity, and conflict still provide a secular tailwind for global defense spending and arms manufacturing, reinforced by the…
Special Report

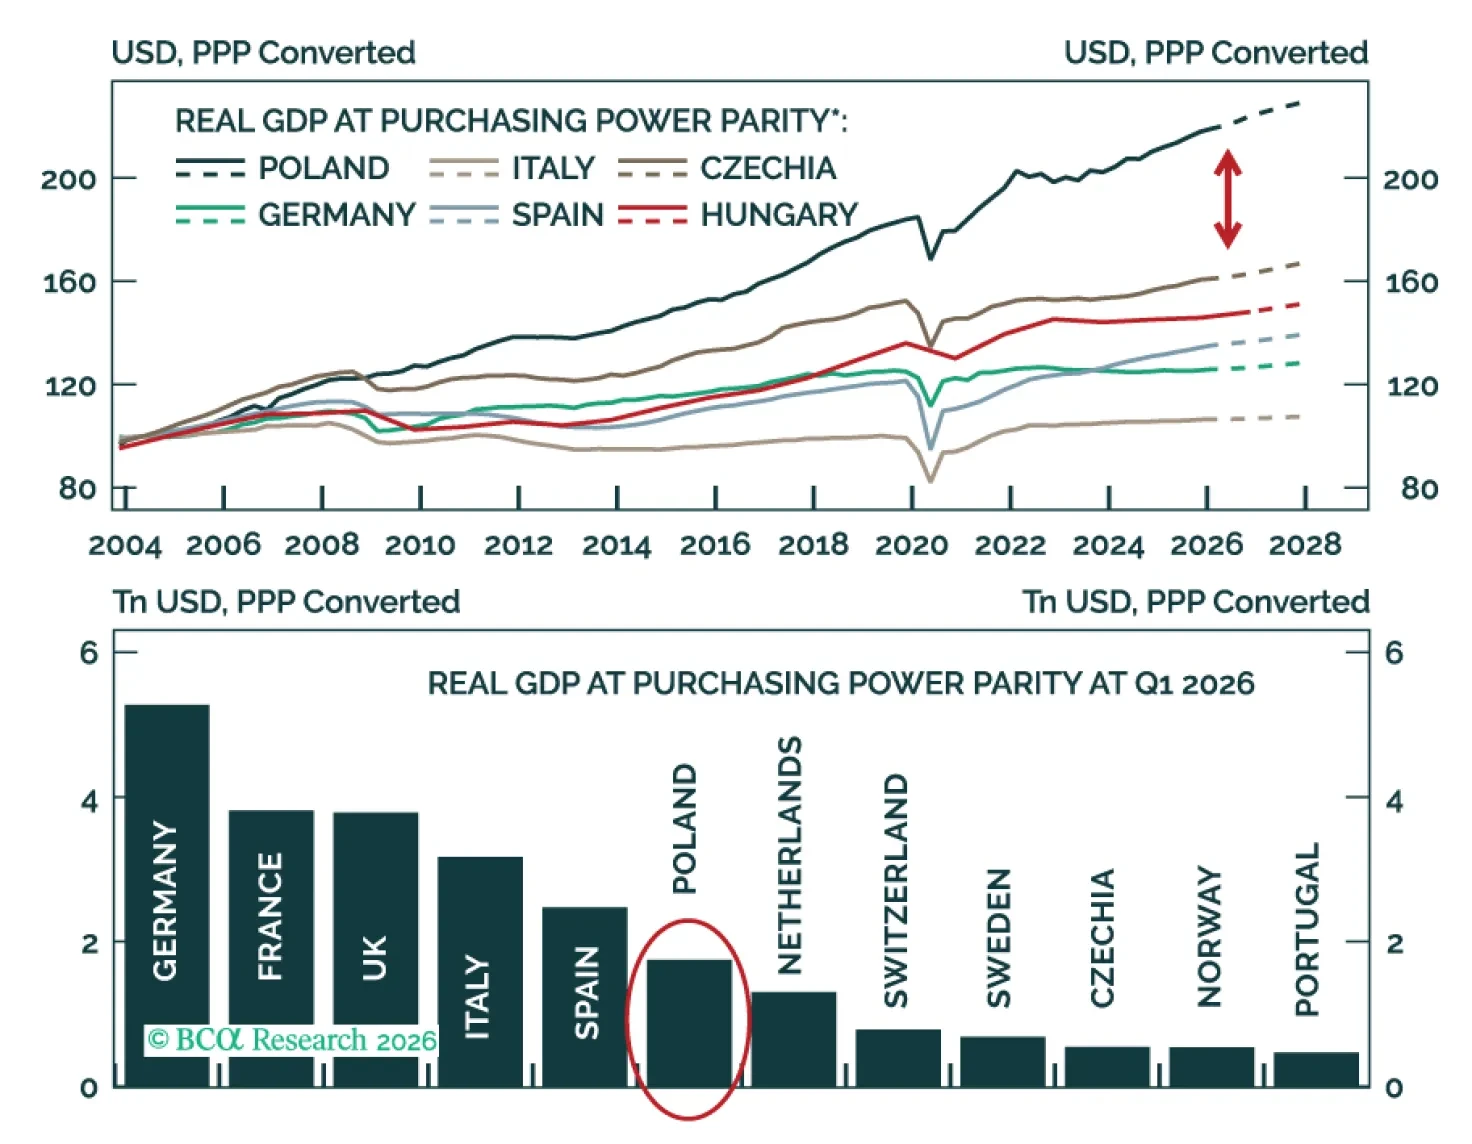
Poland’s near-term growth story remains compelling: surging EU investment should cushion European weakness and support equity outperformance. But the clock is ticking. Demographics, skills shortages, and fiscal deterioration will increasingly constrain convergence. Favor Polish equities and the belly of the curve; expect further near-term zloty weakness against the euro.
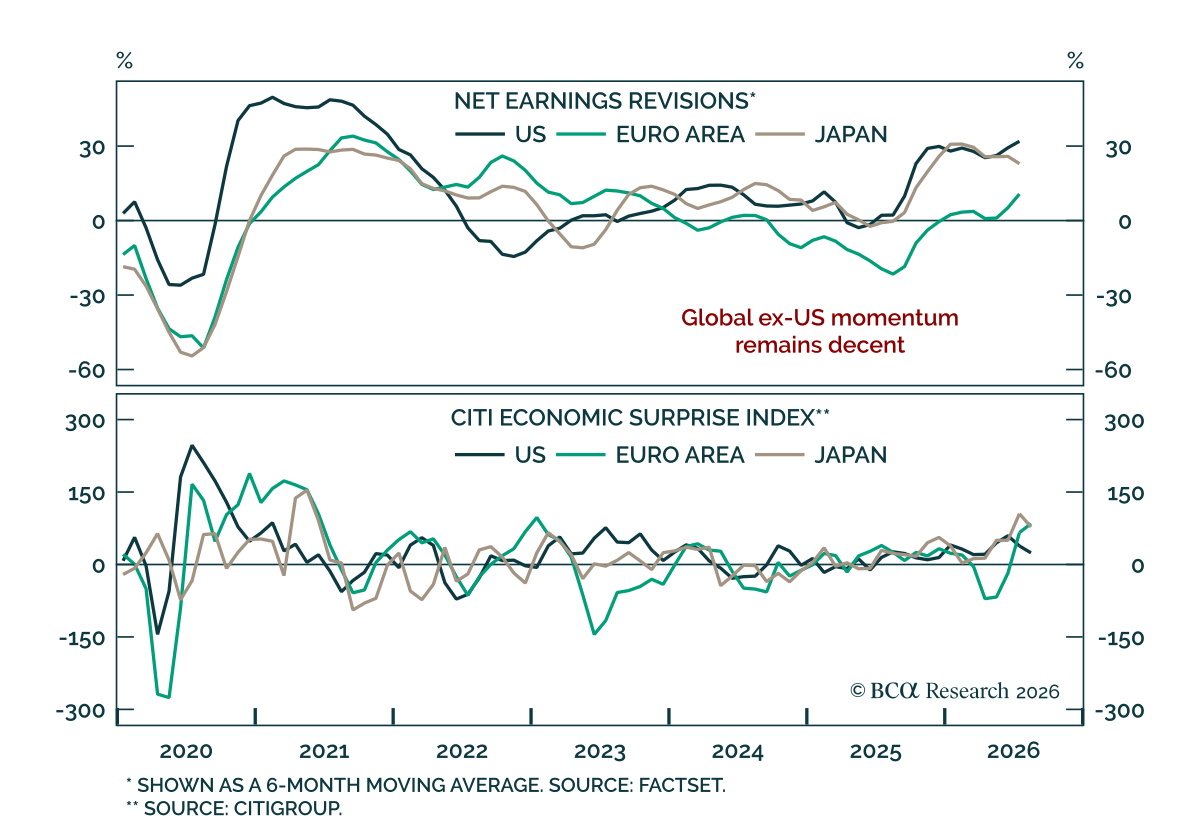
Our strategists have moved from neutral to overweight on global equities over a 12-month horizon. This is not a new bull thesis, but merely a concession that previous skepticism is not materializing. The first objection was AI monetization. The AI economy is…