Insights
Access expert research, timely insights, and exclusive webcasts to help you make confident, data-driven decisions.
Report
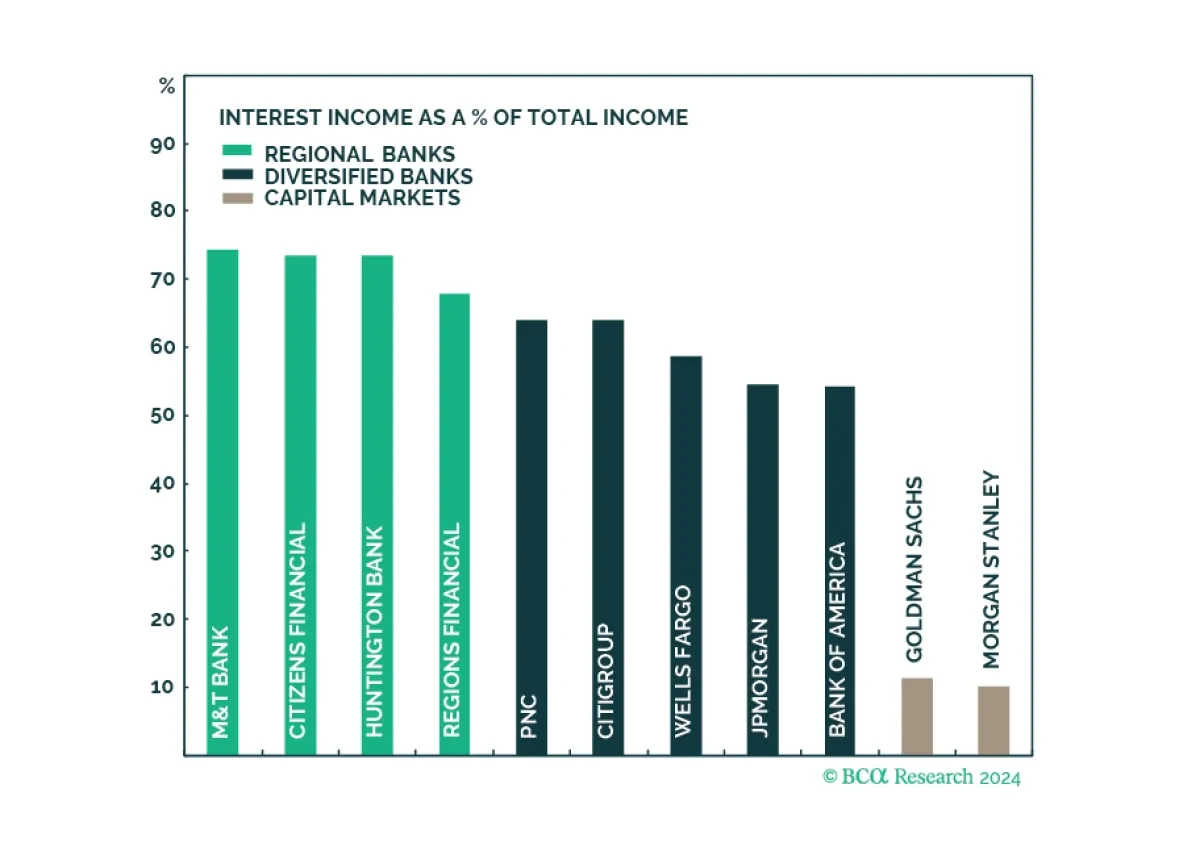
Q1 earnings results of the largest US banks have demonstrated that the engine of recent growth in profitability, NII, has faltered as funding costs are rising fast. However, the resurgence in non-NII thanks to a revival in corporate activity has been a saving grace. Earnings growth appears to have b...
Read more
Report
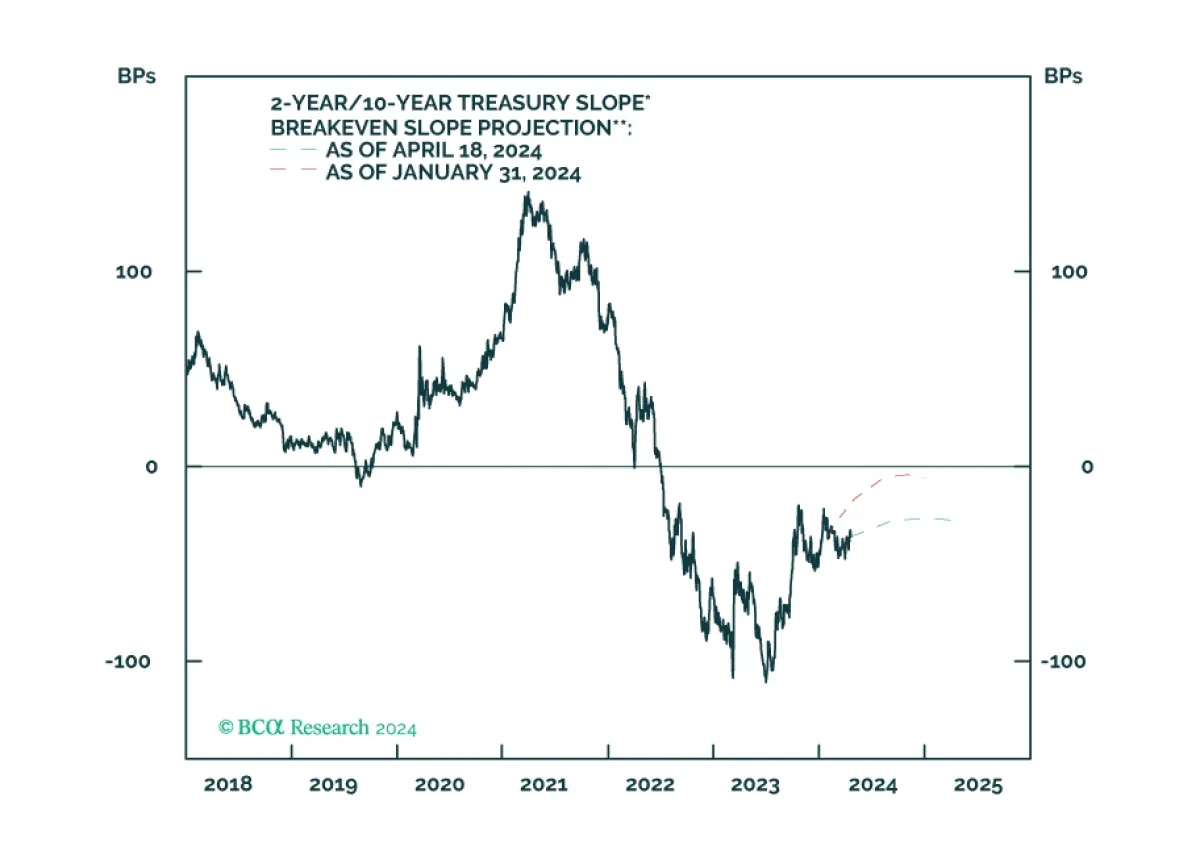
This Special Report introduces a framework for assessing the relative importance of slope change and initial yield in curve trade performance. The yield penalty for curve steepeners has fallen significantly since the beginning of the year, and we recommend shifting out of Treasury curve flatteners a...
Read more
Report
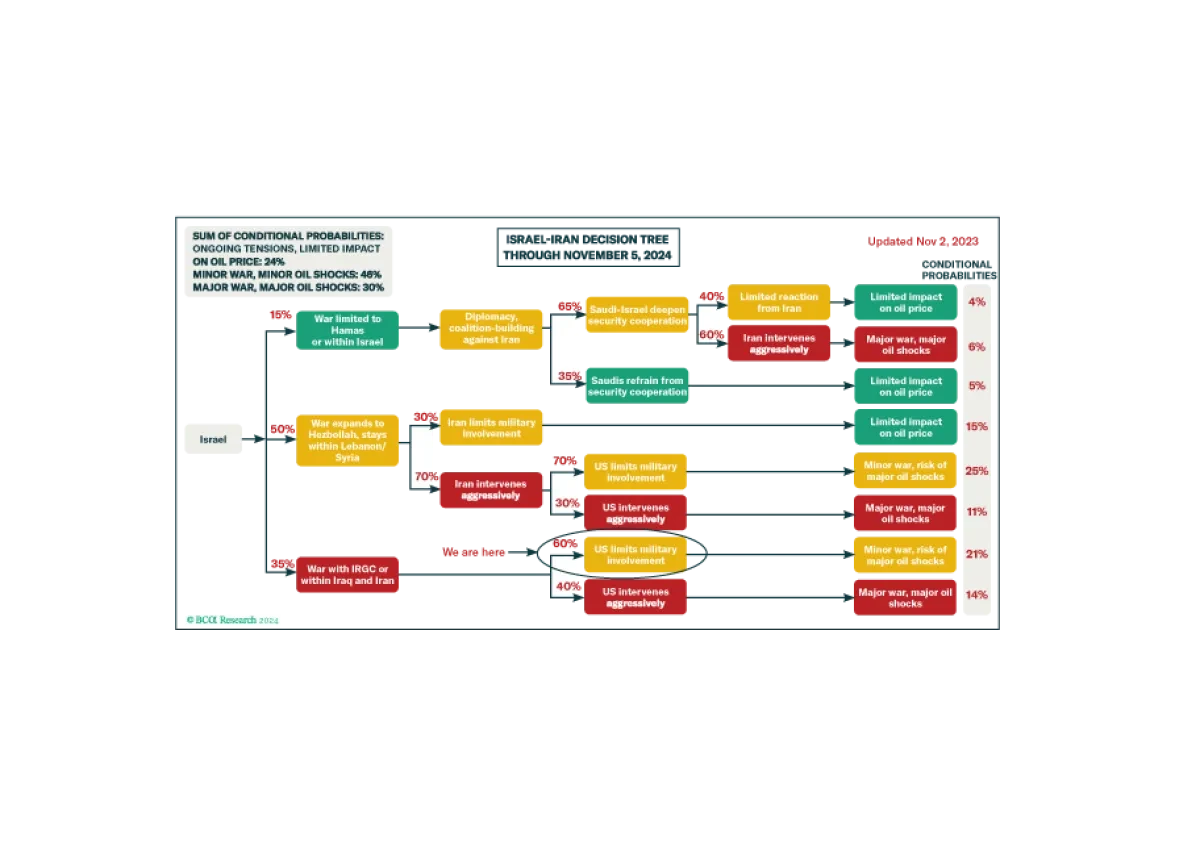
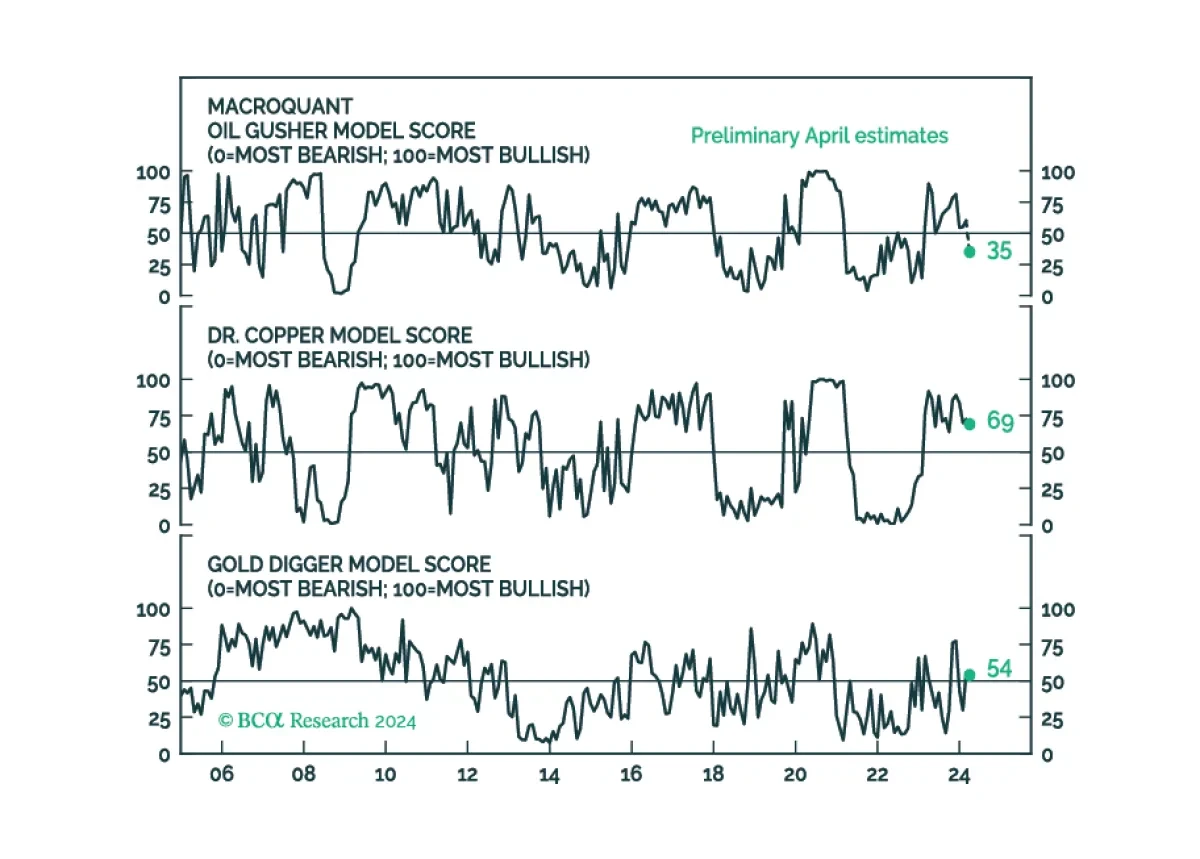
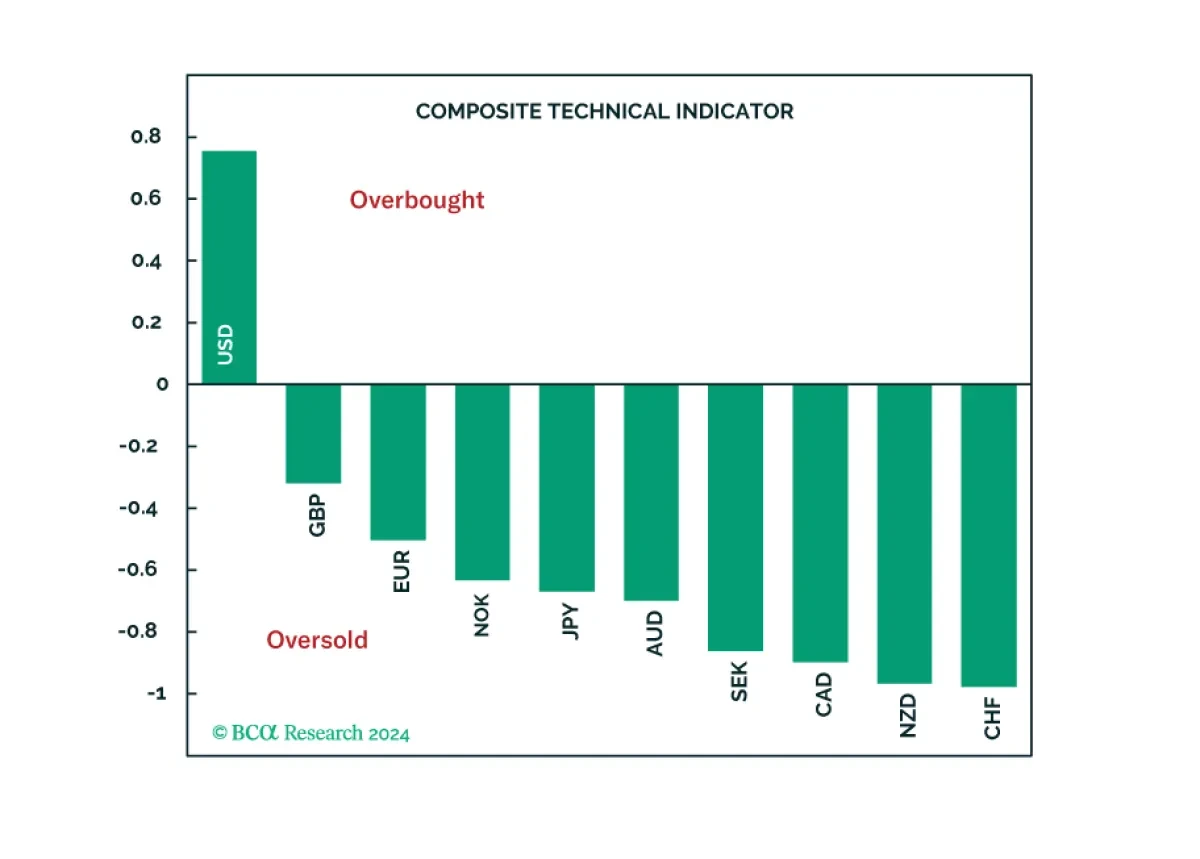
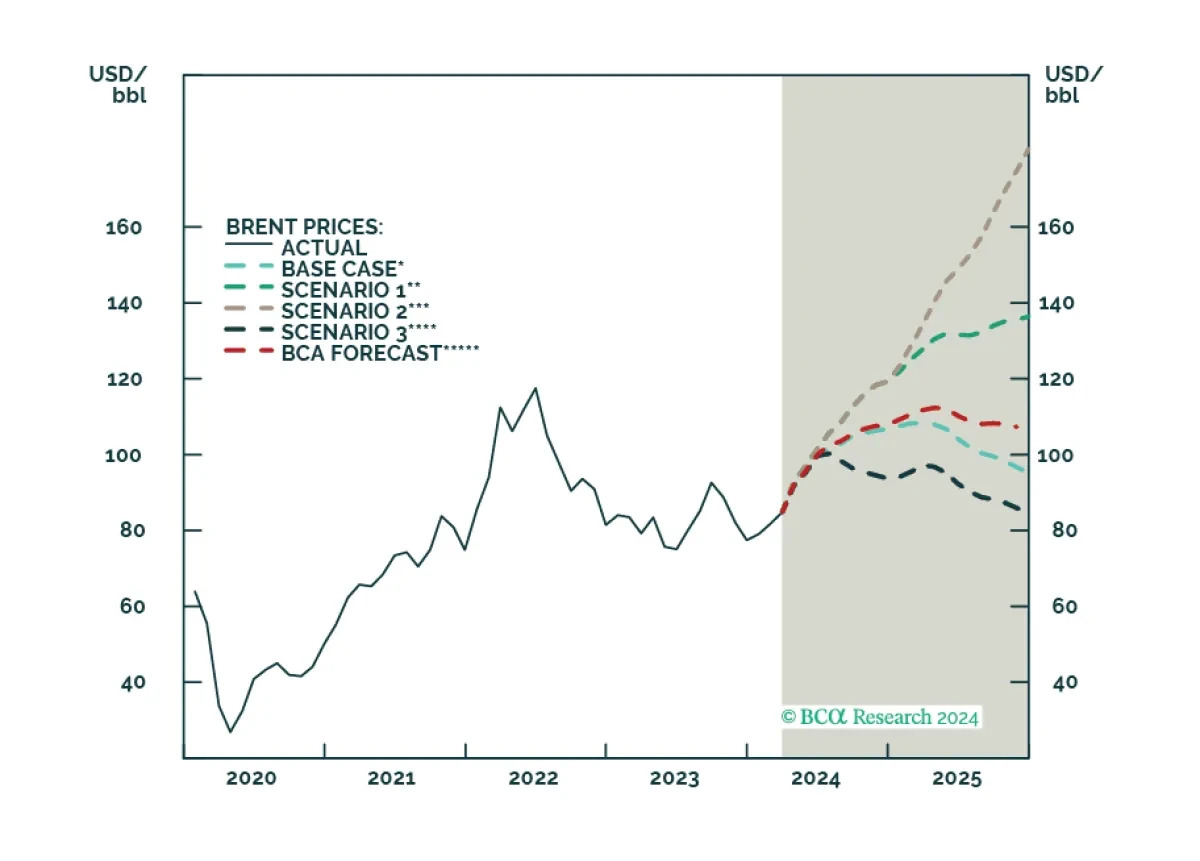
Strong growth in the US and large EMs ex-China will translate into higher oil demand in 2024 – 2025. With mostly unchanged oil supply, tighter markets will ensue. We’ve raised our 2024 average Brent forecast to $98/bbl, and expect $105/bbl in 2H24. In 2025, we expect Brent to average $110/bbl. Price...
Read more
Report
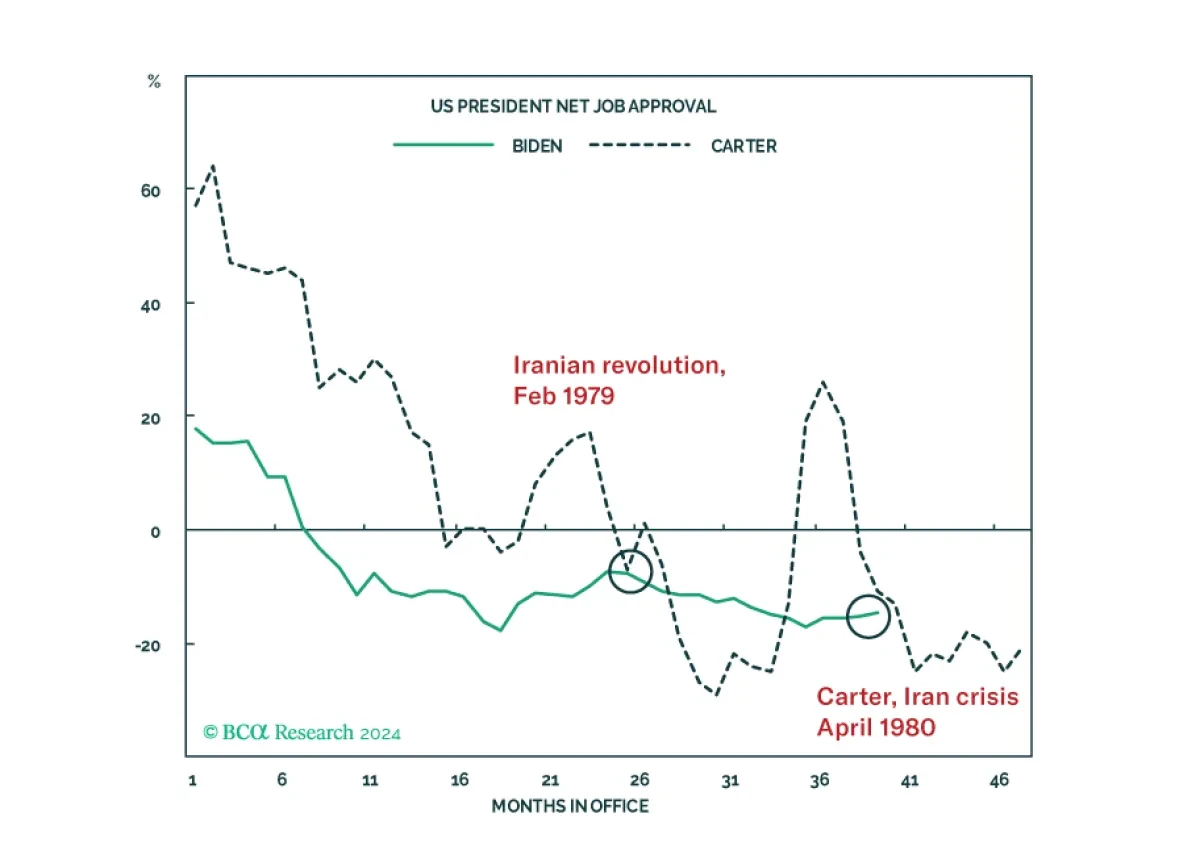
Our quant models suggest Democrats are still slightly favored for the White House. Our Senate model favors Republican control, though Montana and Ohio are the weak links that could deliver Democrats a de facto Senate majority in the event they keep the White House. But there are still six months bef...
Read more
Report
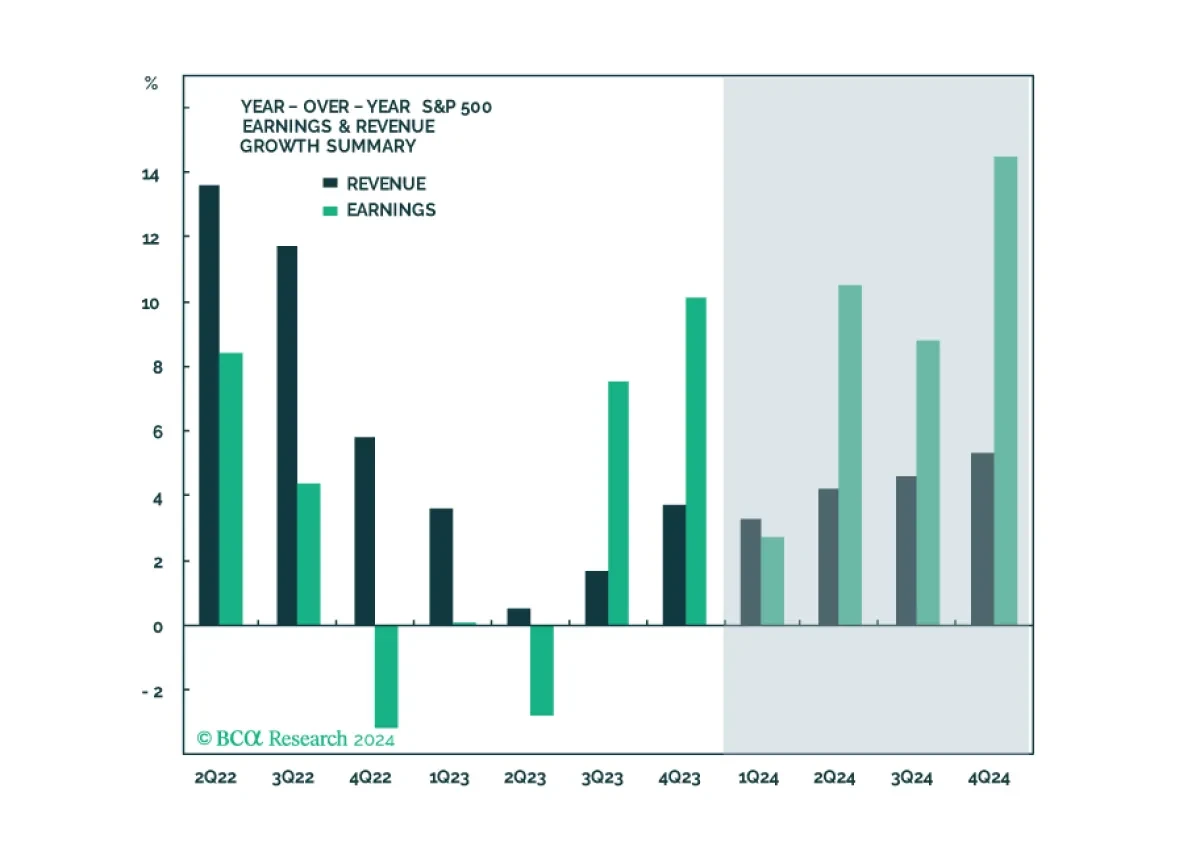
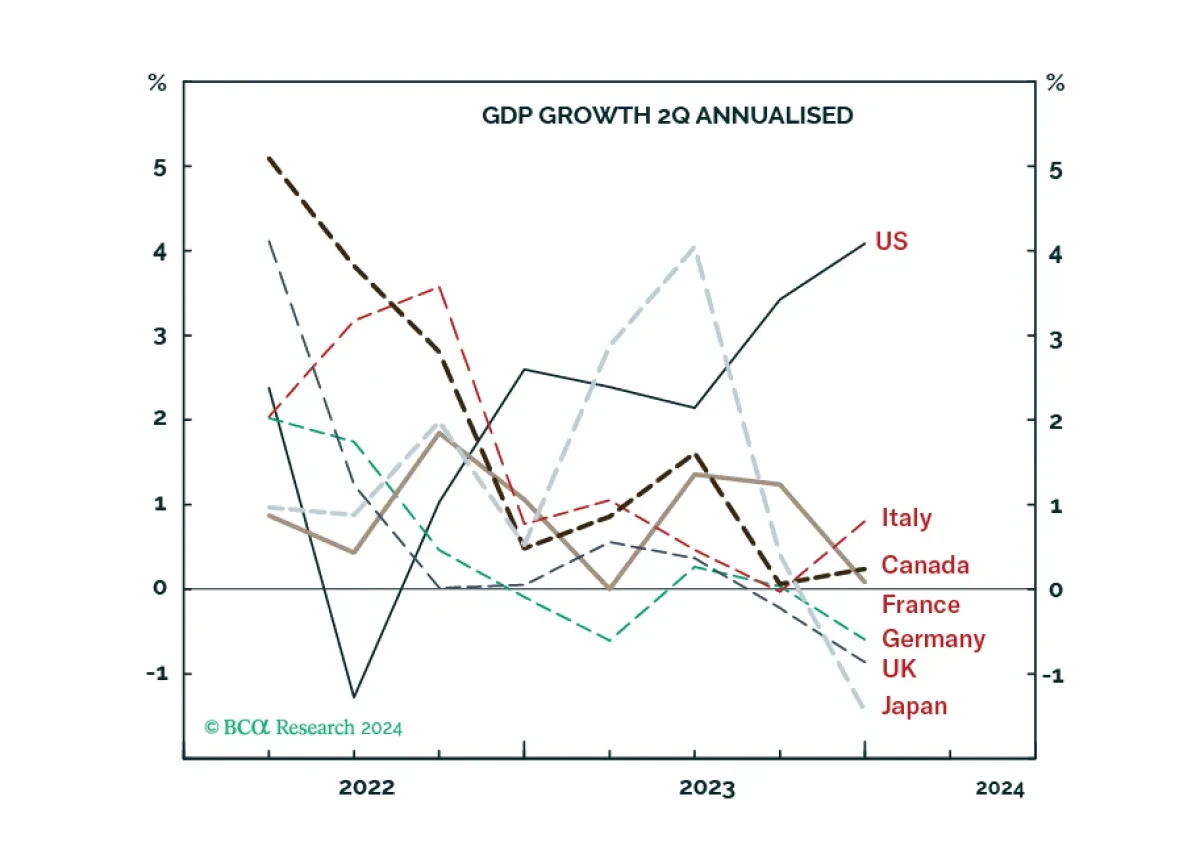
Unlike most advanced economies that are flirting with recession due to weak demand, the ‘inverted’ US economy is motoring along due to strong supply, from a combination of surging labour participation and surging immigration. We go through the implications for stocks, bonds, interest rates, and the ...
Read more