Sorry, you need to enable JavaScript to visit this website.
Skip to main content

Insights

Access expert research, timely insights, and exclusive webcasts to help you make confident, data-driven decisions.
f_image_20231201_152611.PNG
Report
The recent uptick in European economic data will not last beyond the next six months. How will European corporate credit perform in this context? ...
Read more
f_image_20231201_155838.PNG
Report
MacroQuant is overweight bonds and cash and underweight equities....
Read more
F_IMAGE_20231201_152644.PNG
Report
Treasury yields will sketch out a range between now and Q1 2024, with the upside determined by inflation and the downside determined by labor markets. ...
Read more
F_IMAGE_20231130_165005.PNG
Report
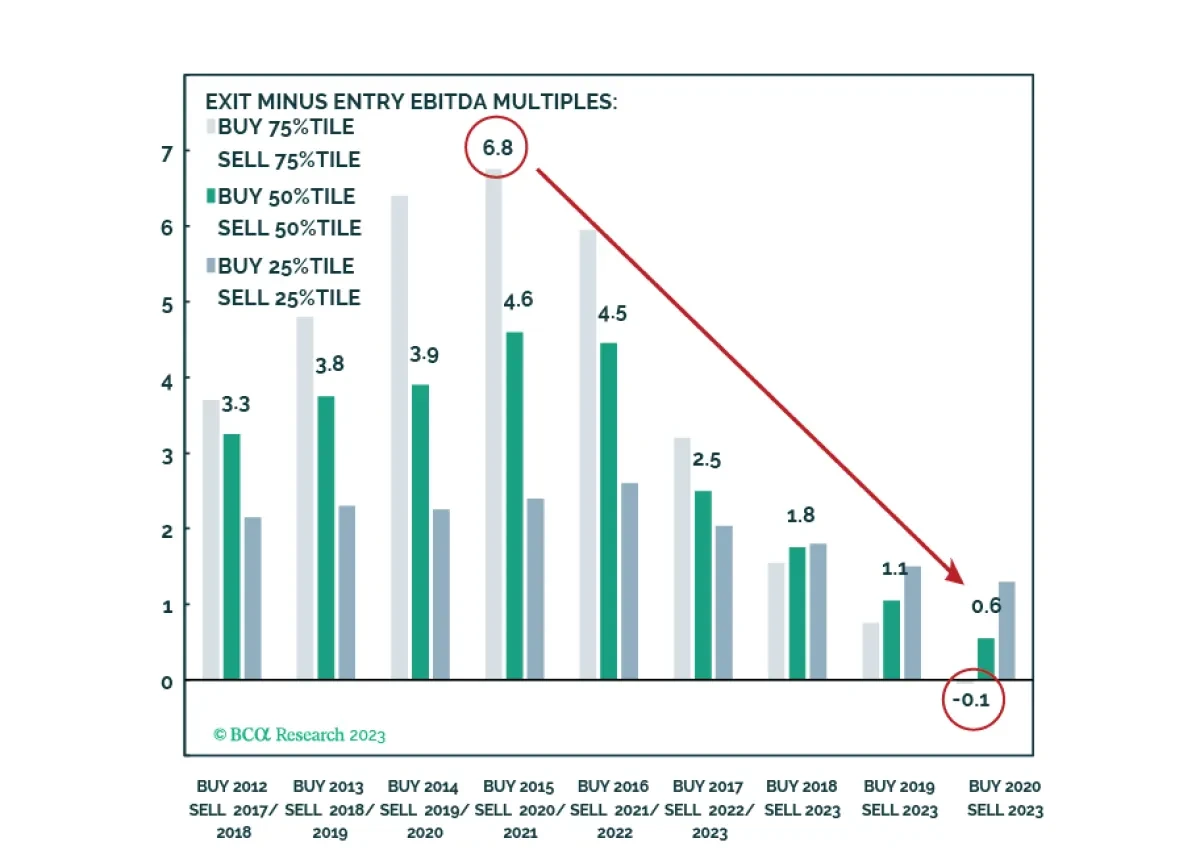
The next dollar into Private Equity carries more time and opportunity cost risk. We do not see a high risk of permanent capital loss for the next vintages; existing vintages we do. While our primary focus revolves around the next dollar, it is valuable to comprehend the risks associated with current...
Read more
f_image_20231201_113439.PNG
Report
In this Insight, we discuss the outlook for monetary policy in New Zealand after this week’s RBNZ policy meeting, and introduce related fixed income and currency trade ideas....
Read more
f_image_20231130_175705.PNG
Report
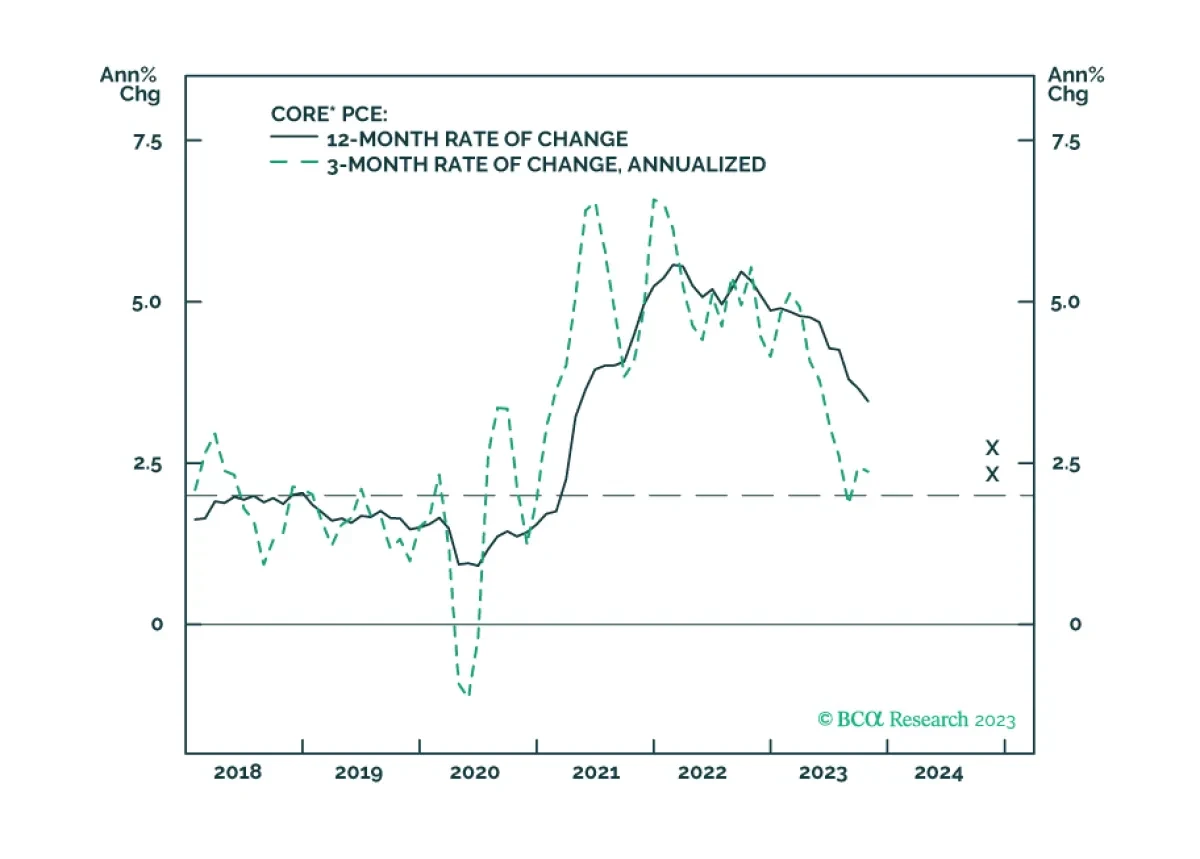
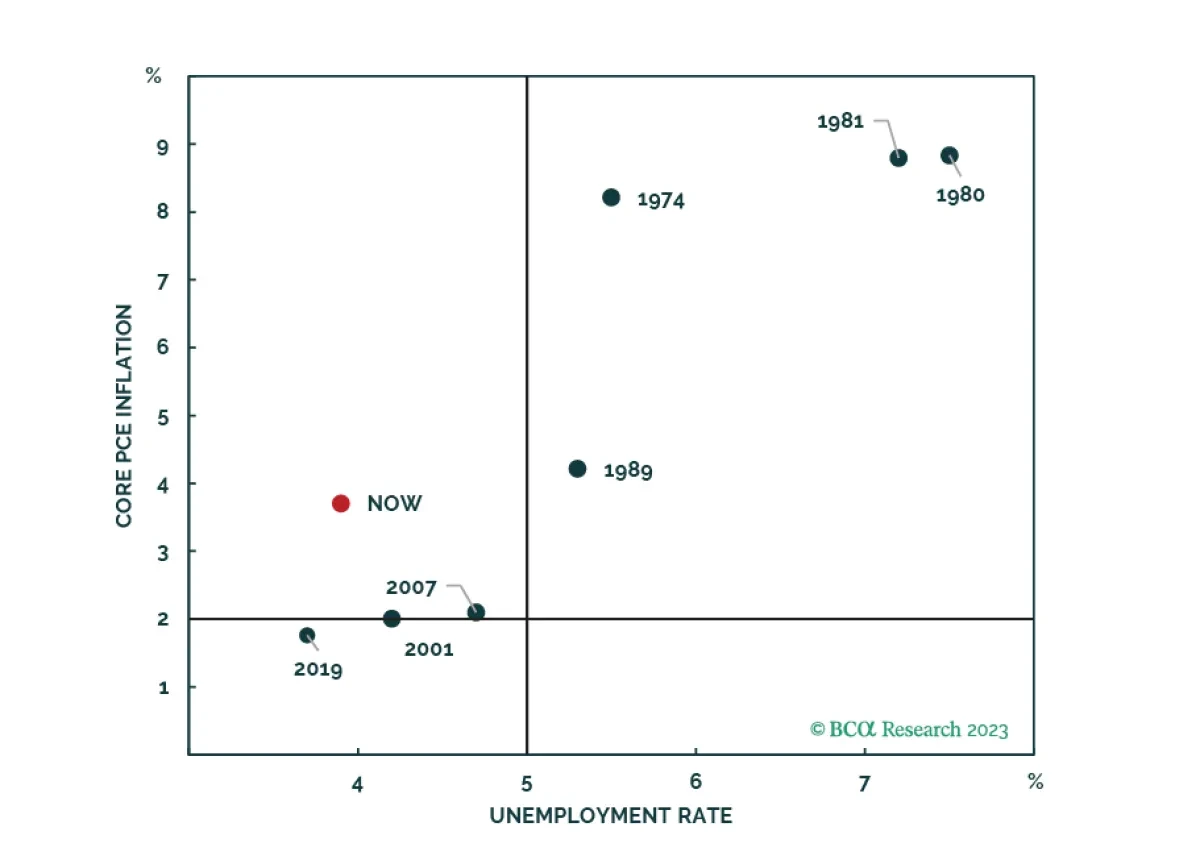
Inflation won’t fall fast enough for the Fed to cut rates preemptively before recession arrives. The risk/rewards balance is unfavorable for risk assets. Stay overweight bonds versus equities. ...
Read more
F_IMAGE_20231130_103921.PNG
Report
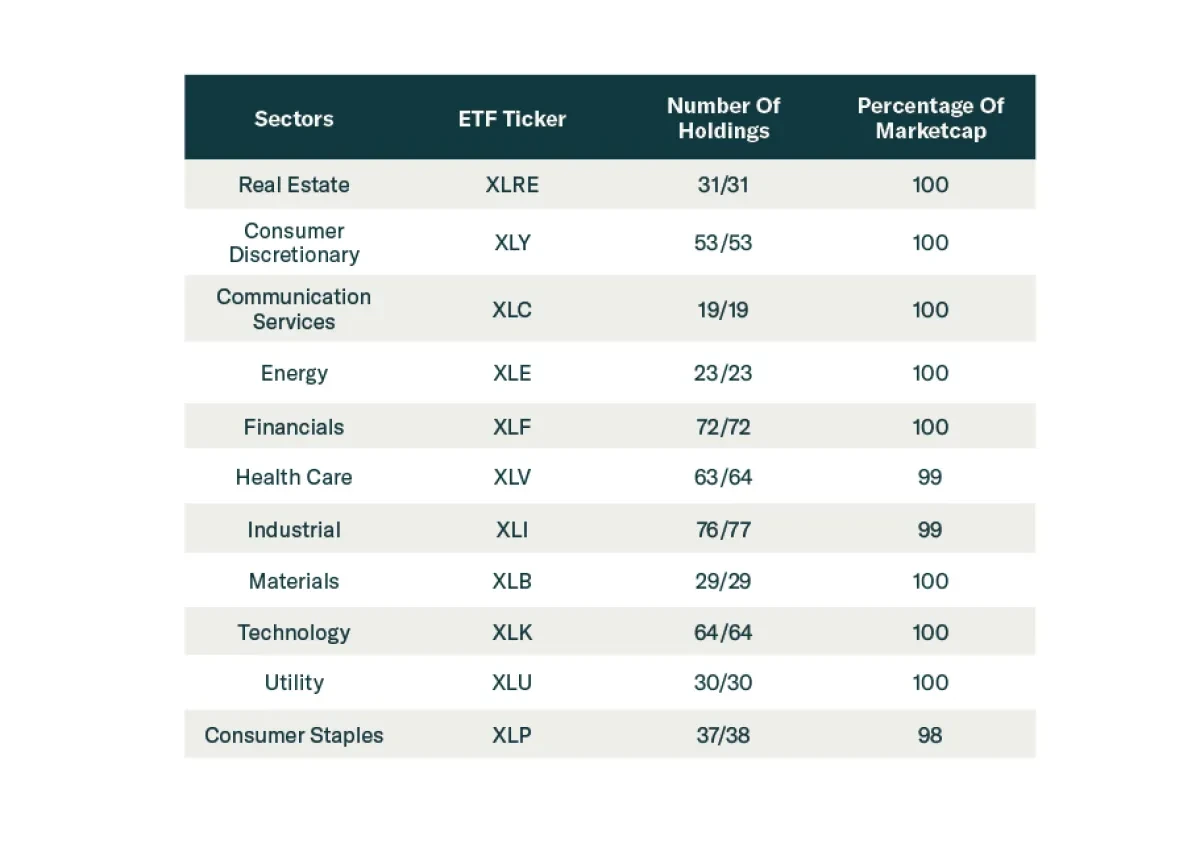
In this insight we provide links to watchlists for 15 MSCI country and 11 US GICS Sector ETFs. Clients can follow the watchlists to use them in the Screener tool and receive regular updates. ...
Read more
F_IMAGE_20231129_191225.PNG
Report
The recent increase in Korean exports will likely prove to be a mid-cycle rebound within a cyclical downtrend. Korea’s households and enterprises are among the most indebted globally, and their debt service ratio is among the highest in the world. Korea’s 10-year bond yields have peaked. We discuss ...
Read more
f_image_20231129_155344.PNG
Report
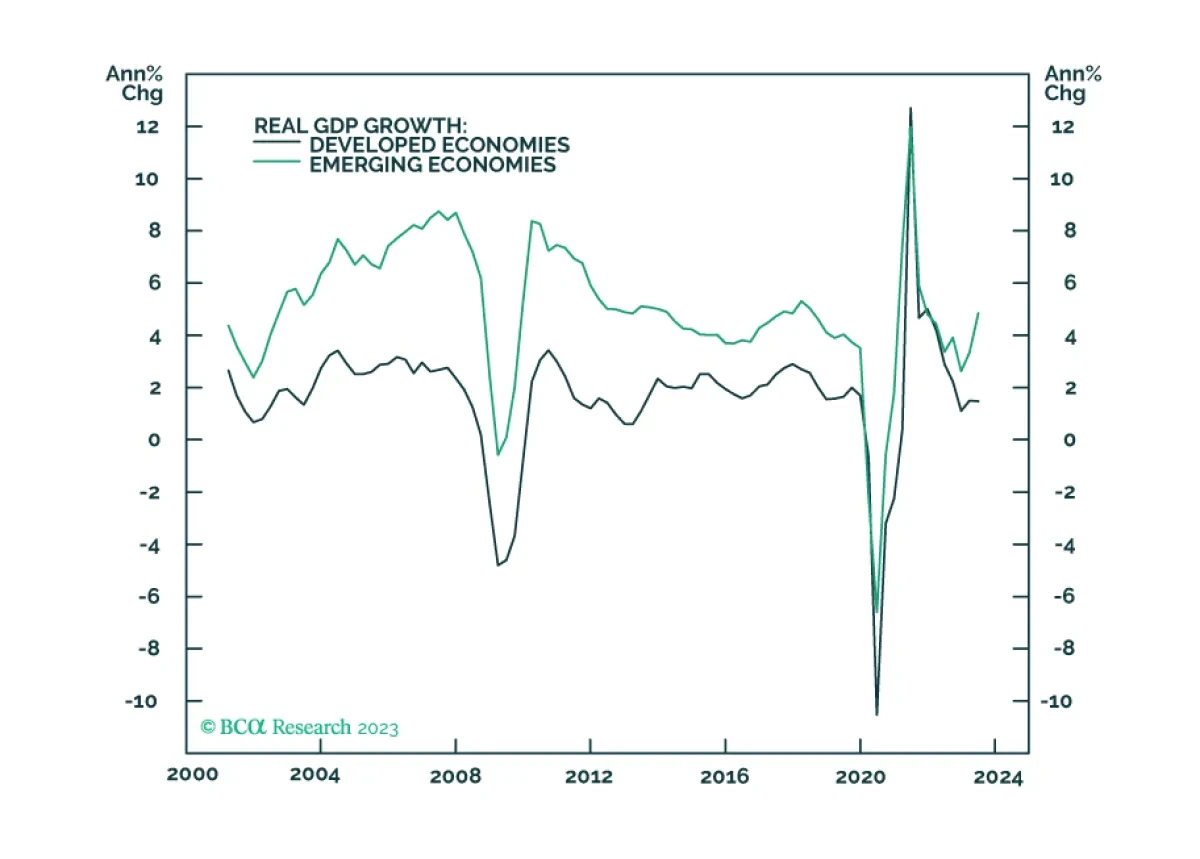
In our simulations of fairly deep global recessions averaging -1.5% in 2024 global GDP growth, we expect OPEC 2.0 to reduce output enough to offset lost demand. Even so, we find oil prices drop ~ $22/bbl – from ~ $100/bbl in 1H24 to ~ $78/bbl in 2H24. We remain long the XOP and COMT ETFs to retain...
Read more
f_image_20231129_144505.PNG
Report
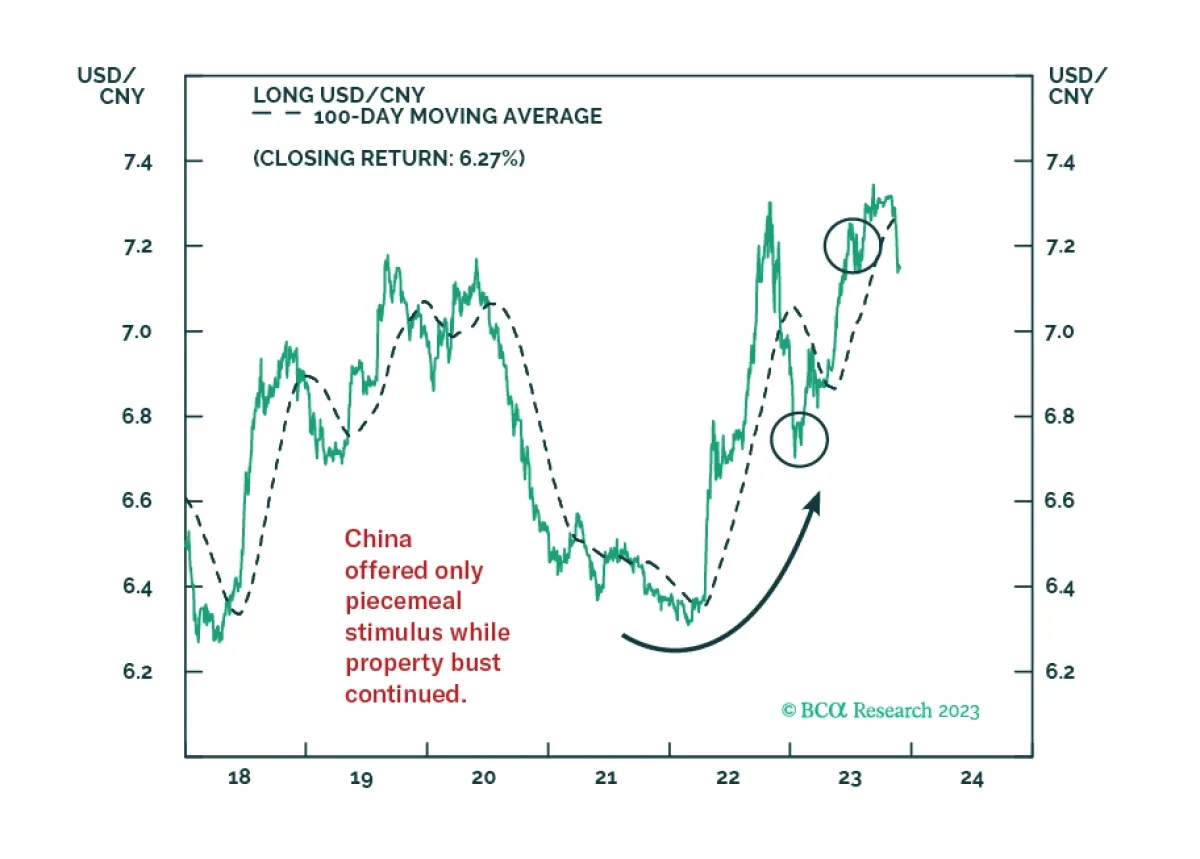
Our political forecasting scored wins in 2023 but we failed to capitalize on it adequately in our trade recommendations. ...
Read more