Latest from BCA Research
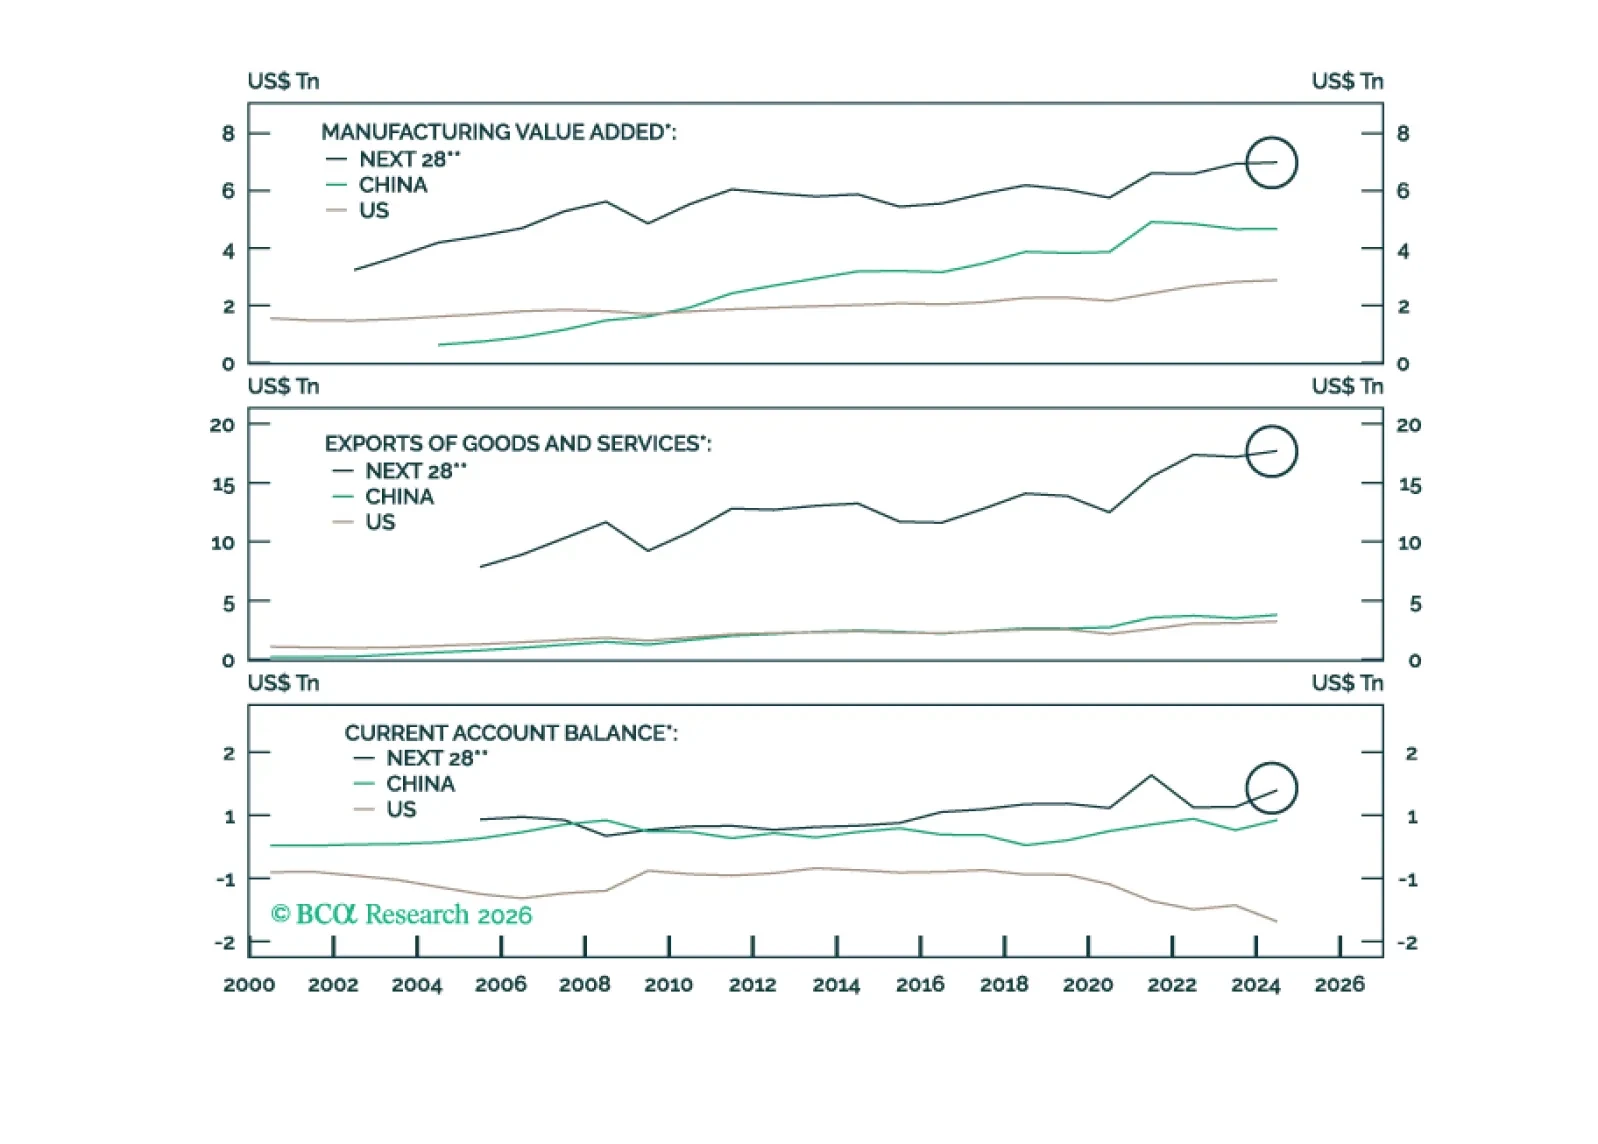
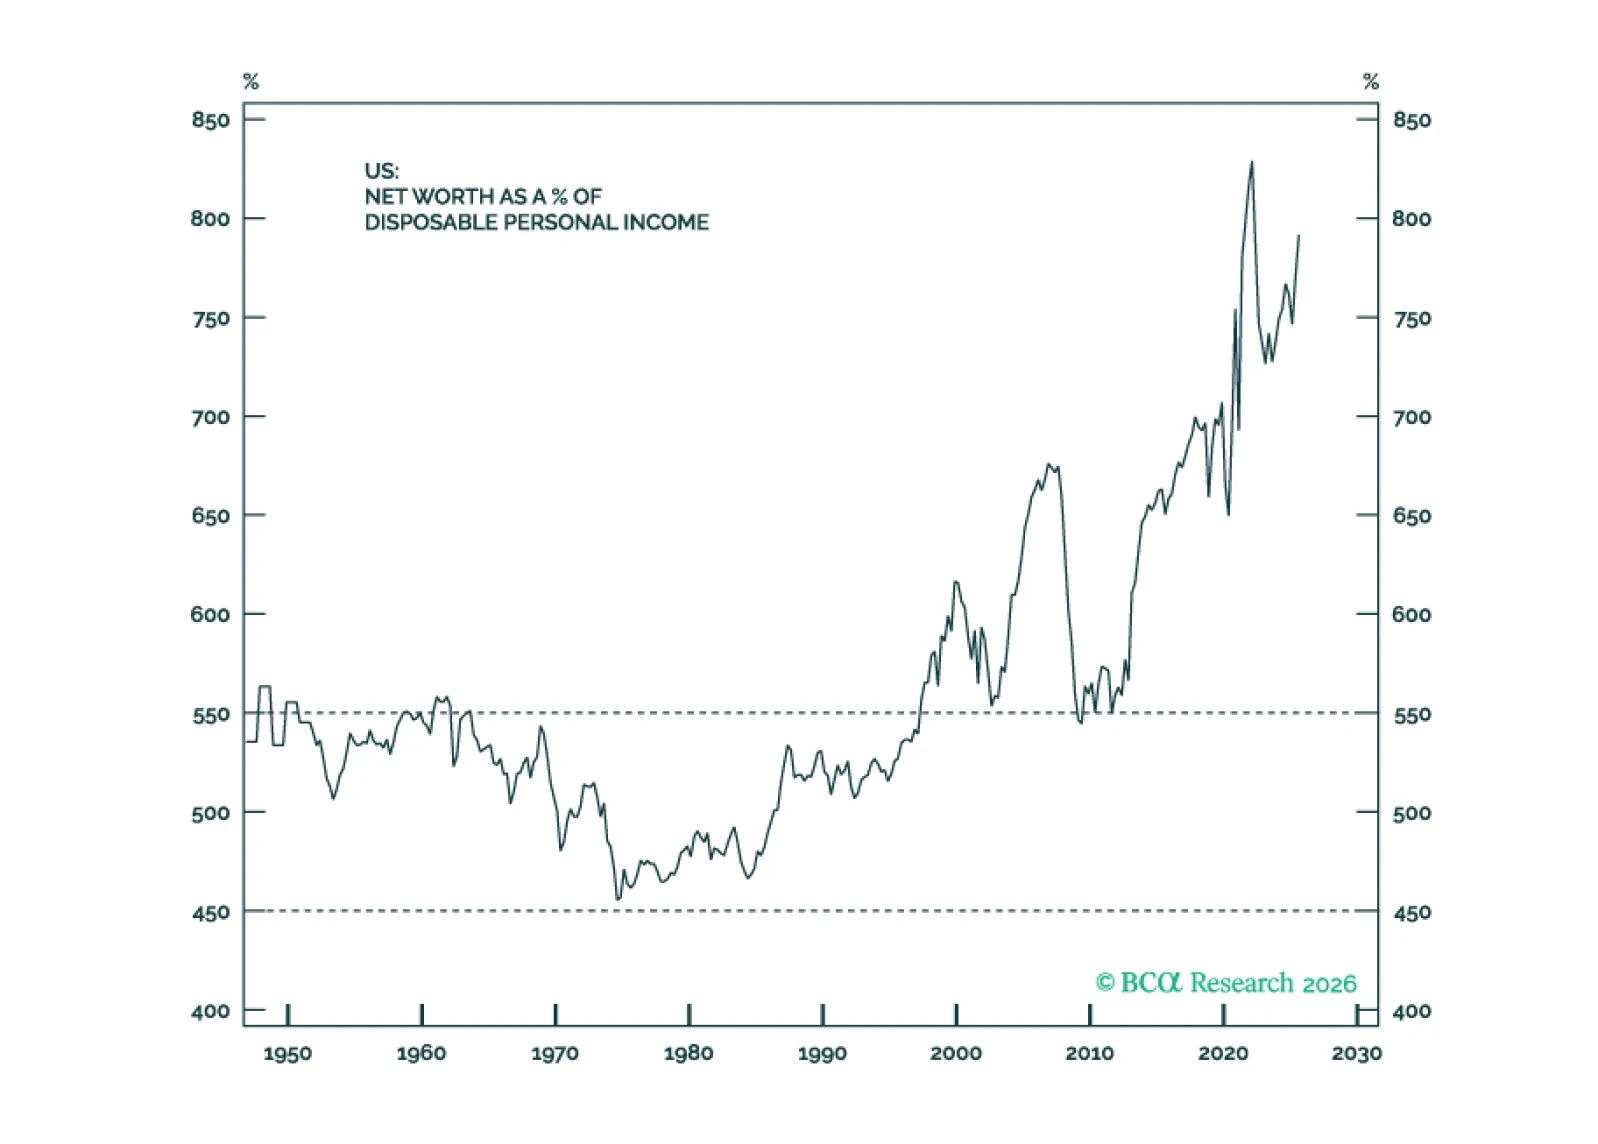
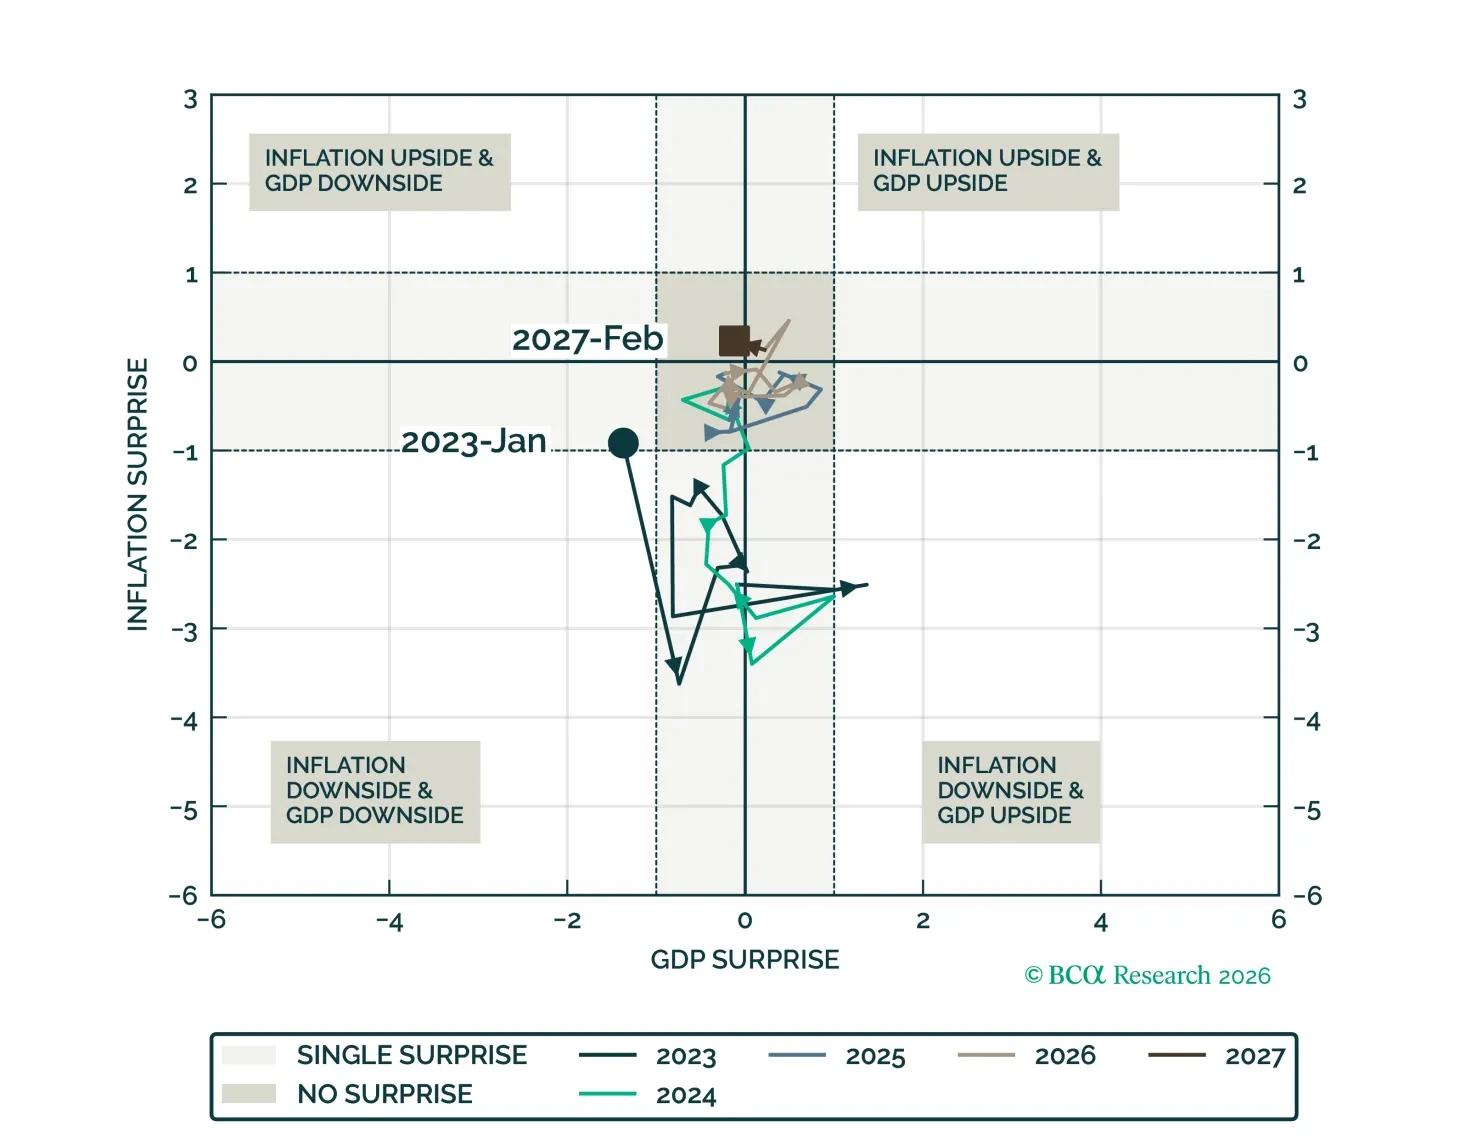
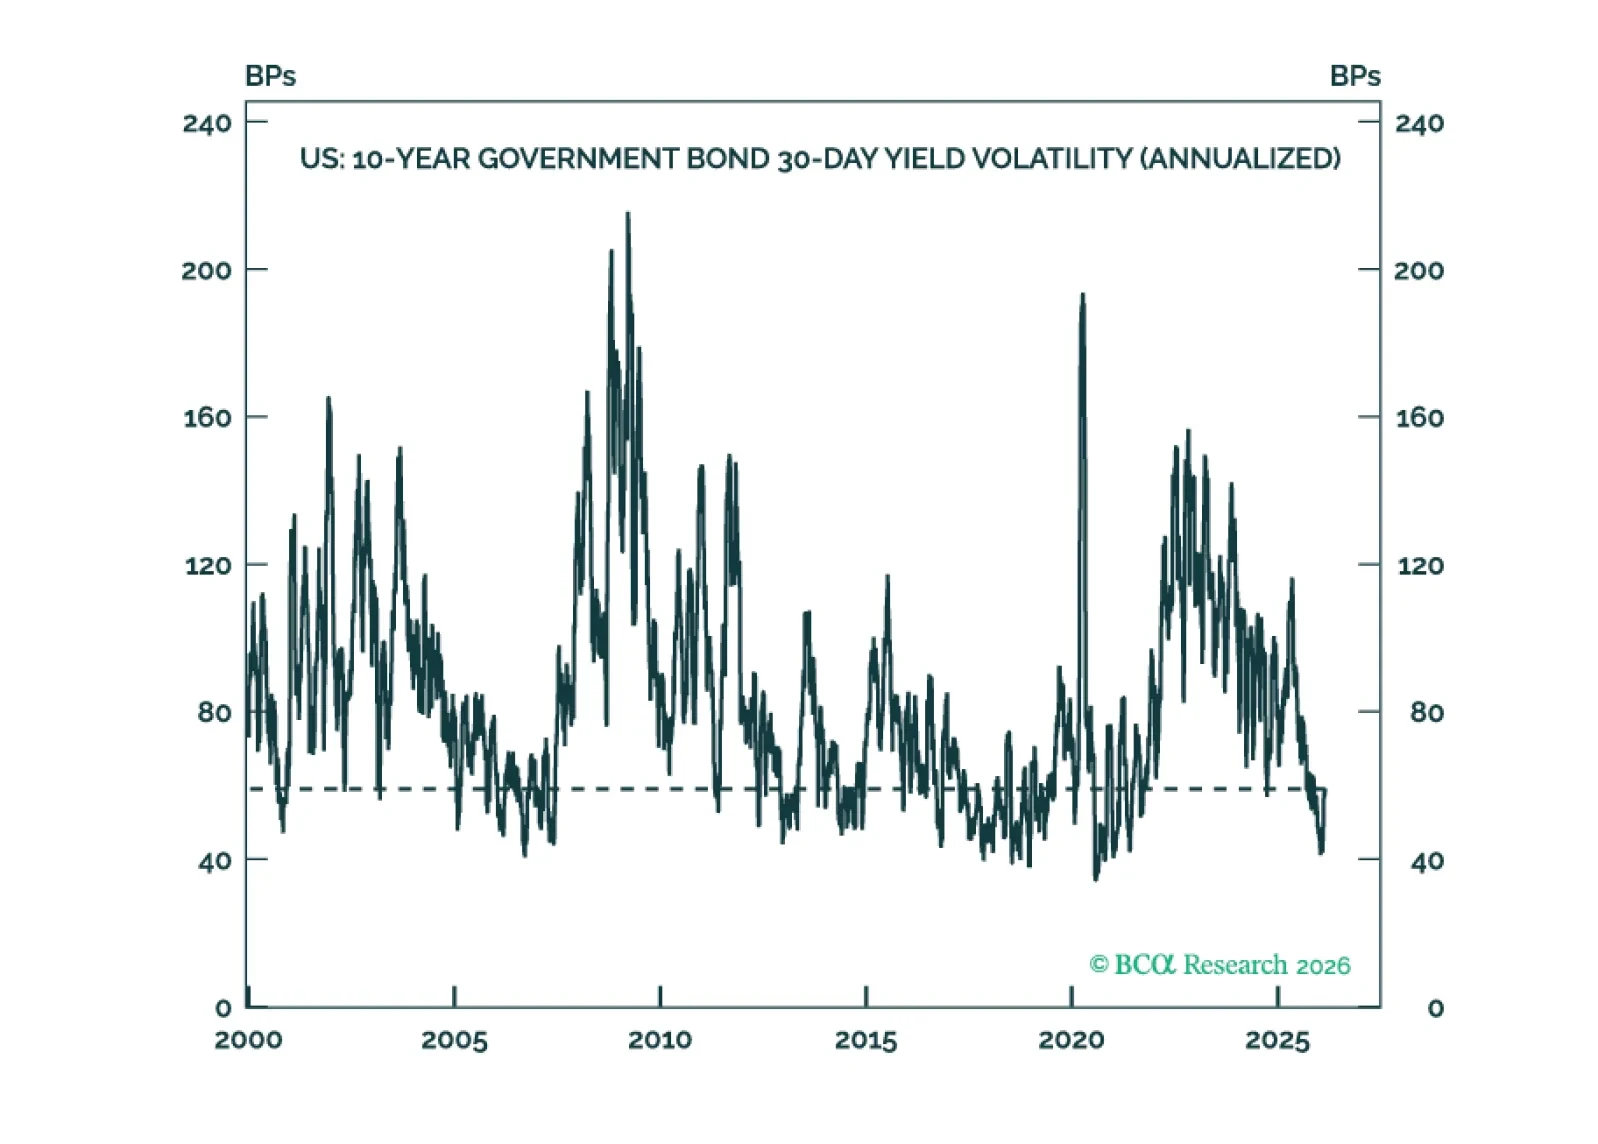
In Section I, Doug recommends cutting US equity exposure in favor of Europe as reduced recession odds make it unlikely that the US will draw safe-haven capital flows. In Section II, Jesse ranks middle economic powers across hard and soft power dimensions and recommends investing in their defense and industrial sectors.

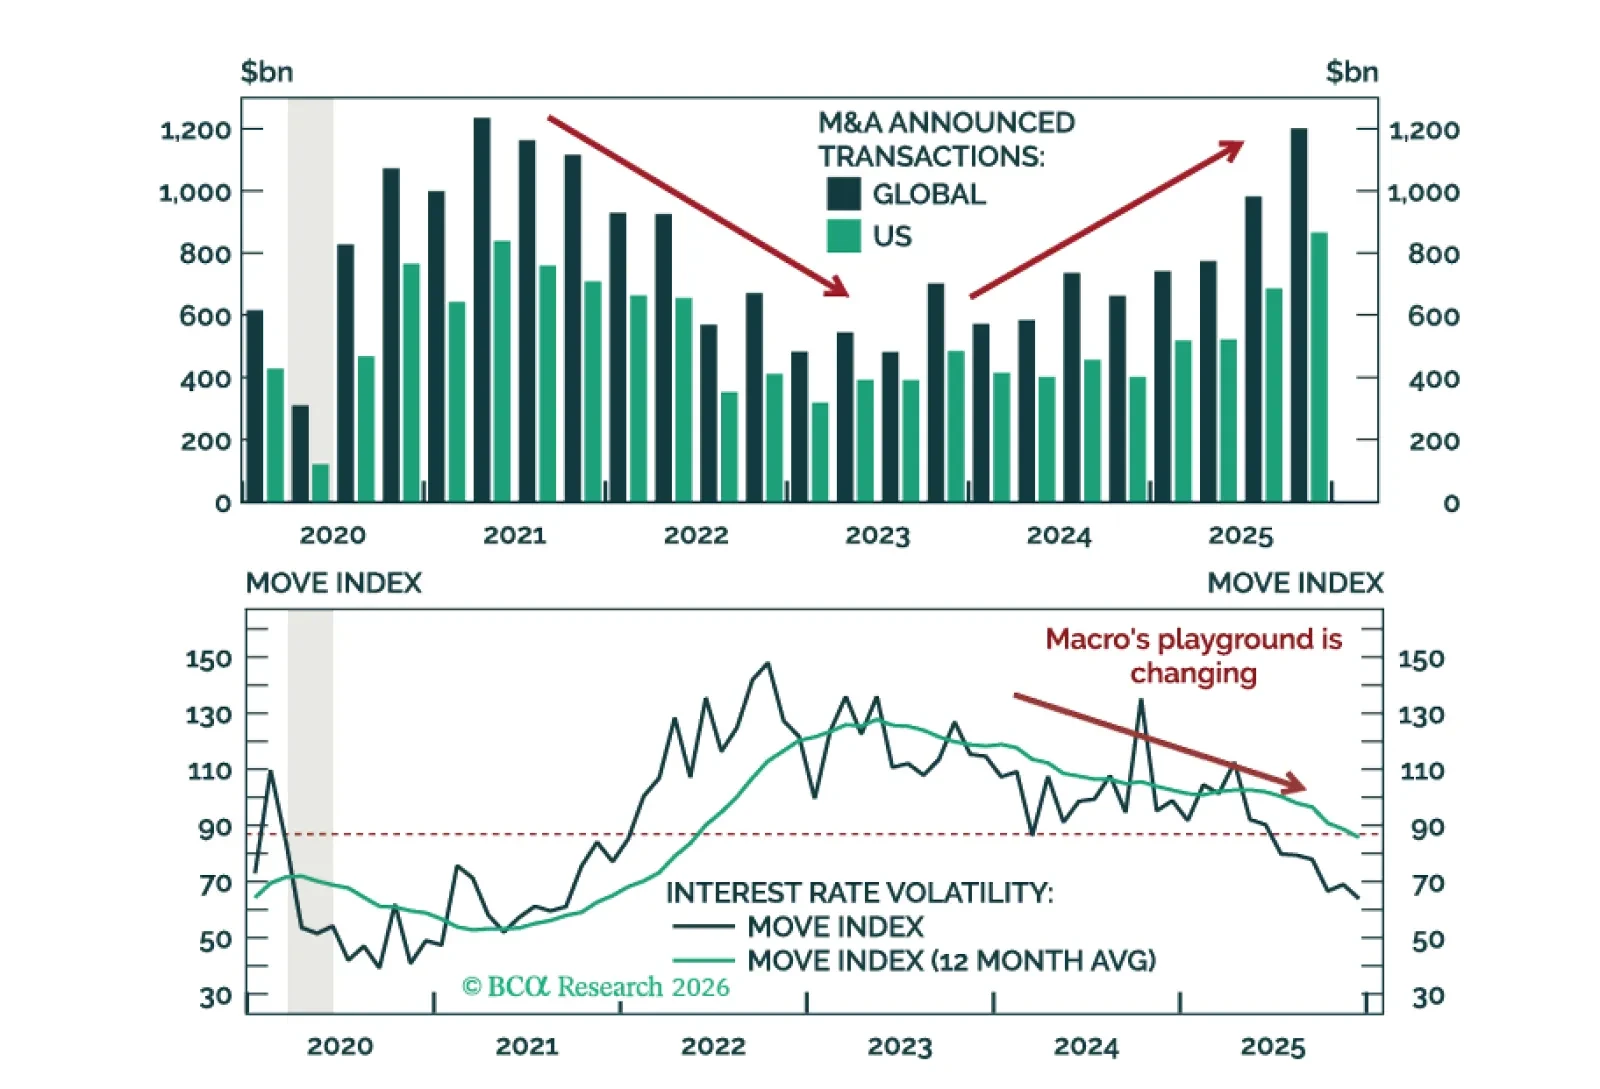
M&A activity finally reaccelerated in Q4 2025—it’s just the start. Macro Hedge Funds have outperformed with top-decile performance from Discretionary Macro—but that’s towards the end. We move Macro from overweight to underweight and Event Driven from neutral to overweight.
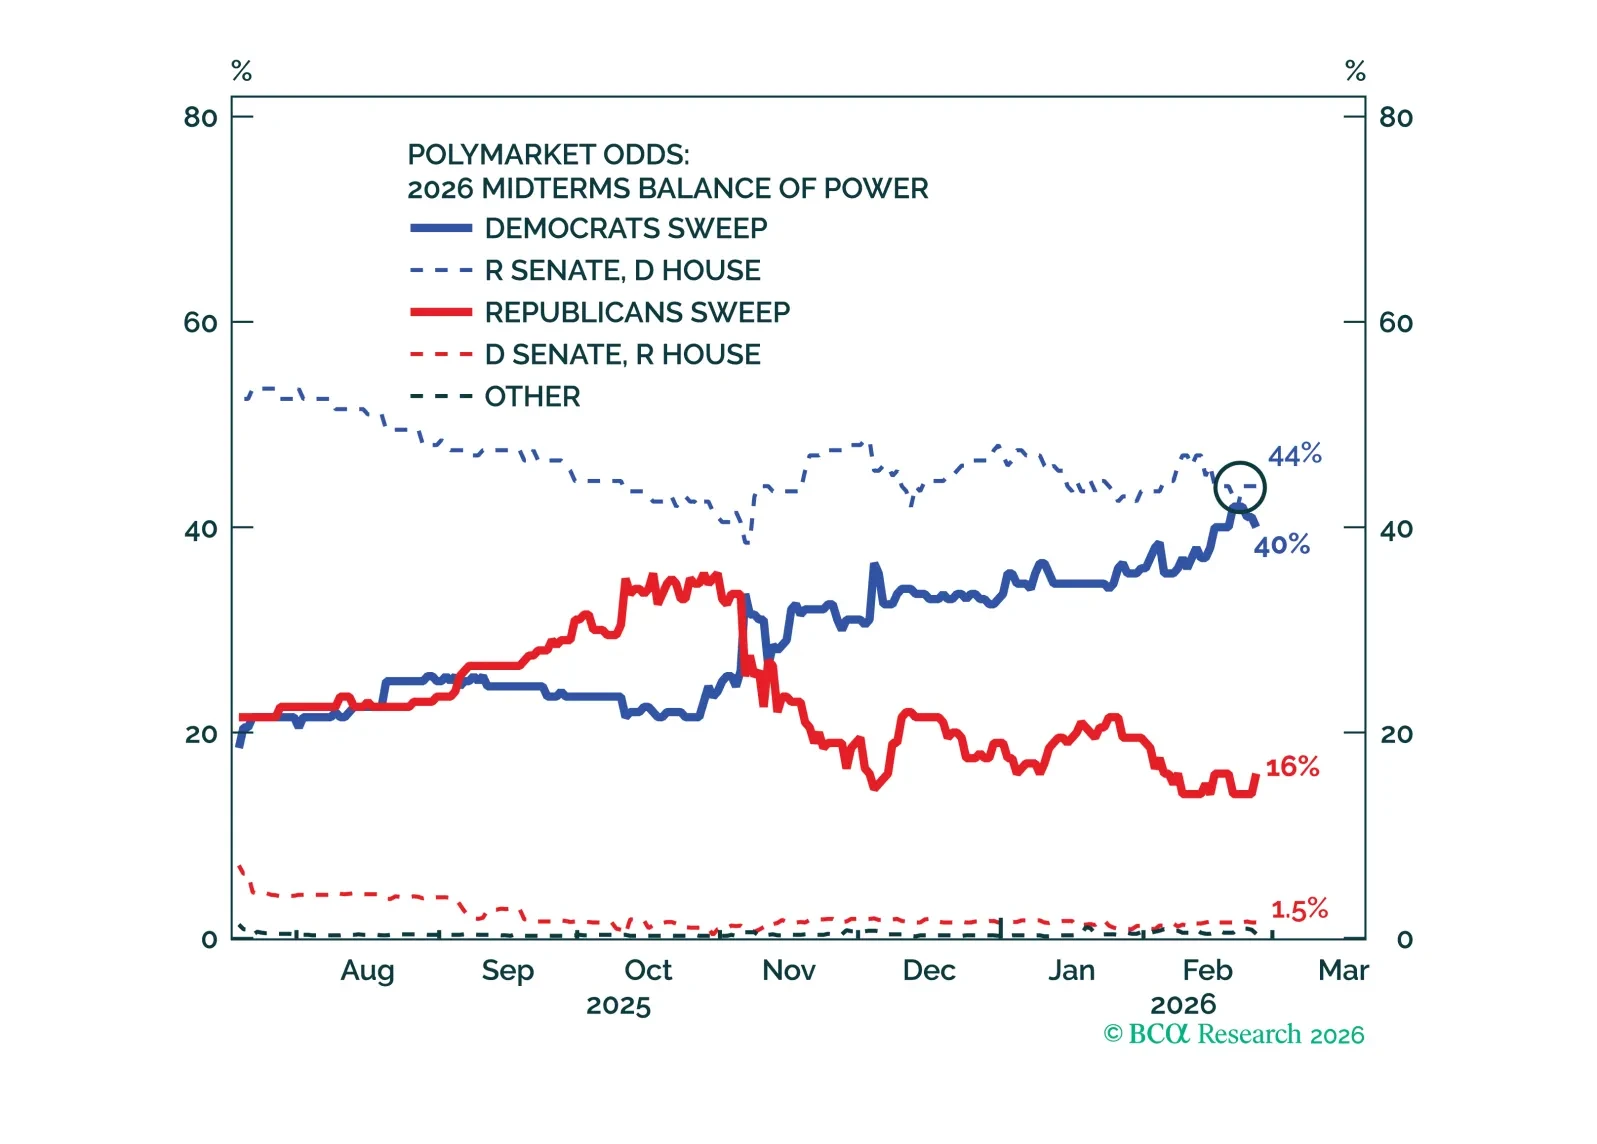
The president did not announce significant new tax cuts or economic stimulus.

This report examines the implications for Chinese exports and global trade in light of the US Supreme Court’s ruling on tariffs.
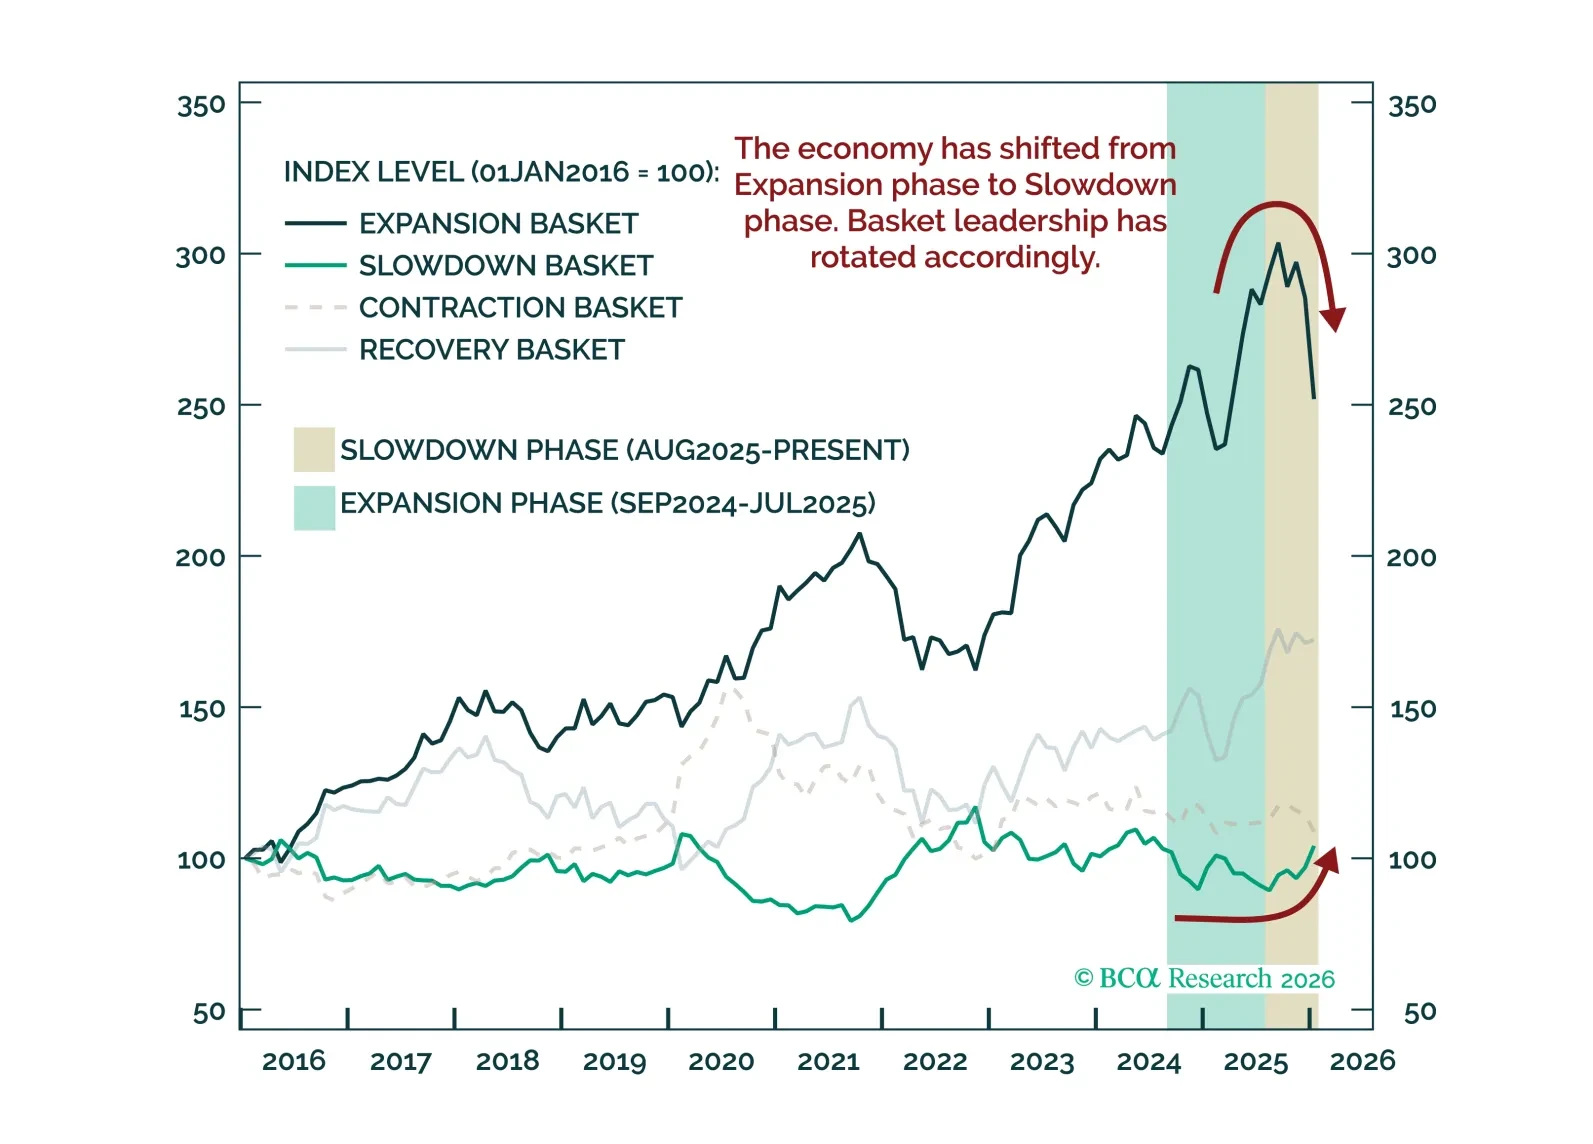
The US economy is in the Slowdown phase of the business cycle, according to our measure of aggregate US economic activity; growth remains positive but acceleration is negative. Historically, this phase more often resolves in reacceleration than recession. Recent market price action, from the index, to sectors, to relative industry performance, broadly reflects typical Slowdown phase dynamics.