Latest from BCA Research
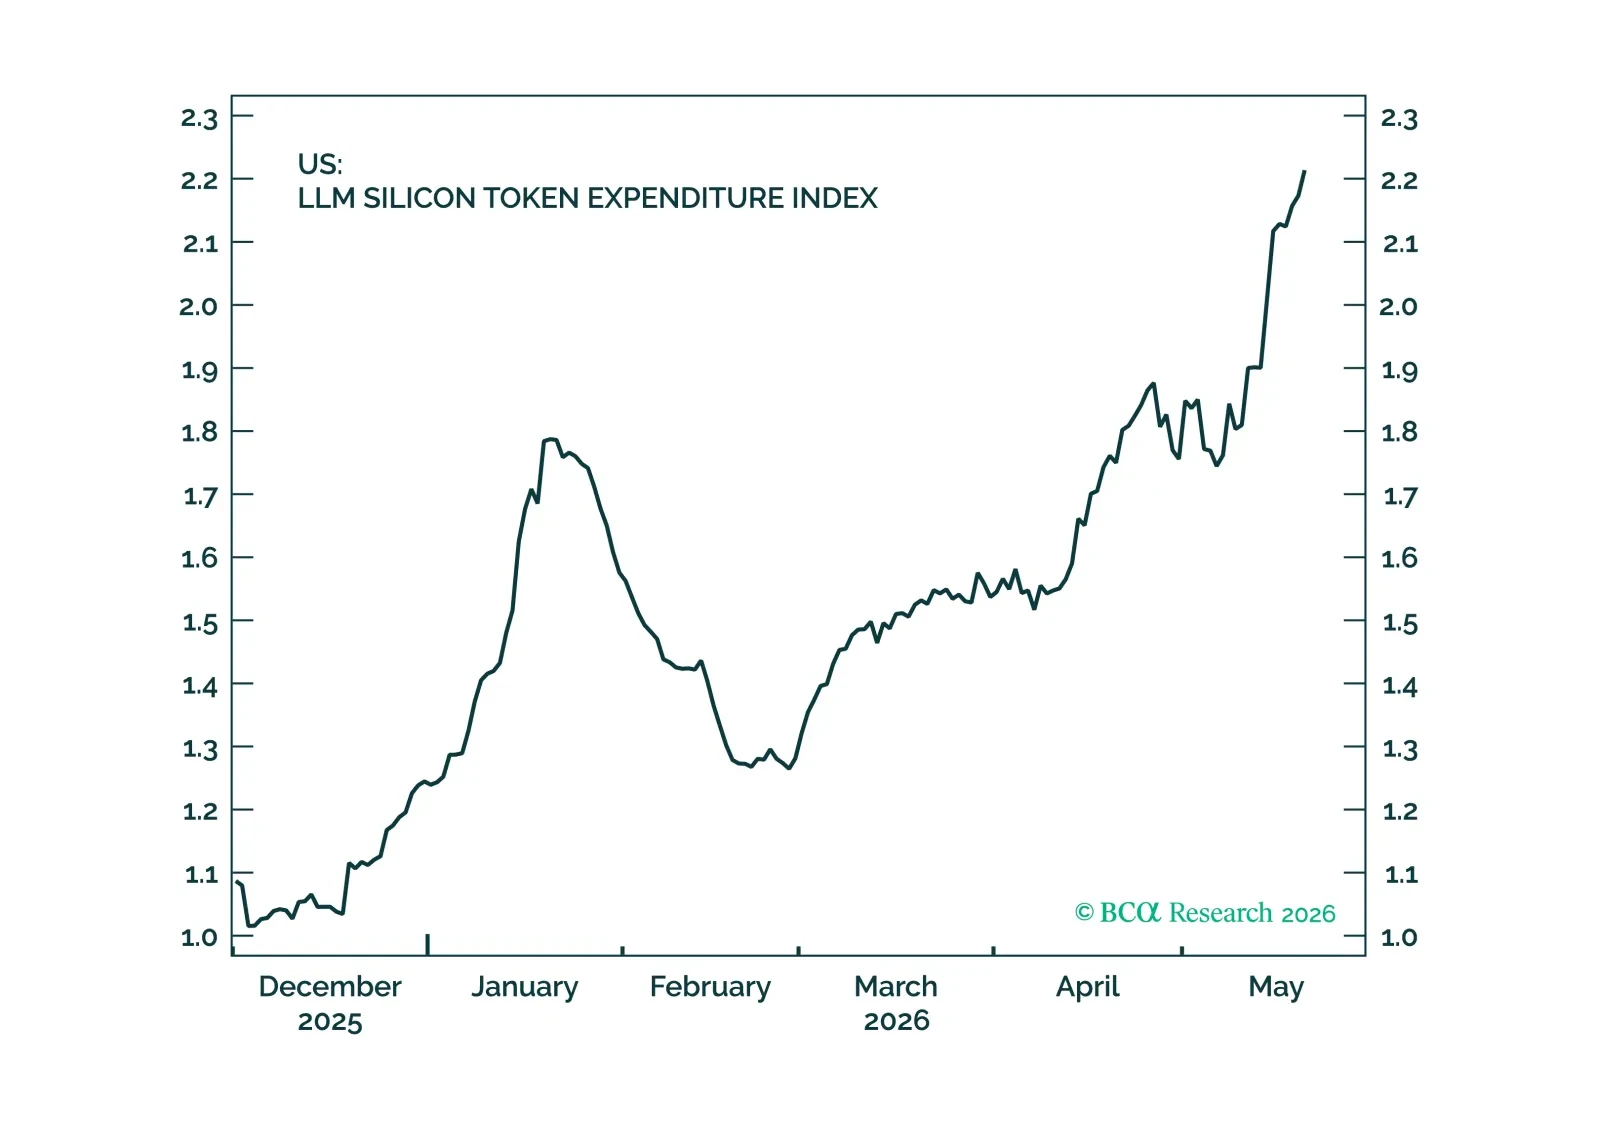
So far most of the value in the AI supply chain has been captured by hardware companies. However, as model providers shift to usage-based pricing, value will begin to accrue to models and applications. Communications Services and Software should benefit from this shift. This broadening of the AI story, along with solid economic momentum should keep the rally going for the rest of the year. Remain overweight equities. Downgrade Energy to Neutral. Buy Software.
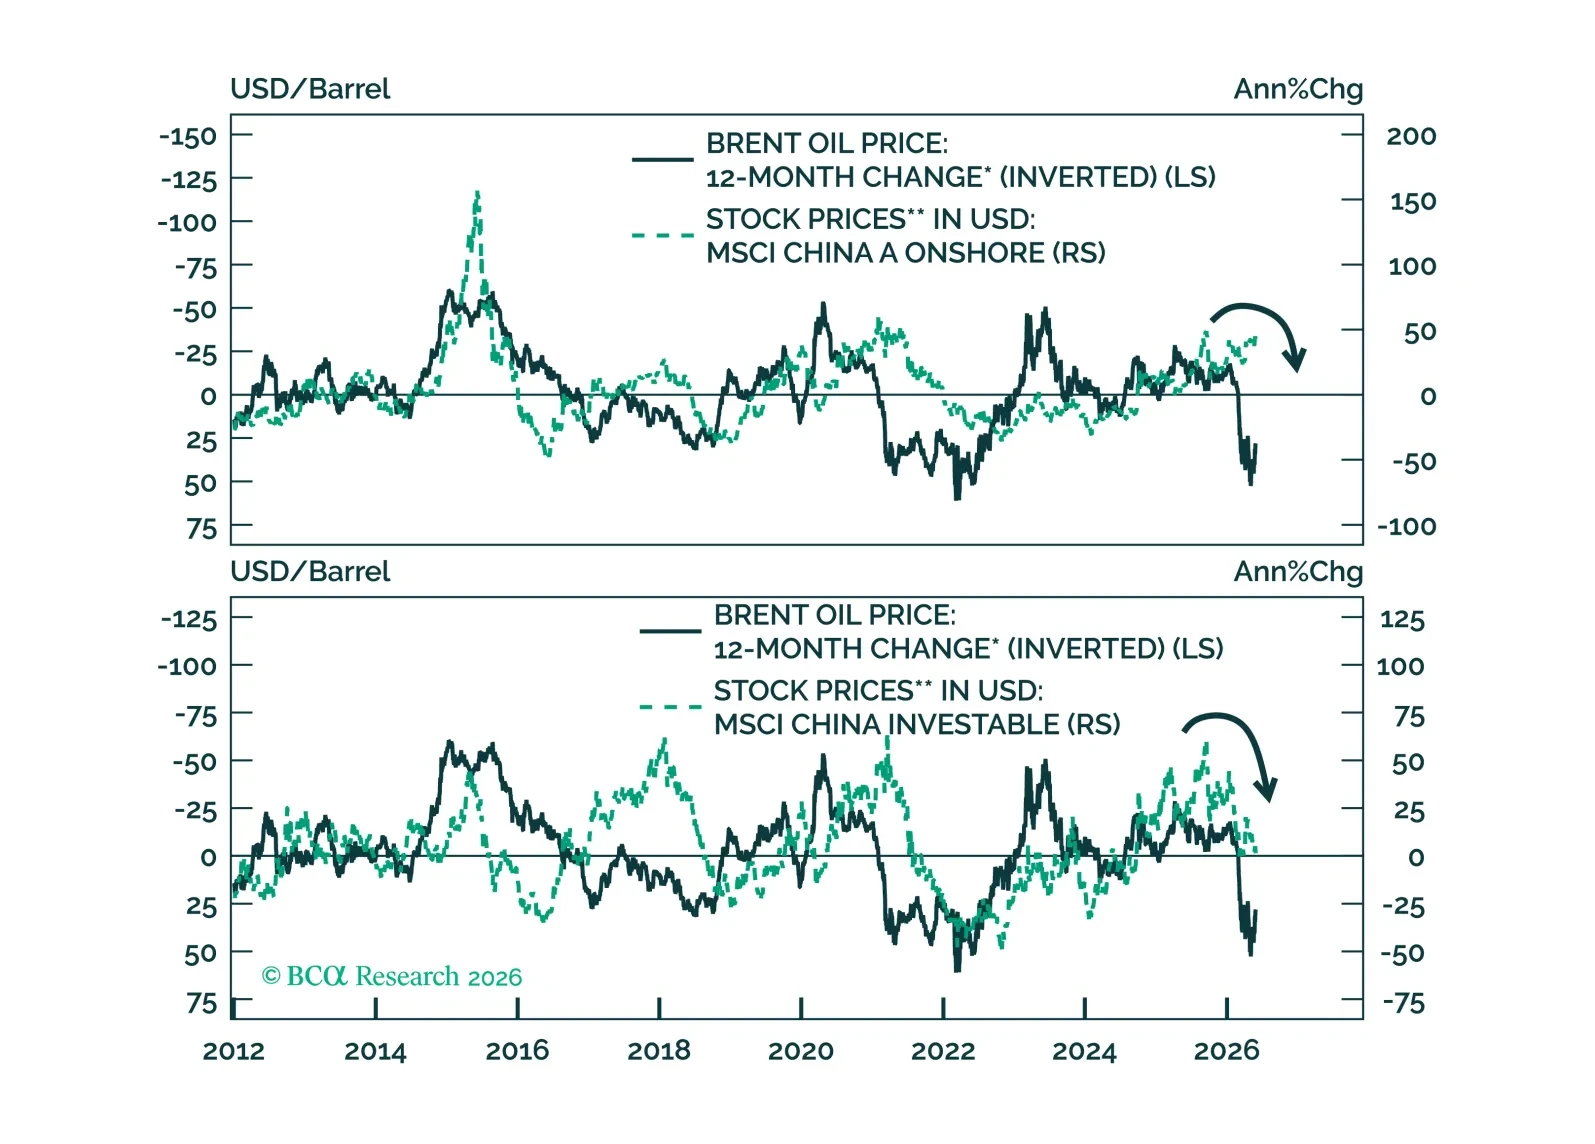
Oil shocks hit economies with a lag. China will feel the delayed pain of surging oil prices, pushing Beijing toward infrastructure spending as its main tool to prop up growth.
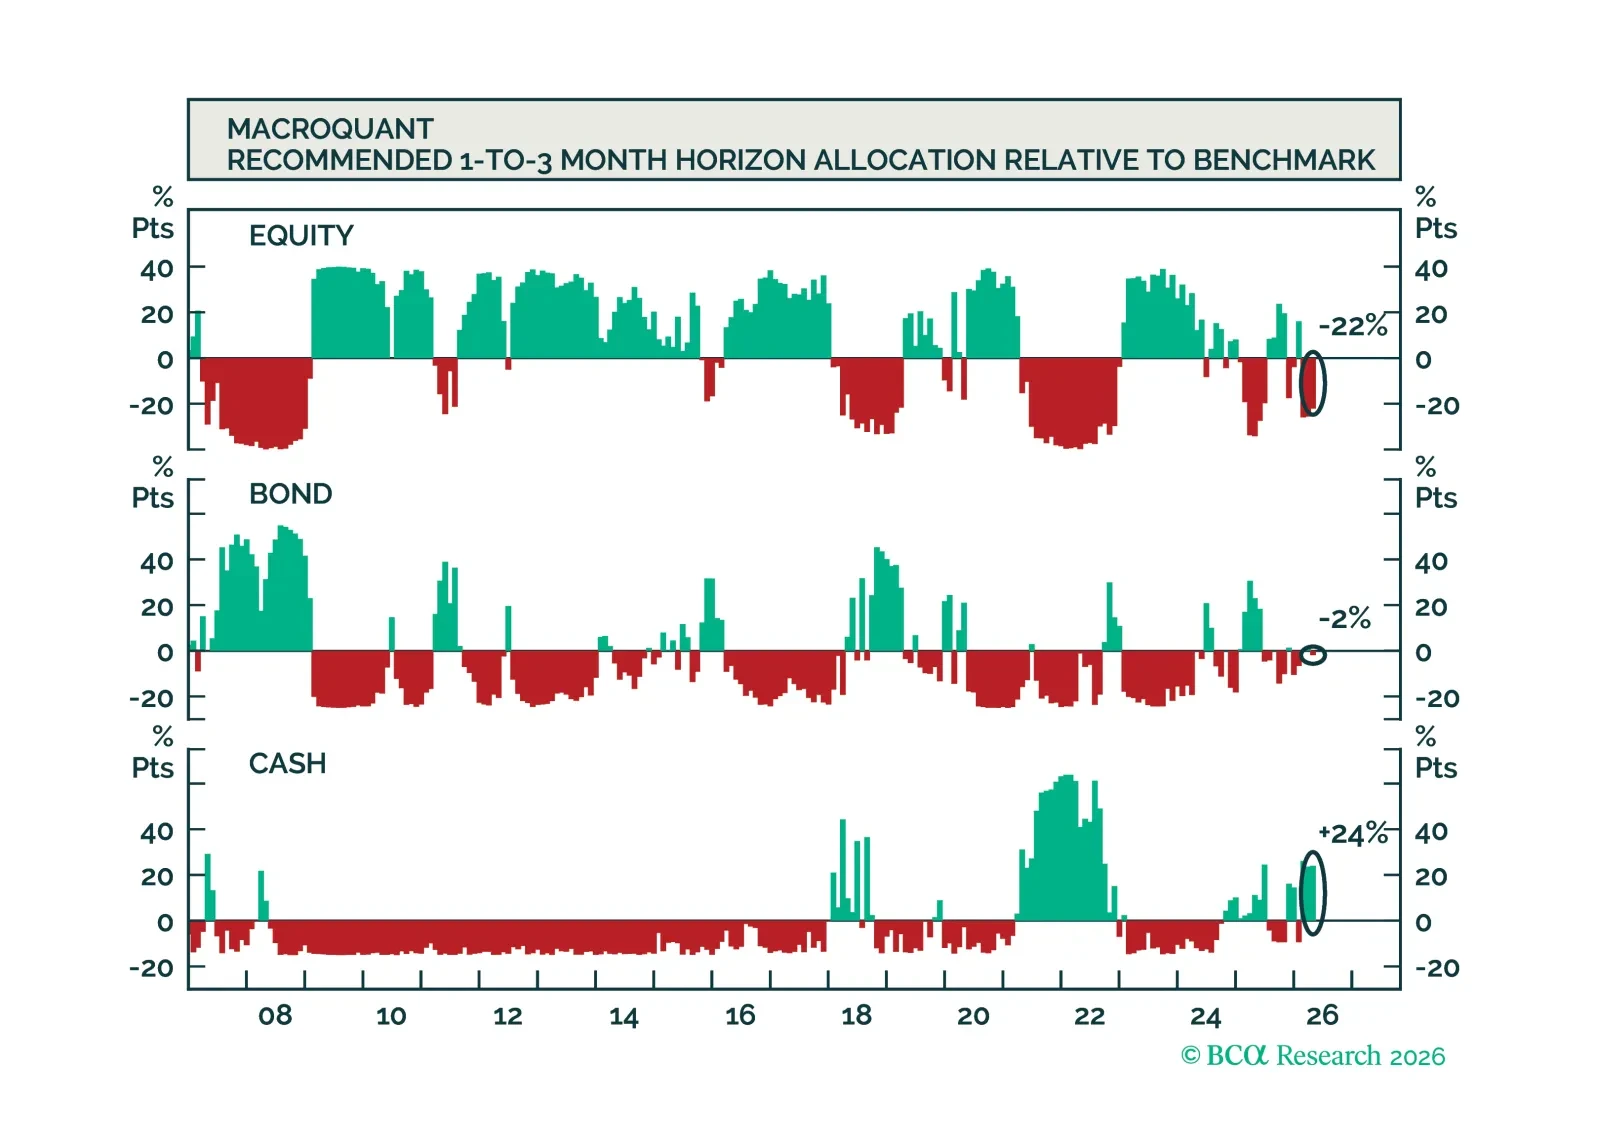
MacroQuant recommends a slight underweight position in equities, favors a below-benchmark duration stance in fixed-income portfolios, is very positive on the US dollar, downgrades gold to underweight, upgrades copper to overweight, and remains very bullish on oil.
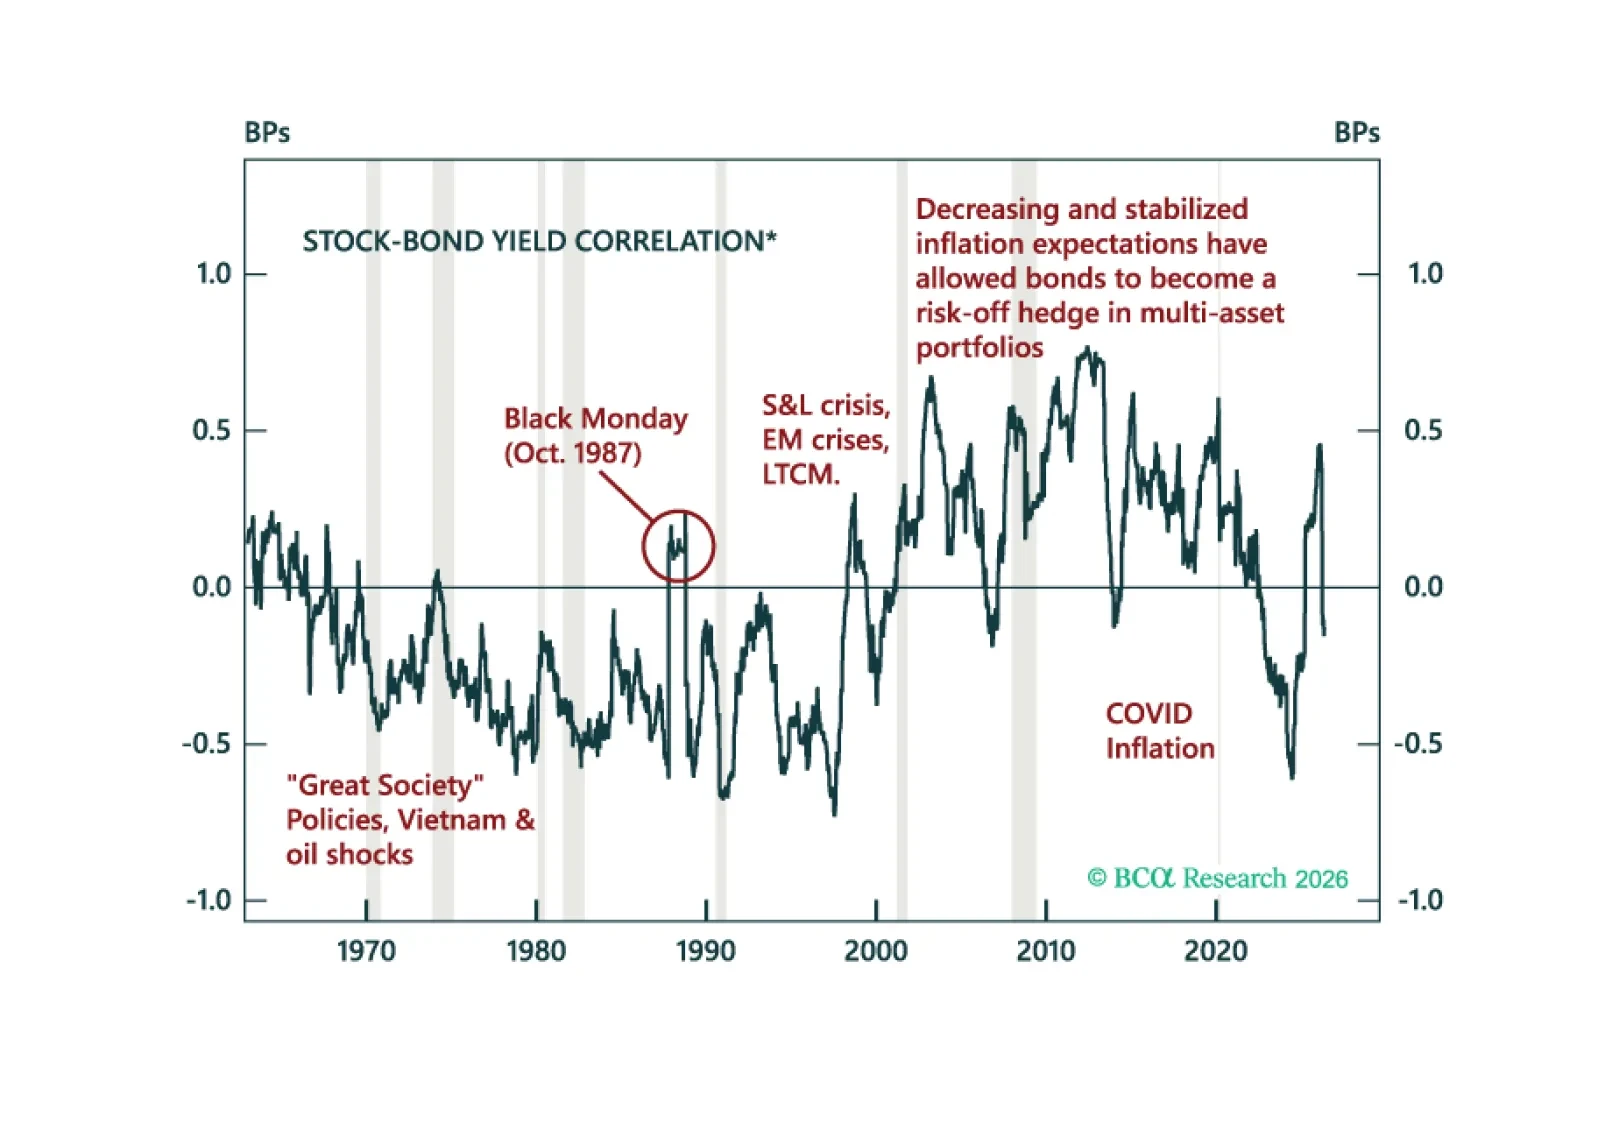
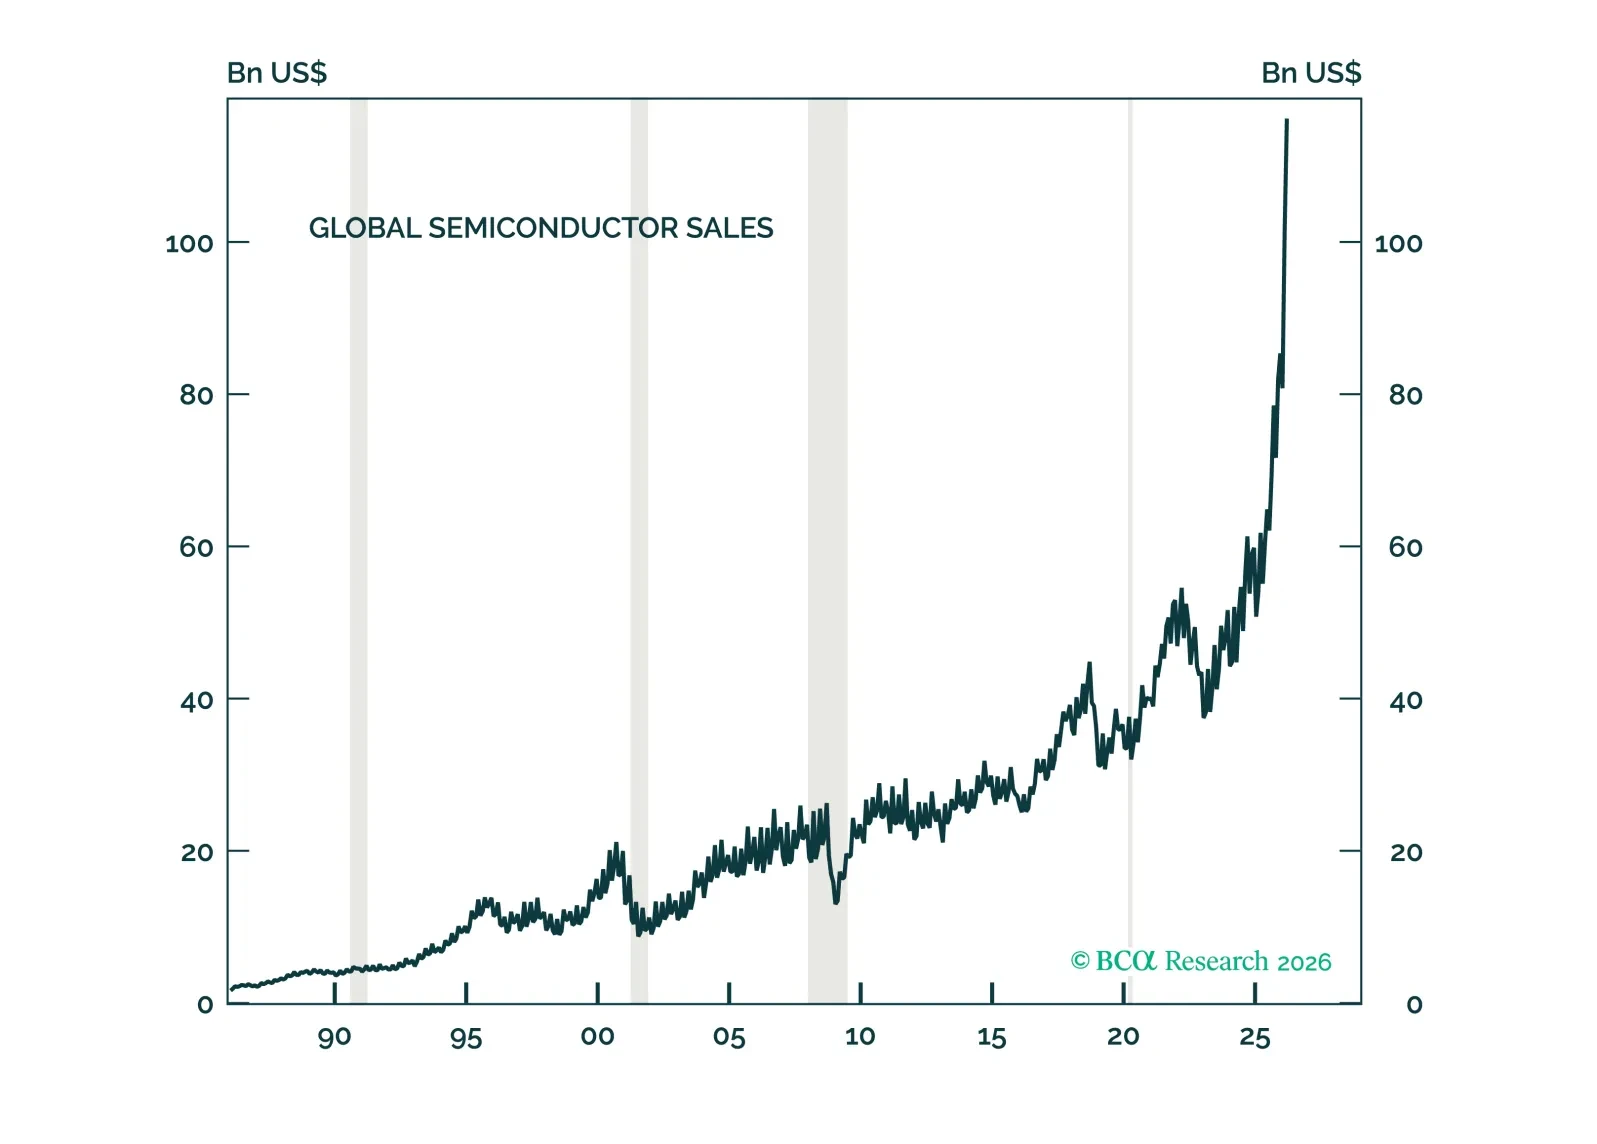
The AI bubble is a different type of bubble. It is primarily an earnings bubble rather than a valuation bubble. Like all bubbles, the AI bubble will burst. For now, however, our AI demand indicators do not suggest that this is imminent.
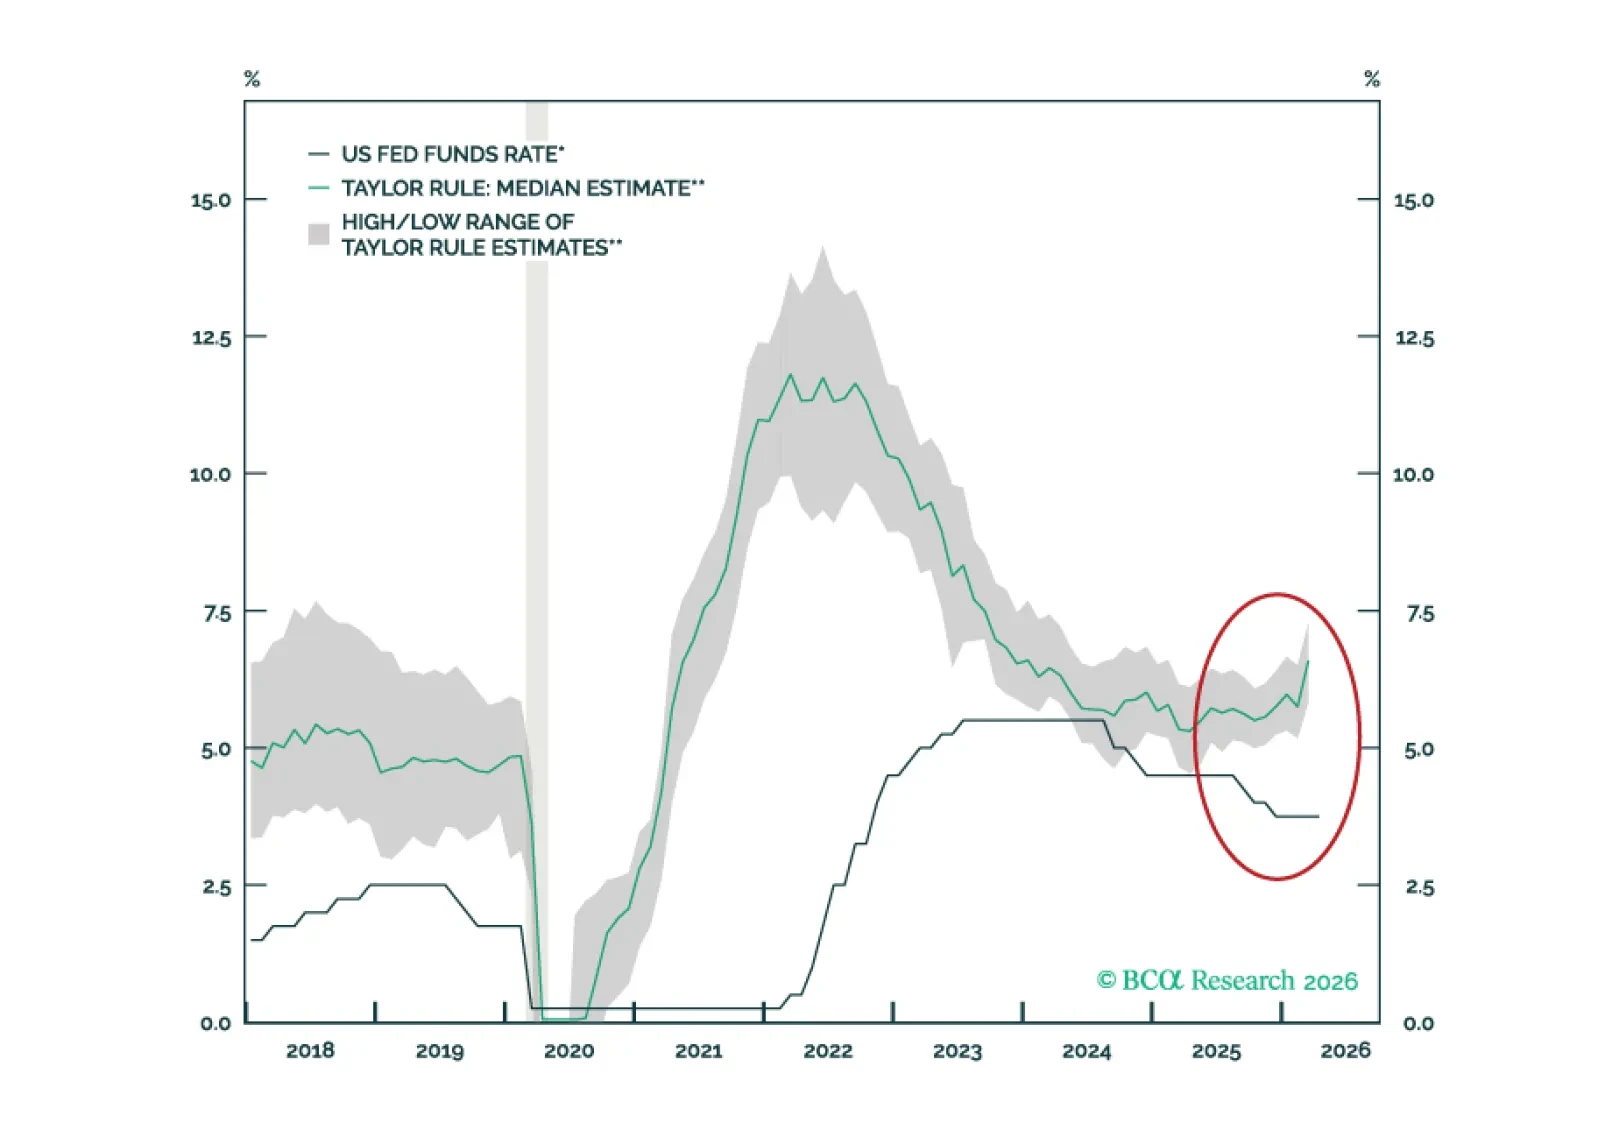
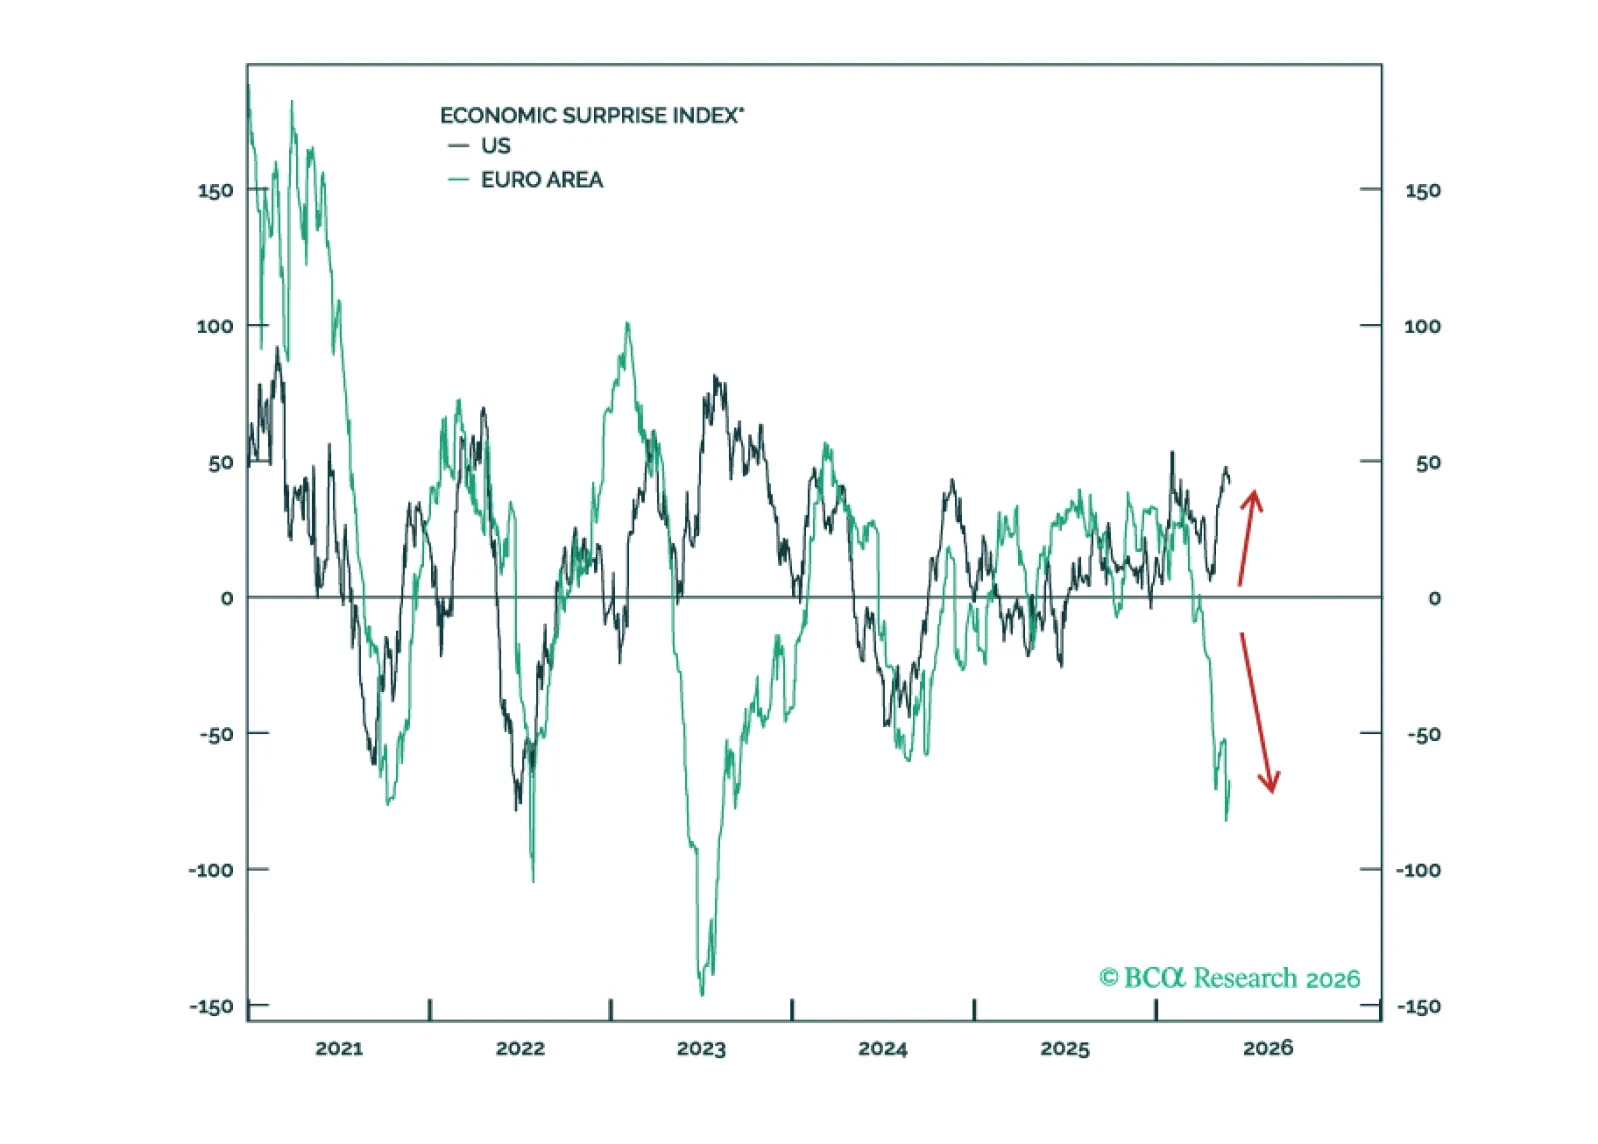
In Section I, Doug revisits the situation in the Strait of Hormuz and its implications for growth in Europe and the US. In Section II, Jonathan explores whether Kevin Warsh's appointment as Fed Chair signals a return to Greenspan-era, rules-based monetary policy.
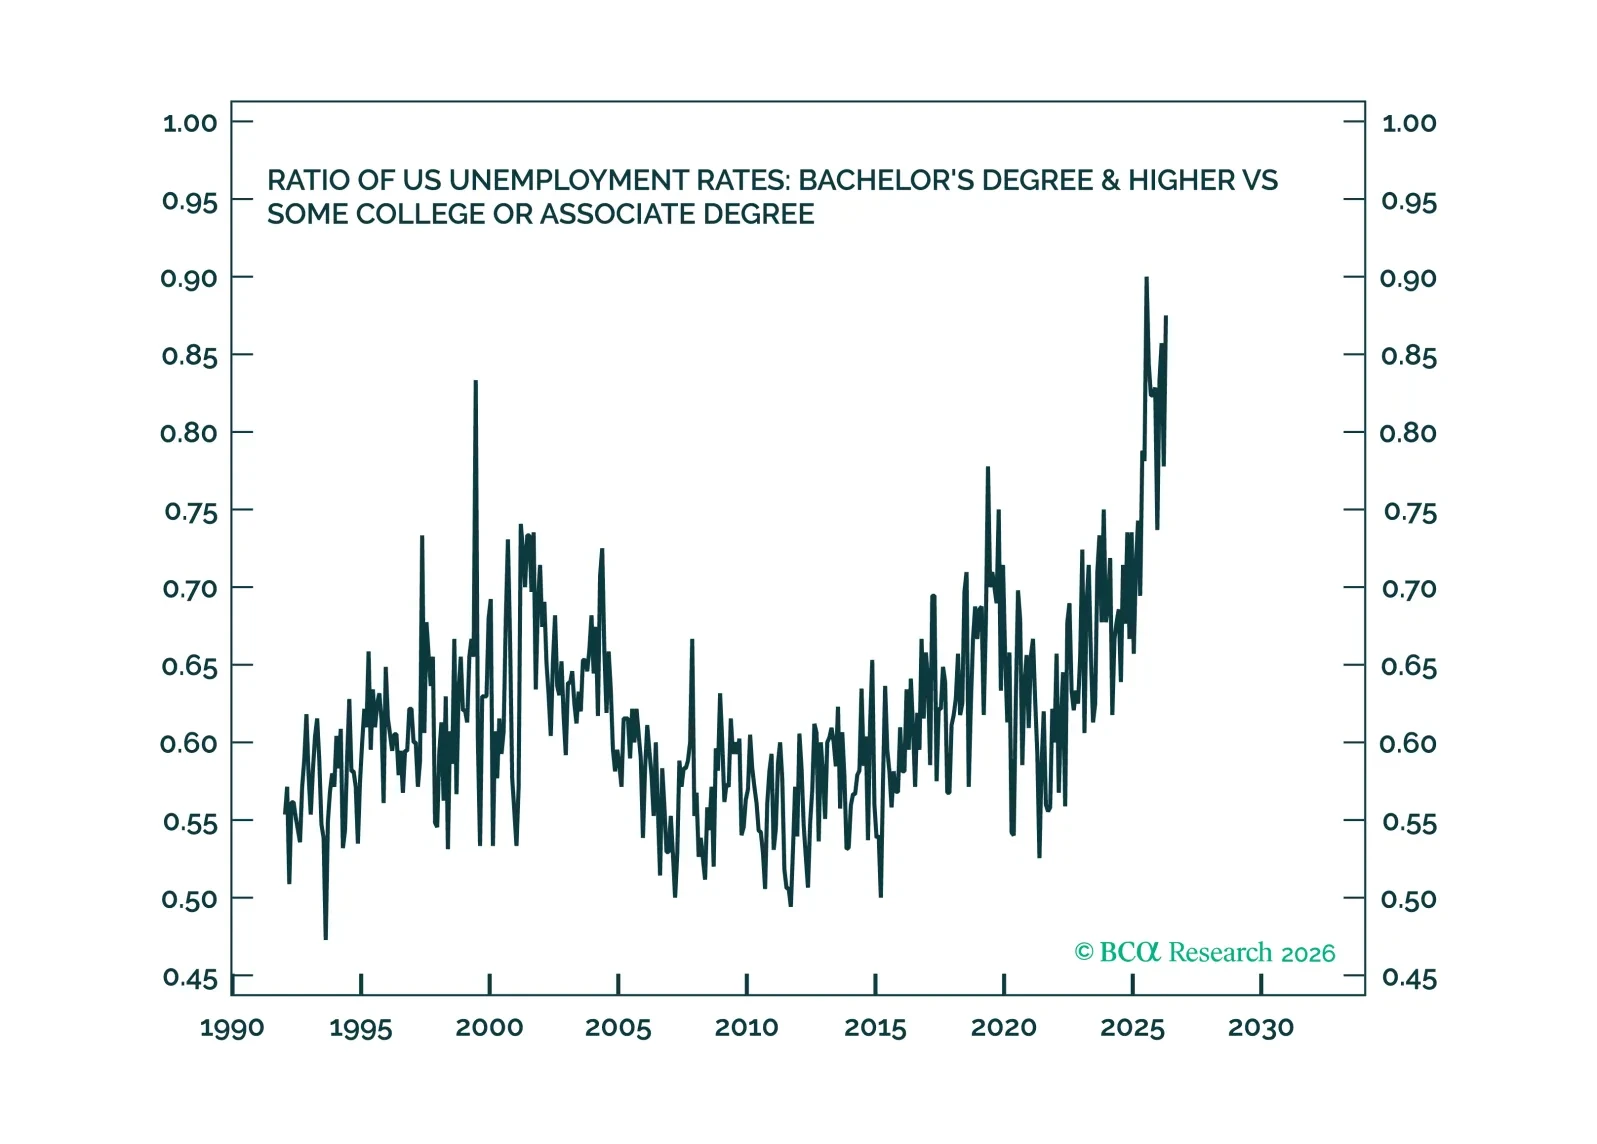
AI excels at IQ but fails miserably at EQ. Hence, AI will obsolete any job that relies on IQ, including many graduate-level jobs. But high-EQ humans will be in high demand to pair up with AI, and many of these jobs will be middle income jobs. We discuss the implication for the economy and markets. Plus, a new tactical trade is underweight global tech versus healthcare.
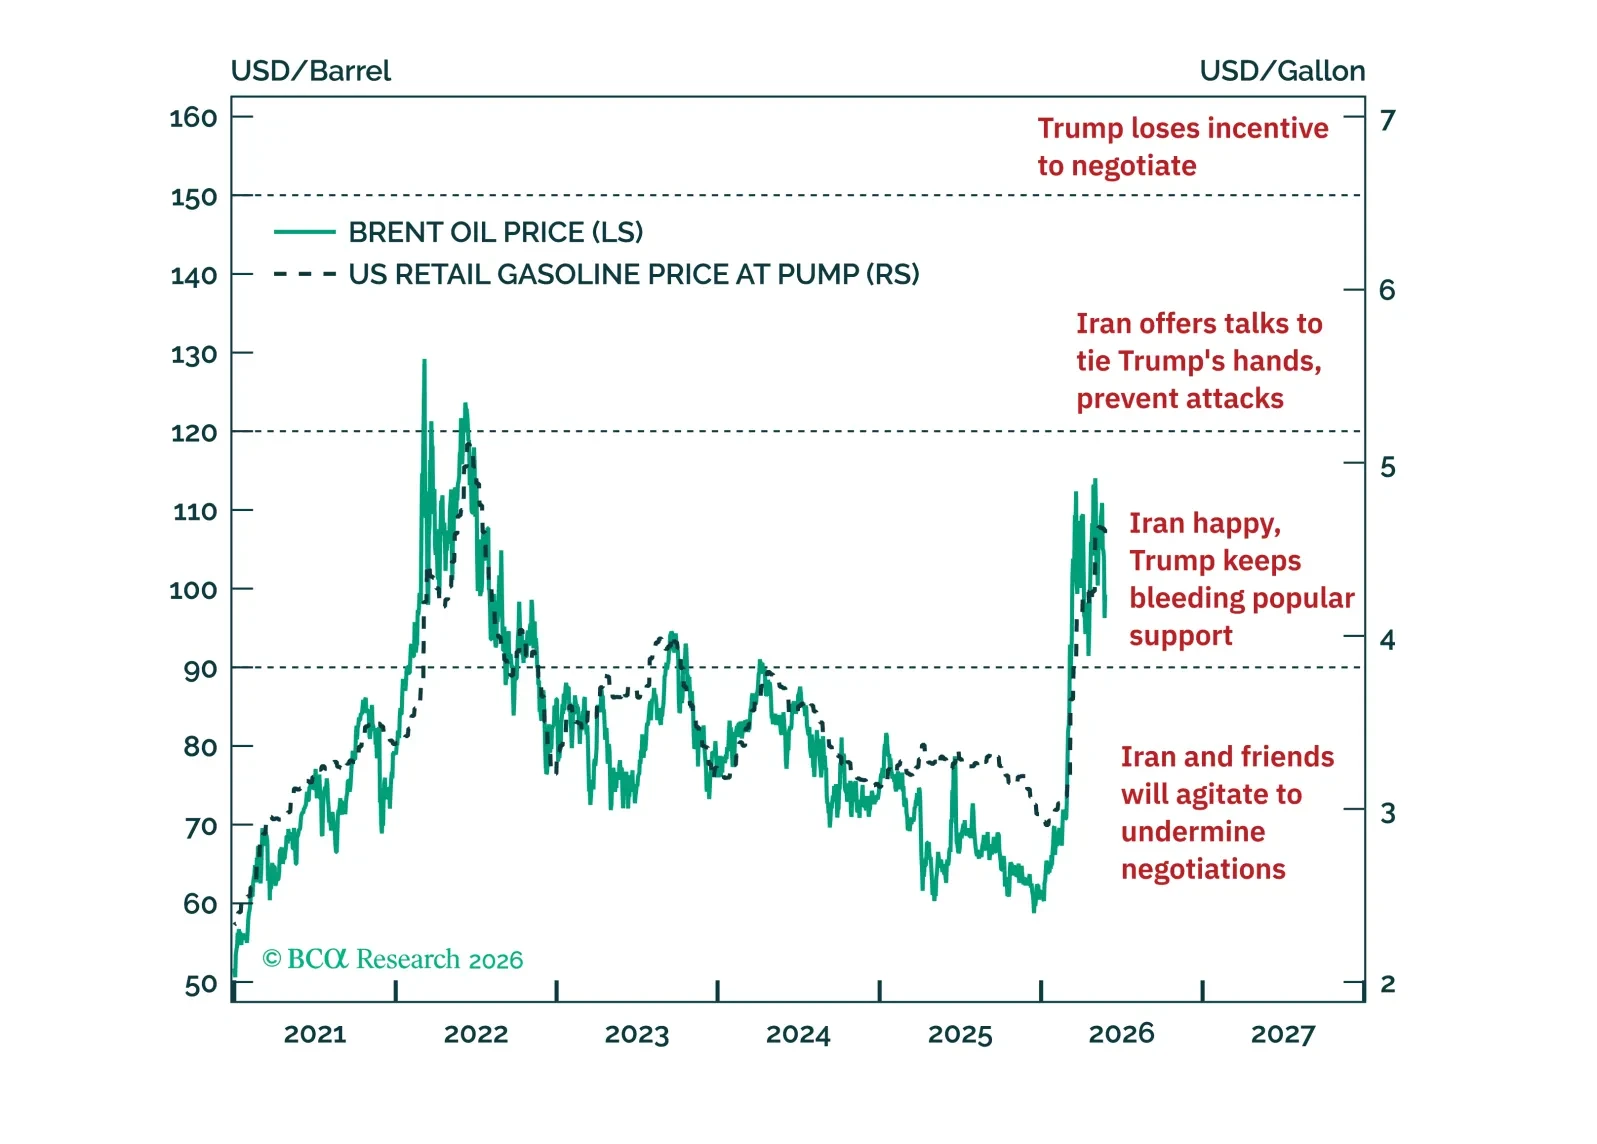
The odds of a near-term US-Iran deal have gone up slightly, but the odds of a Russian provocation that divides NATO have also gone up.
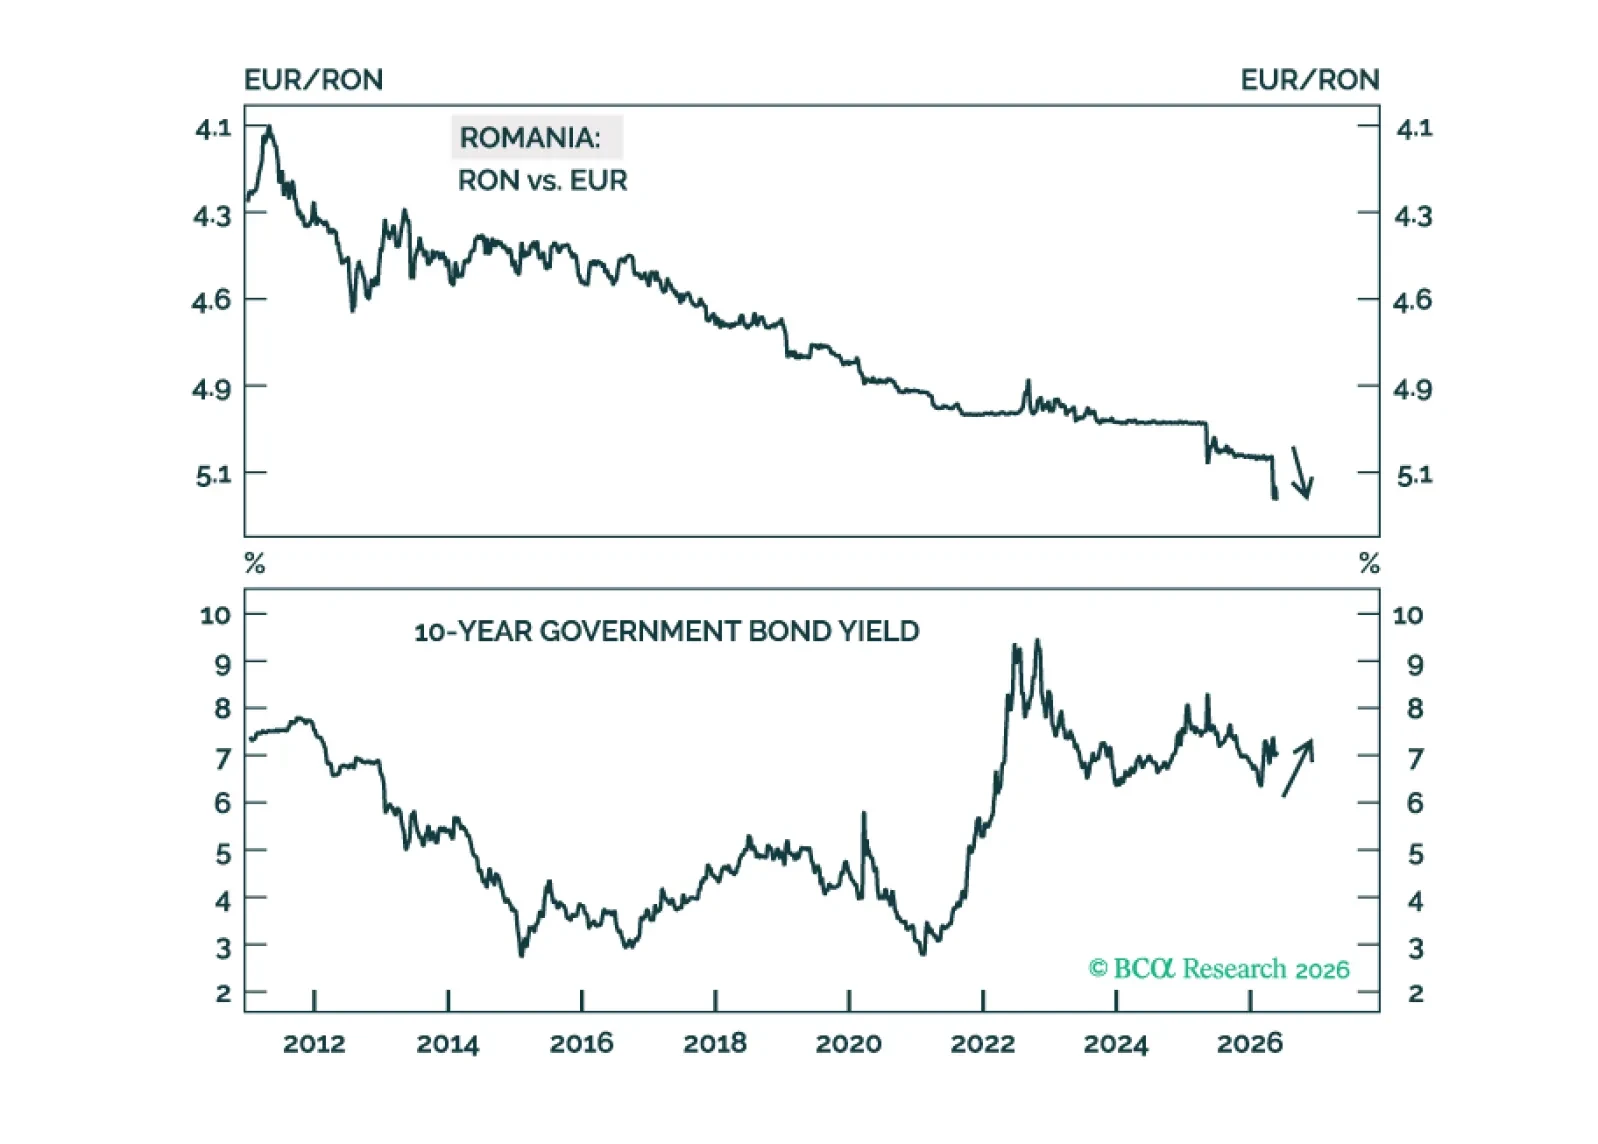
In Romania, large fiscal and current account deficits, high inflation, negative real rates, an overvalued exchange rate, and deteriorating growth point to budding currency devaluation. Investors should short the Romanian currency versus the euro and underweight Romanian local bonds, equities, and sovereign credit.