Equities
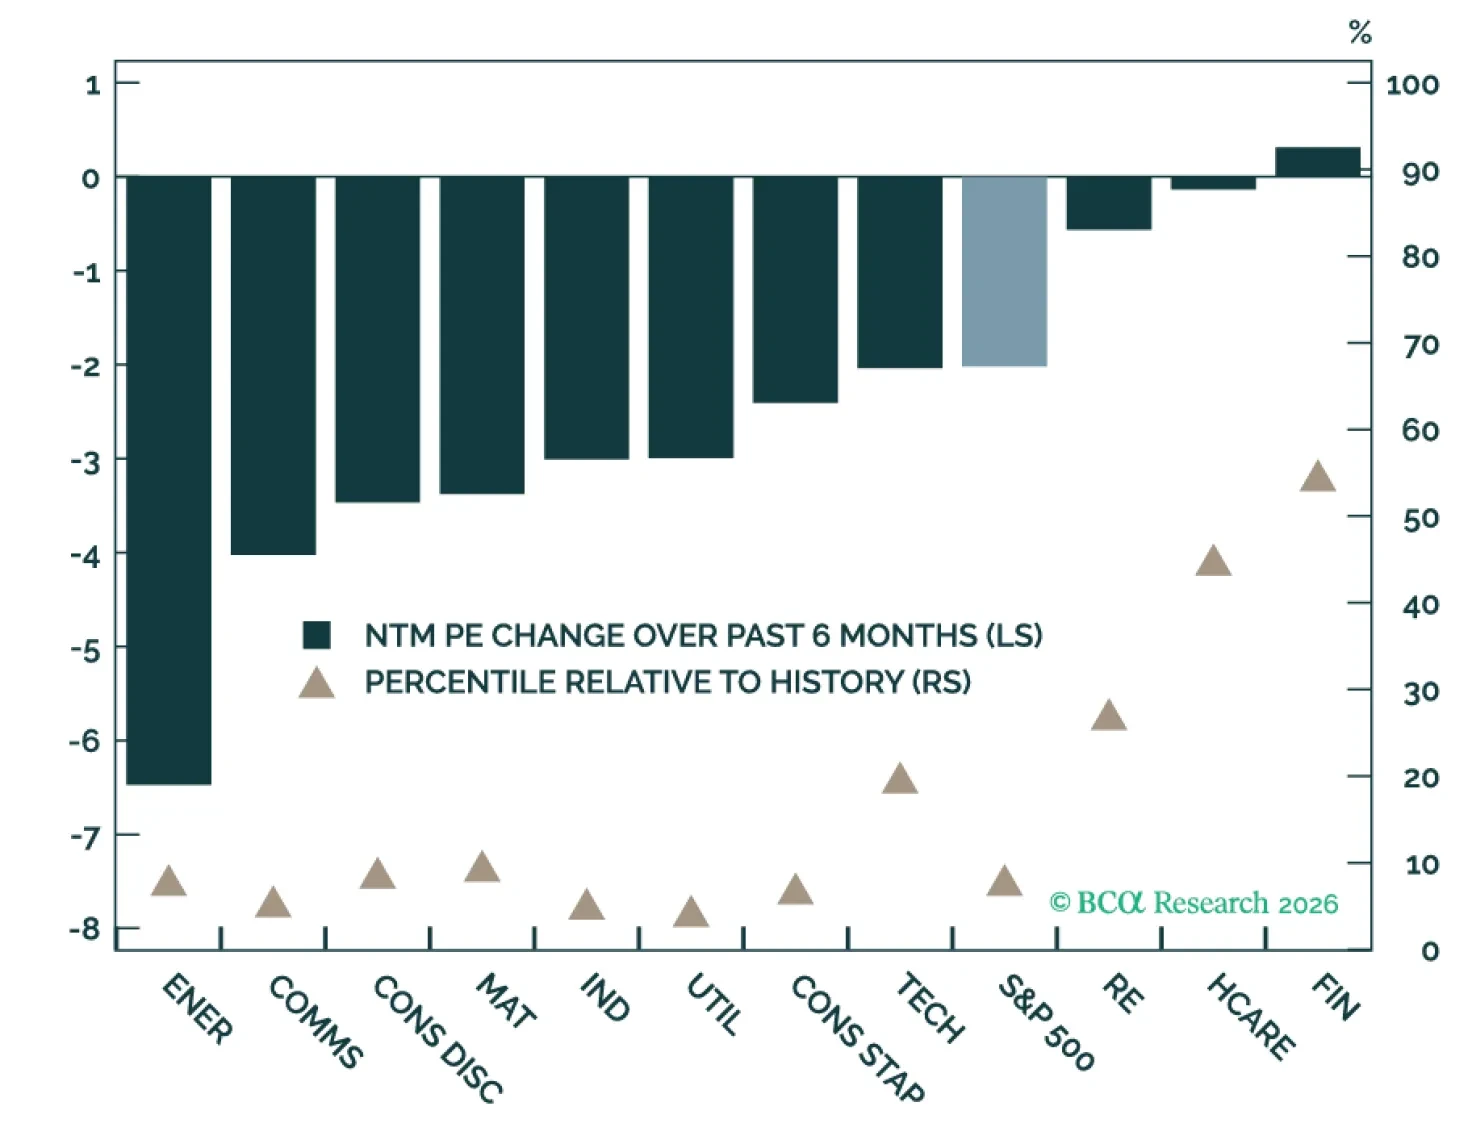
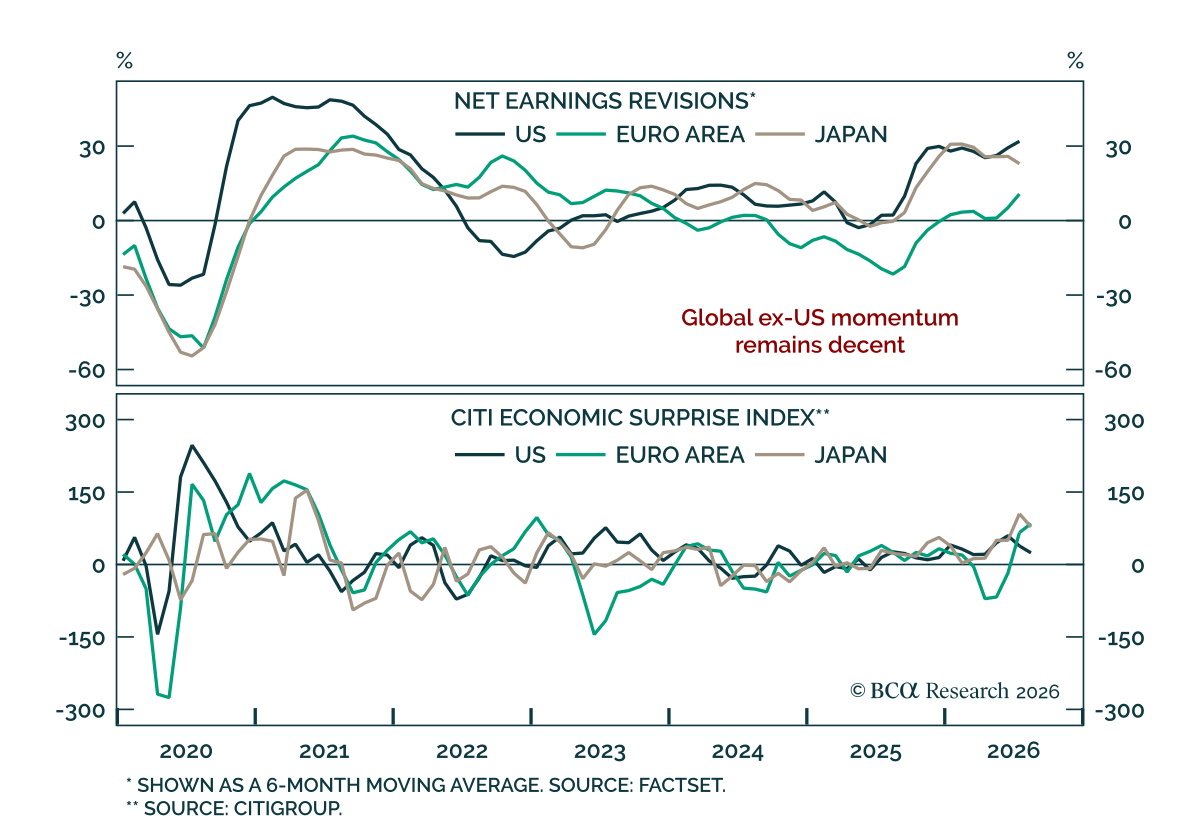
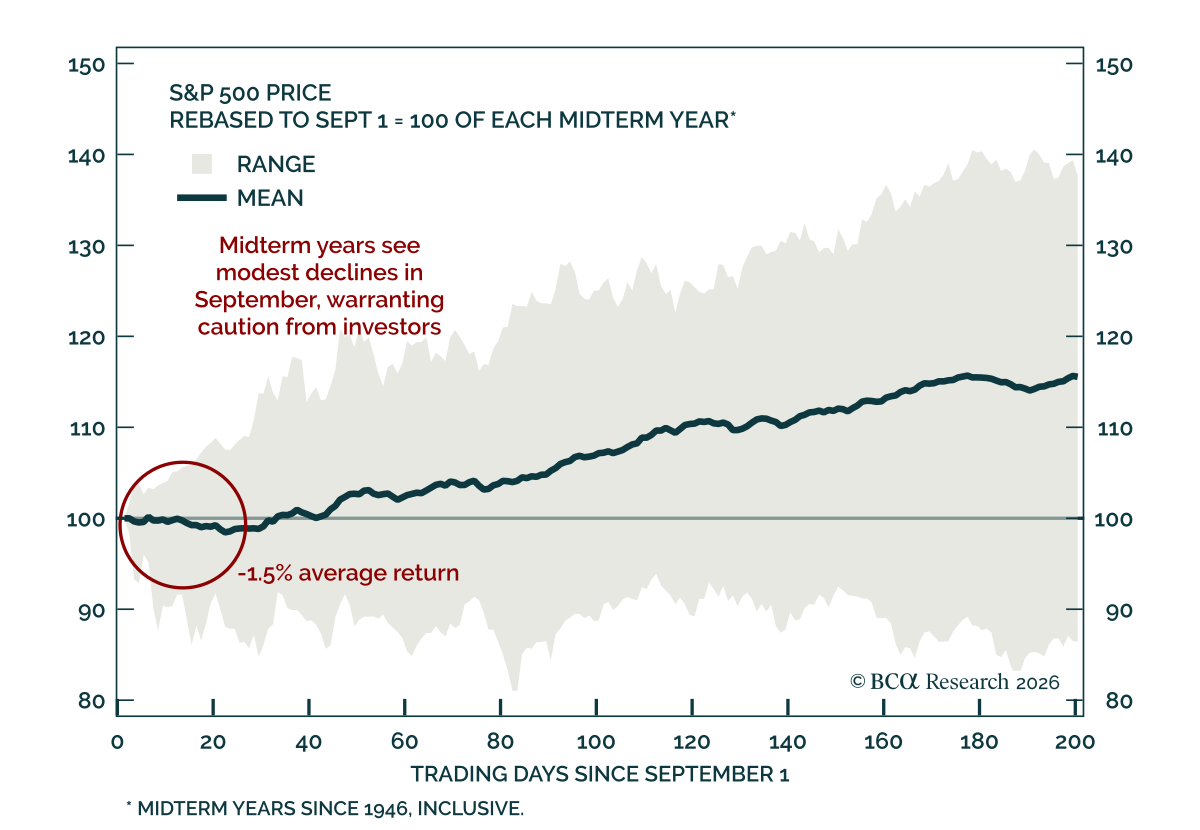
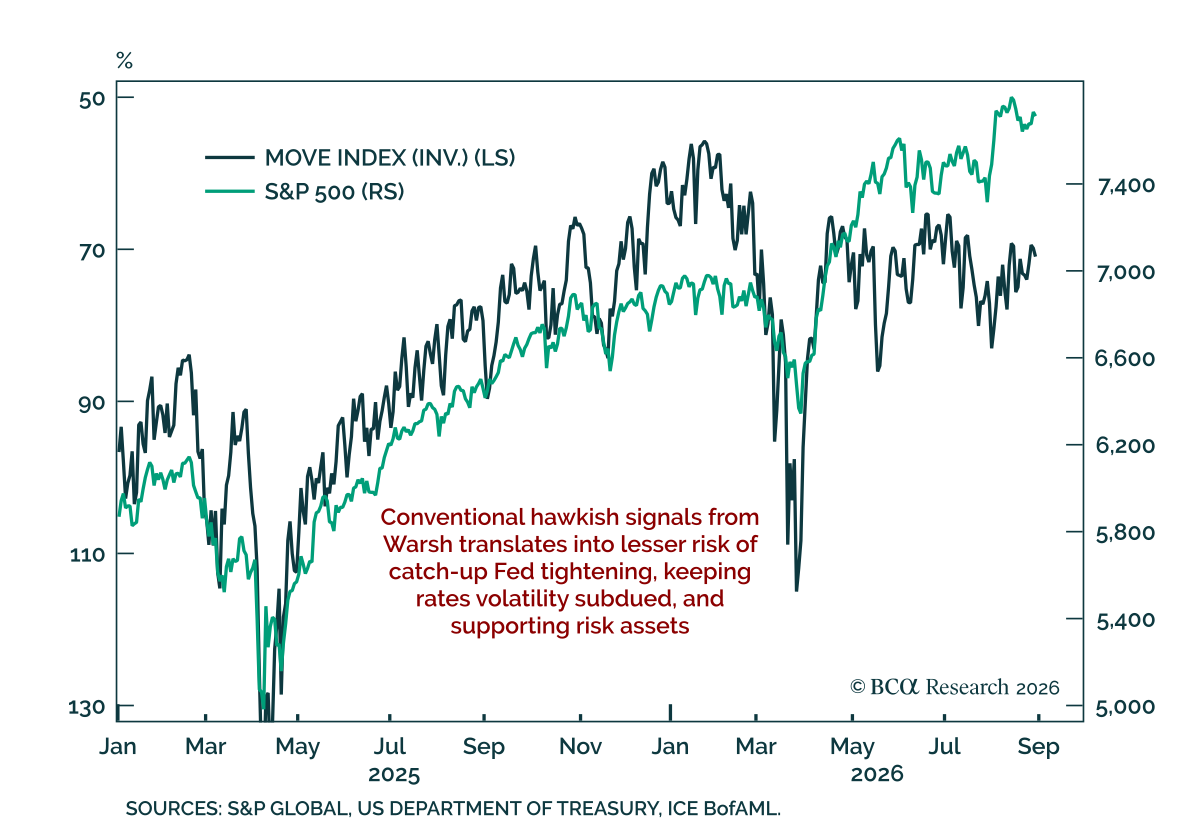
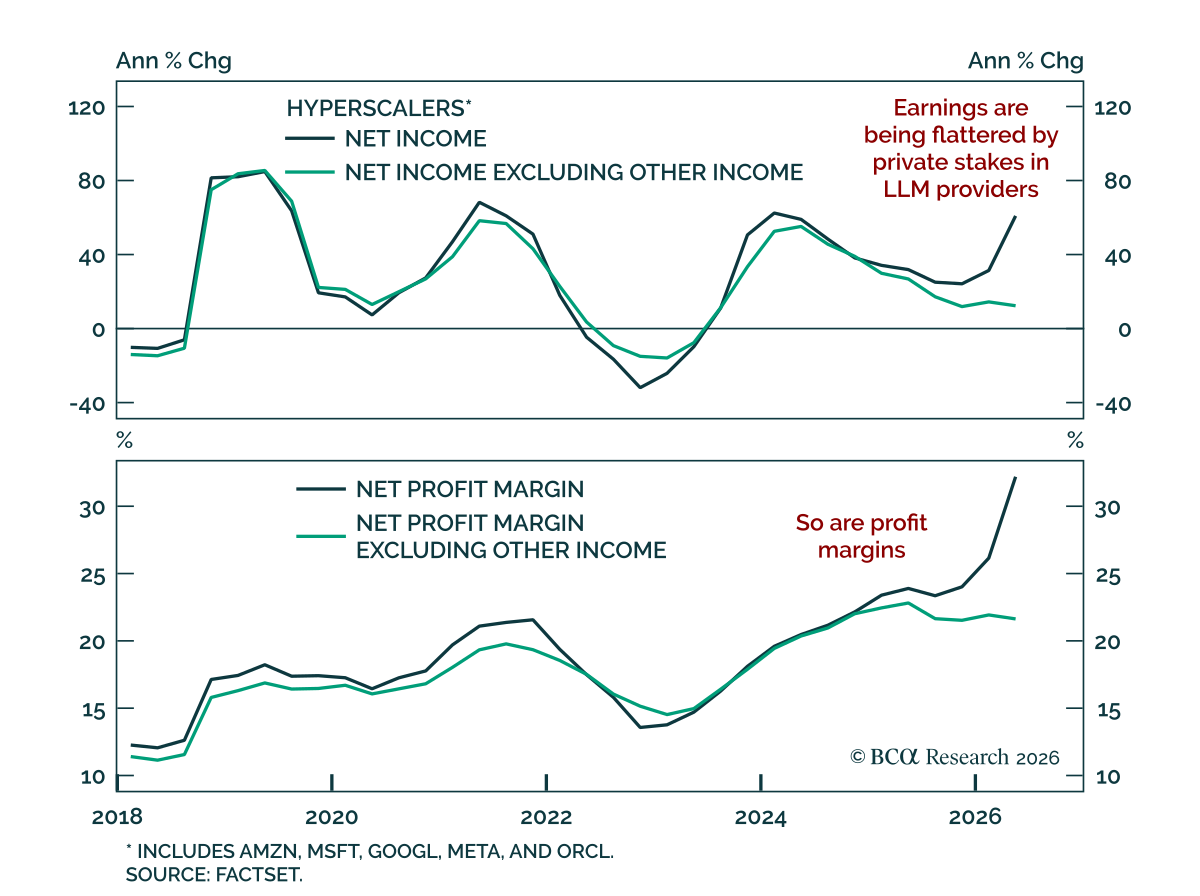
We remain constructive on US equities, but higher yields, slower EPS growth and heavy IPO issuance remain significant risks to valuations, leaving the path to our year-end target increasingly dependent on earnings. Tactically, there has already been a significant, but benign, compression in multiples, as earnings have outpaced prices. A well-communicated Fed hike could ease rather than intensify bond-market uncertainty.
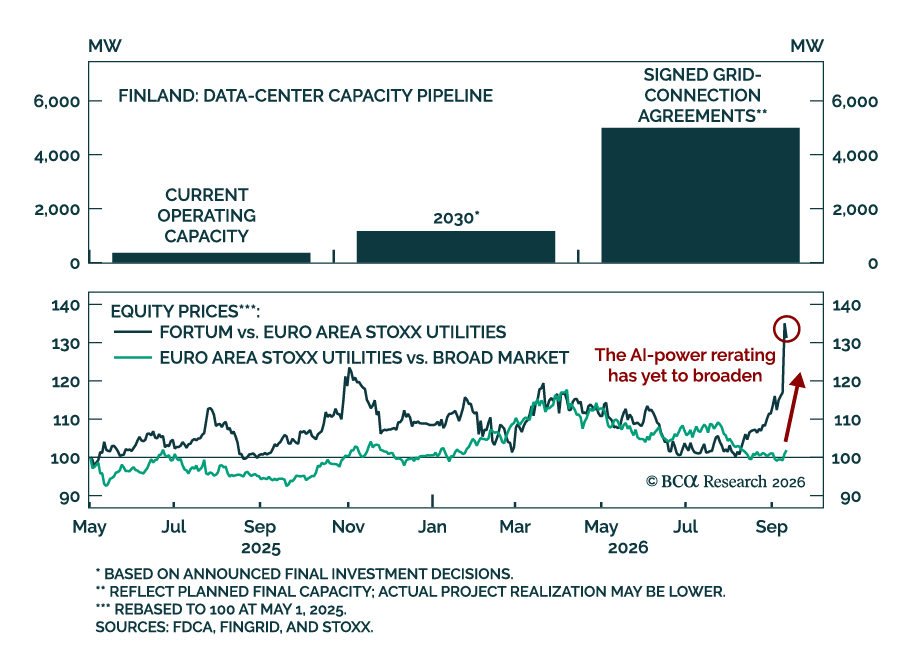
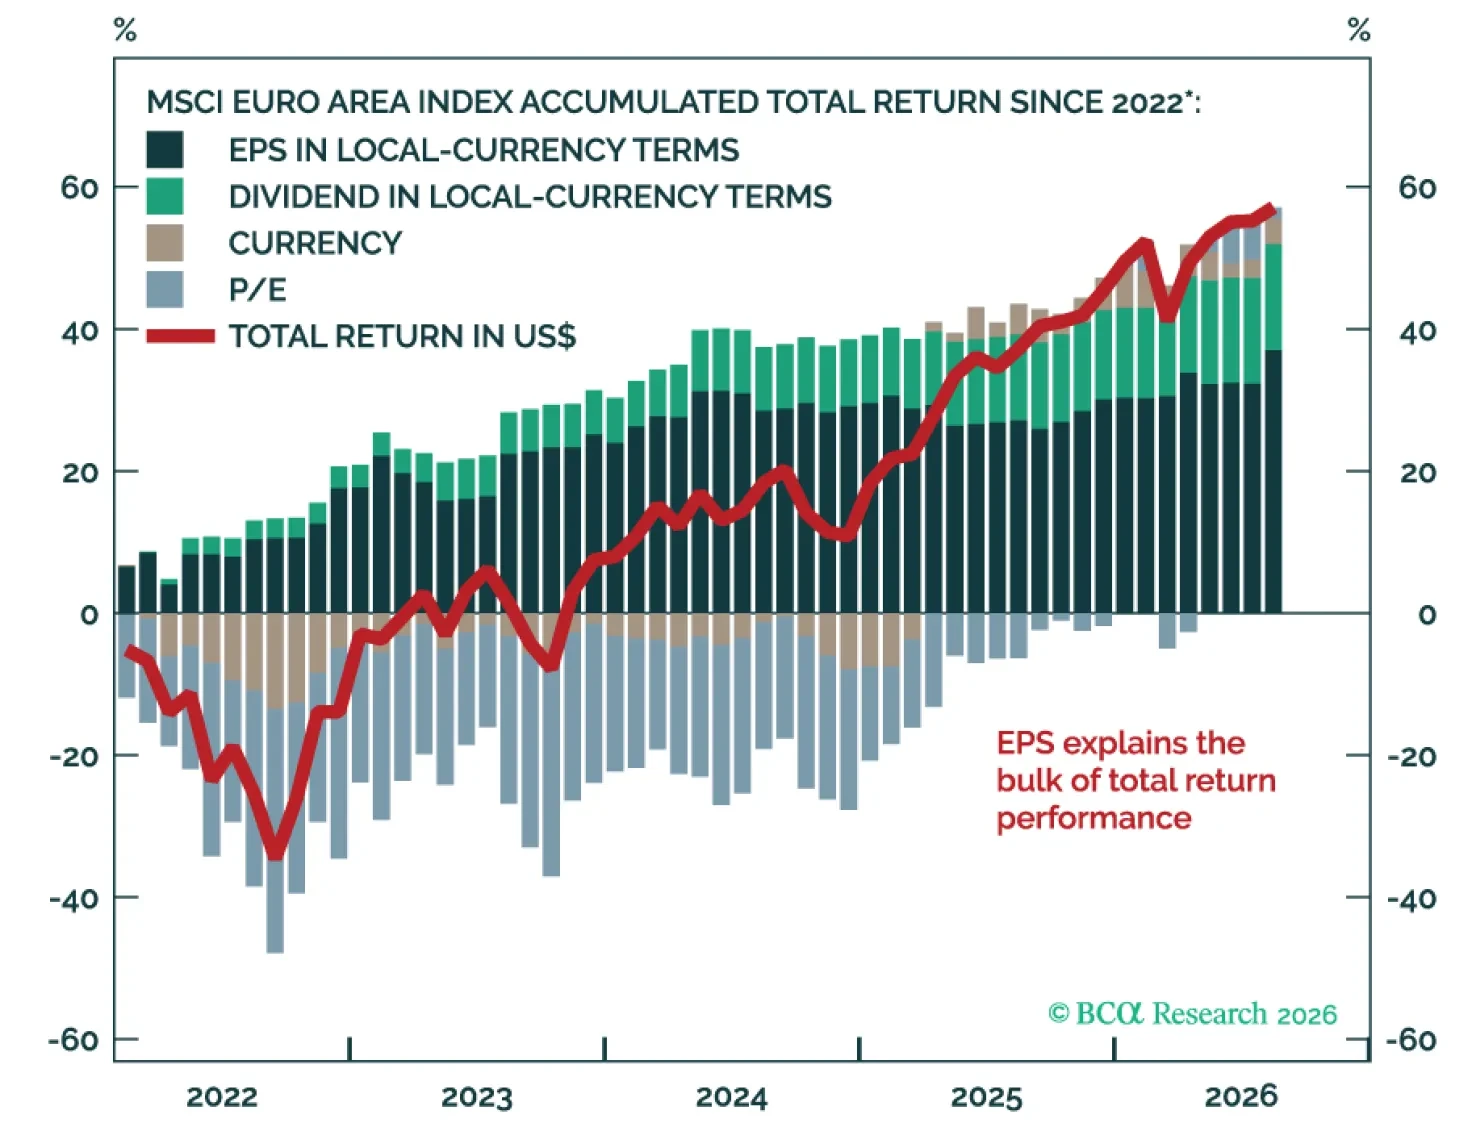
Europe’s earnings recovery is increasingly difficult to dismiss. Margins, ROE, ROIC, and capital efficiency have all improved, while banks have re-emerged as an earnings engine. Cyclical conditions remain supportive, and the structural picture continues to improve: higher investment, improving productivity, and EU reforms could give the recovery staying power.
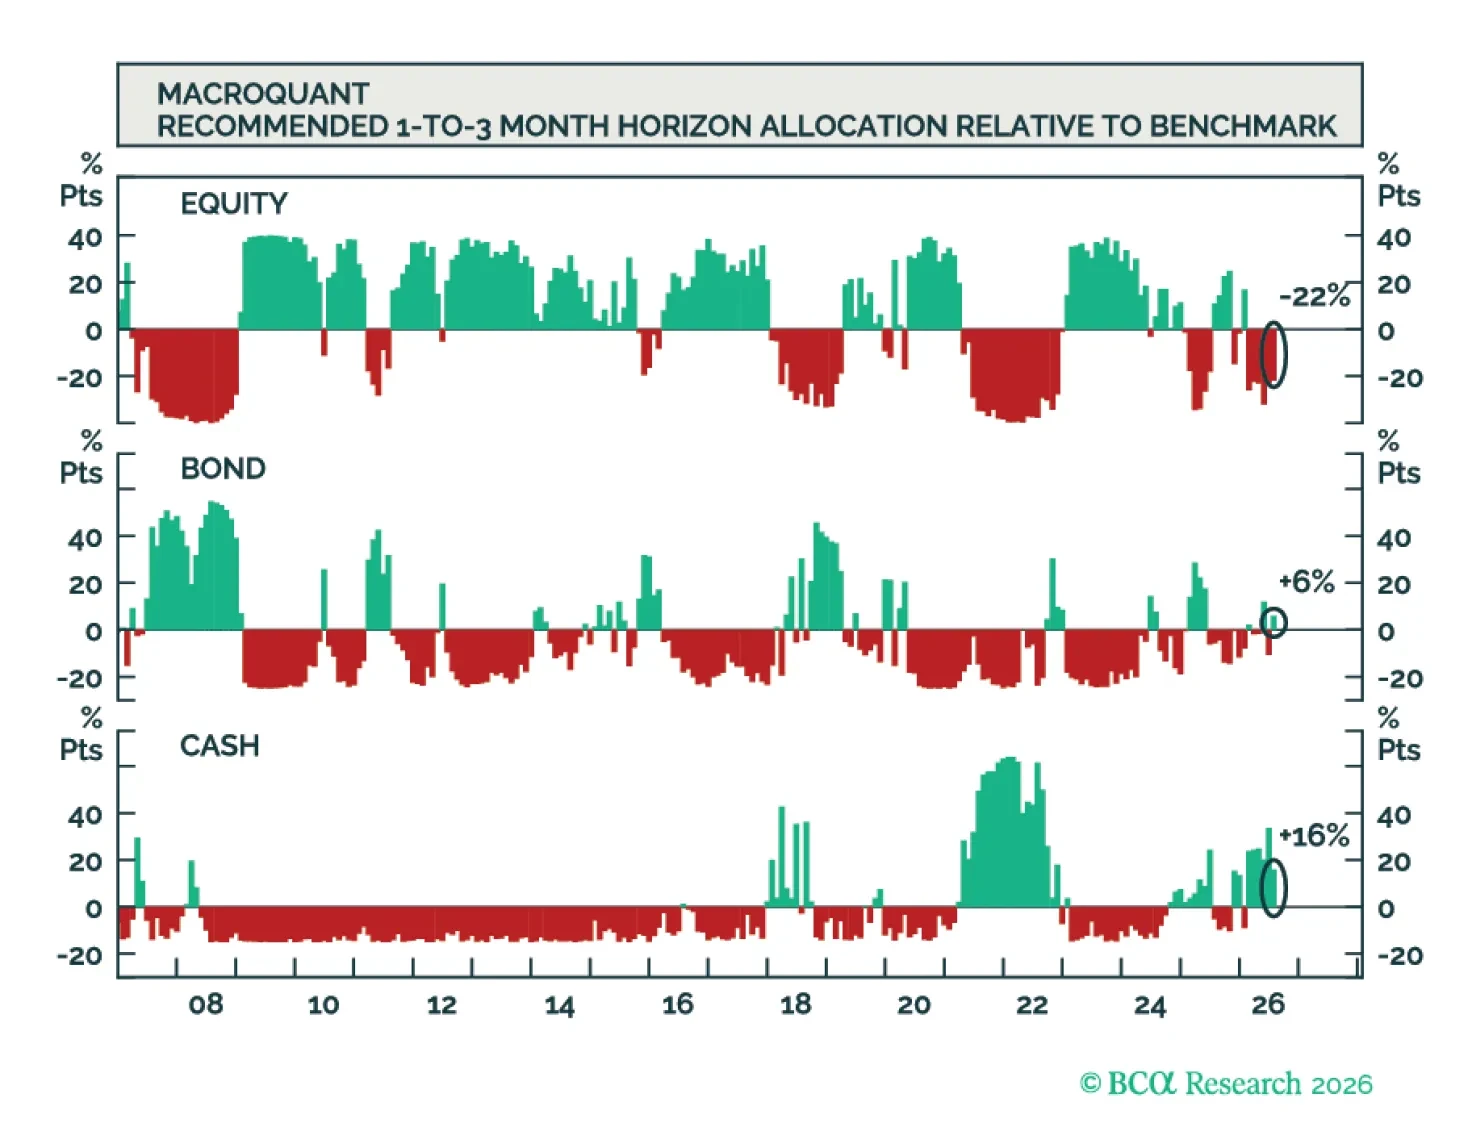
MacroQuant recommends a slight underweight position in equities, counterbalanced by a slight overweight to bonds, and a significant overweight to cash. The model is positive on the US dollar, modestly negative on gold, and bullish on copper and oil.
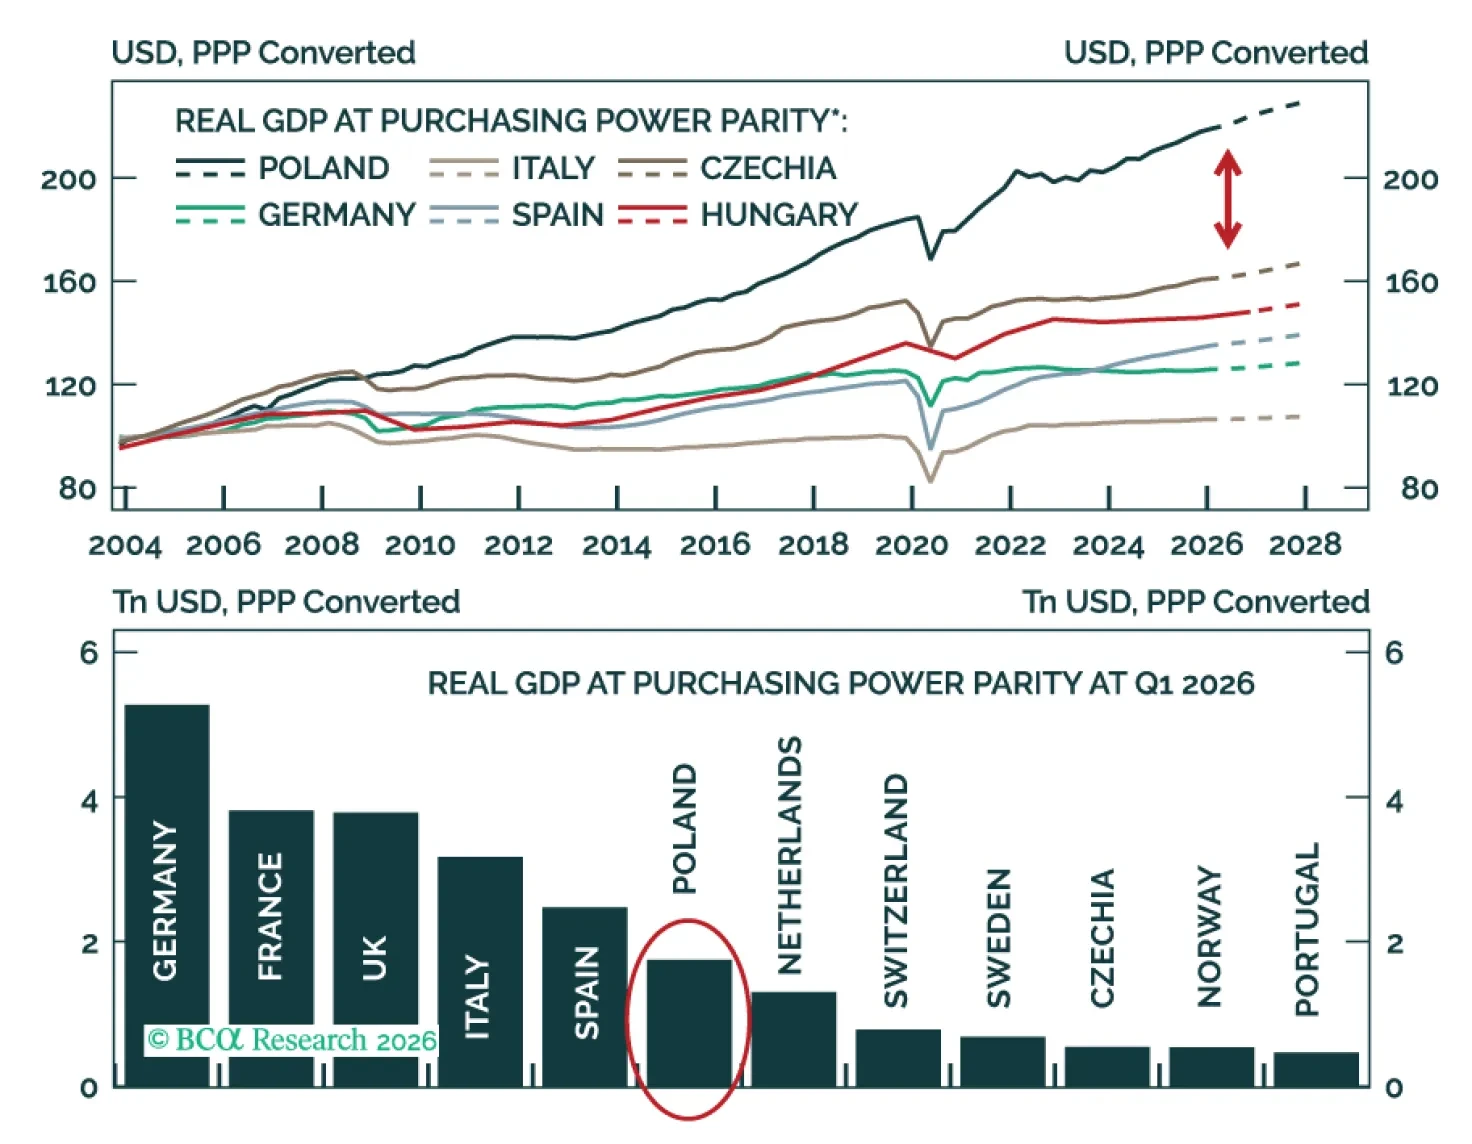
Poland’s near-term growth story remains compelling: surging EU investment should cushion European weakness and support equity outperformance. But the clock is ticking. Demographics, skills shortages, and fiscal deterioration will increasingly constrain convergence. Favor Polish equities and the belly of the curve; expect further near-term zloty weakness against the euro.