Economy
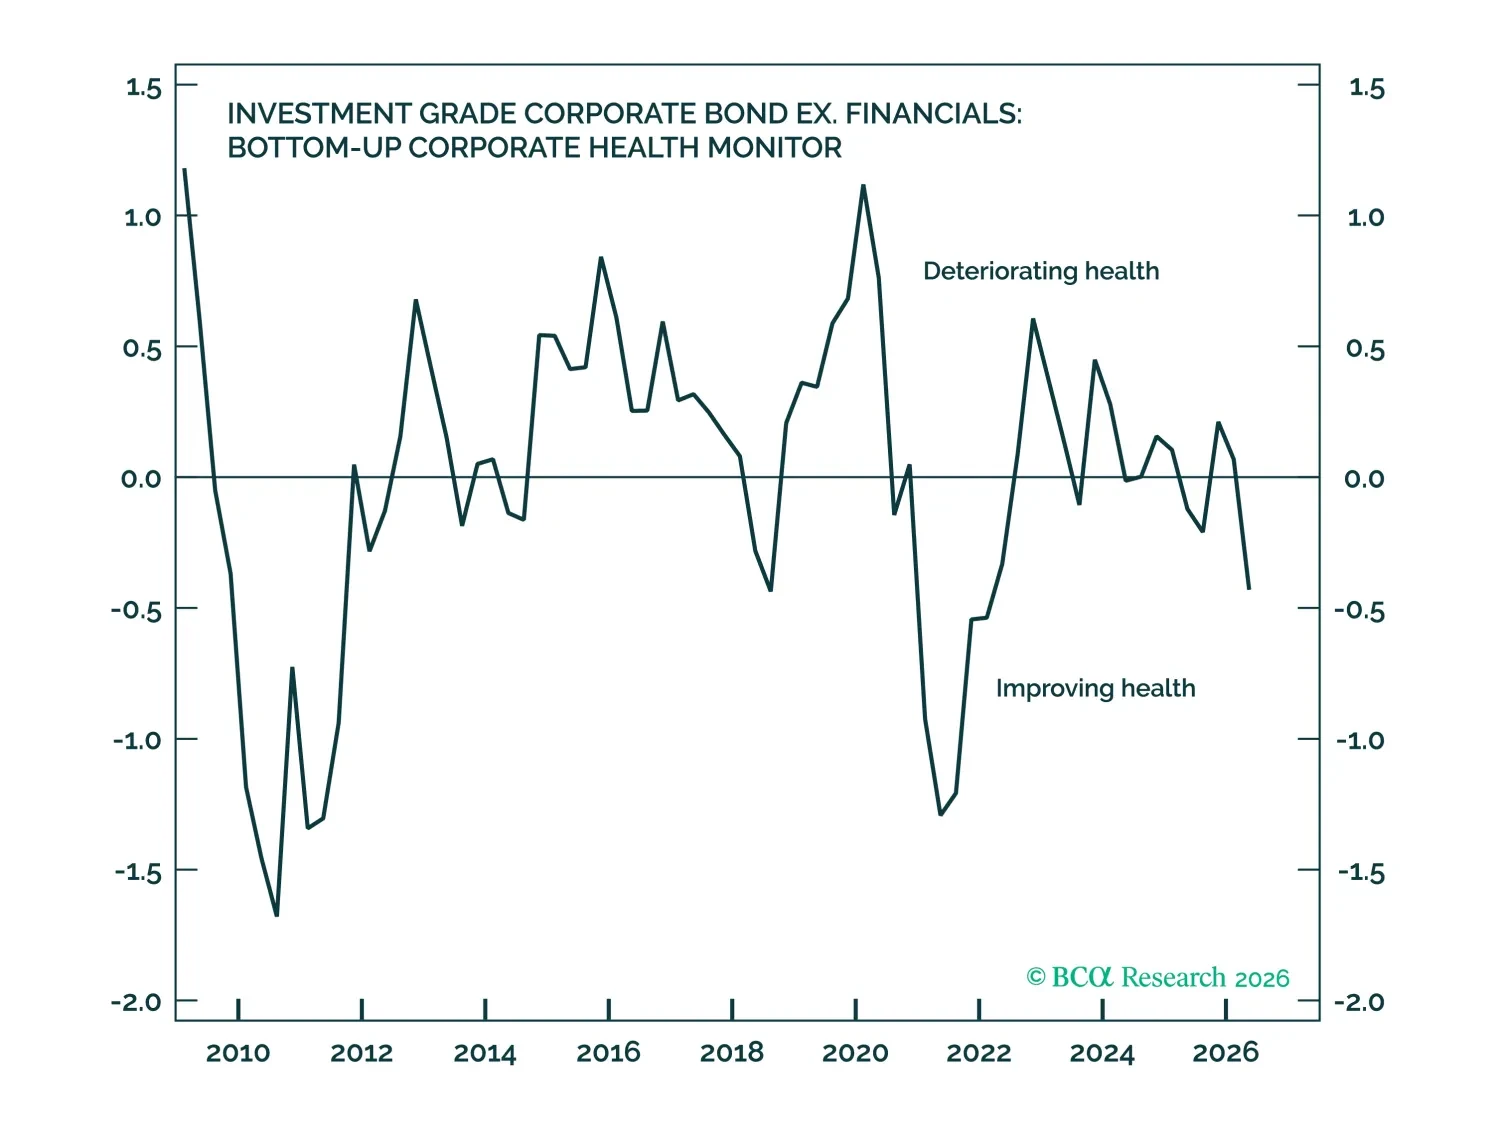
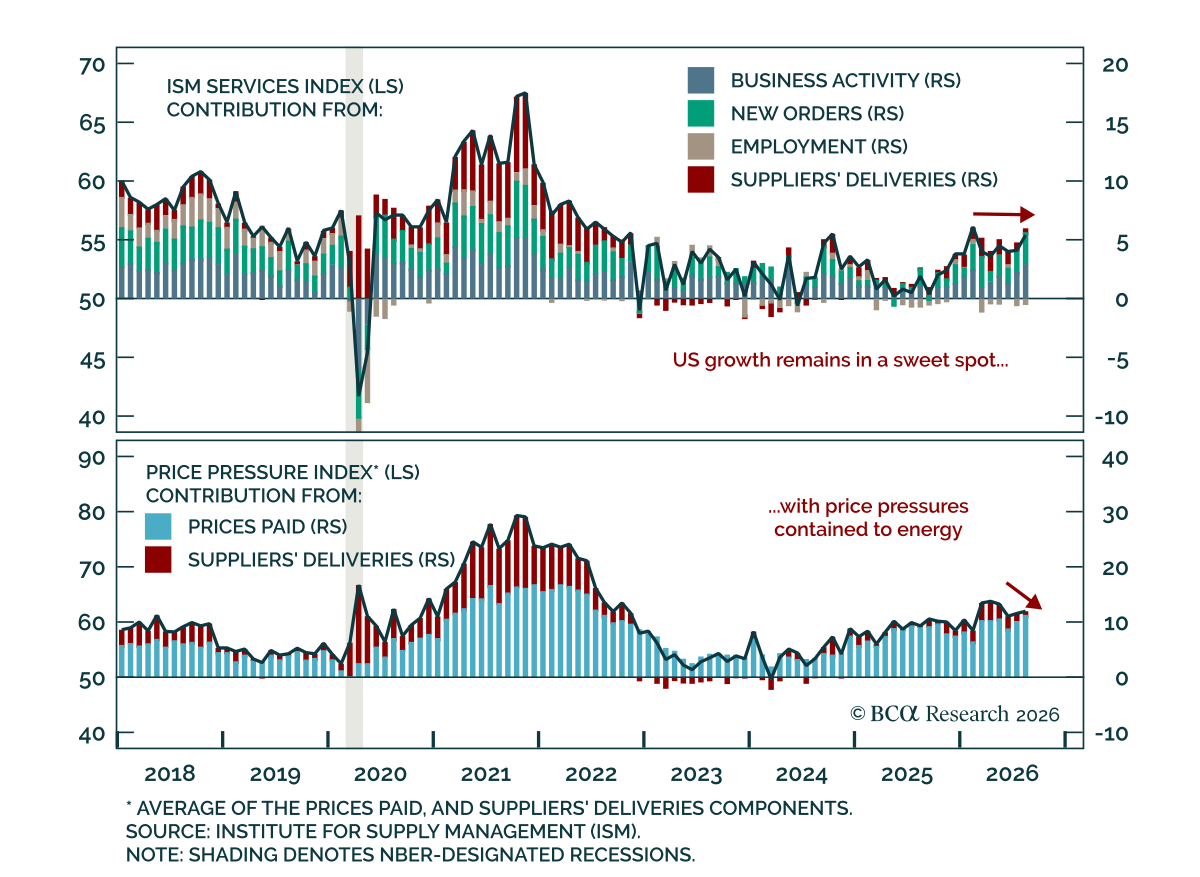
US corporate balance sheet health looks strong overall, and credit metrics aren’t showing any significant negative impact from the AI issuance boom.
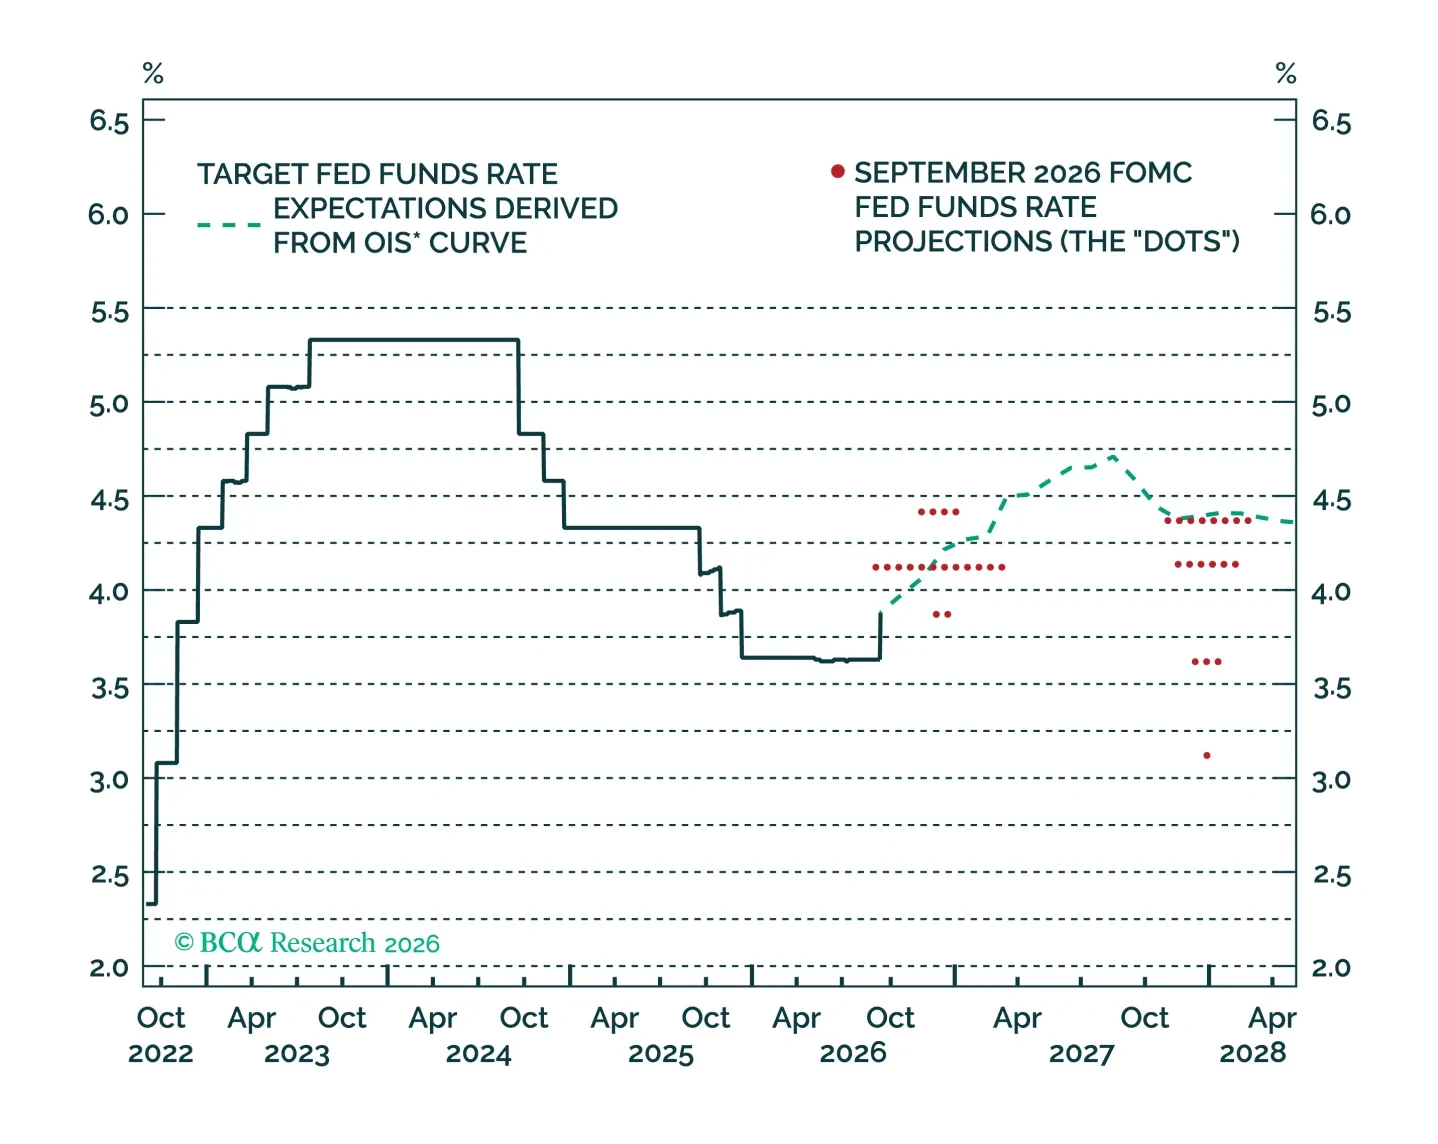
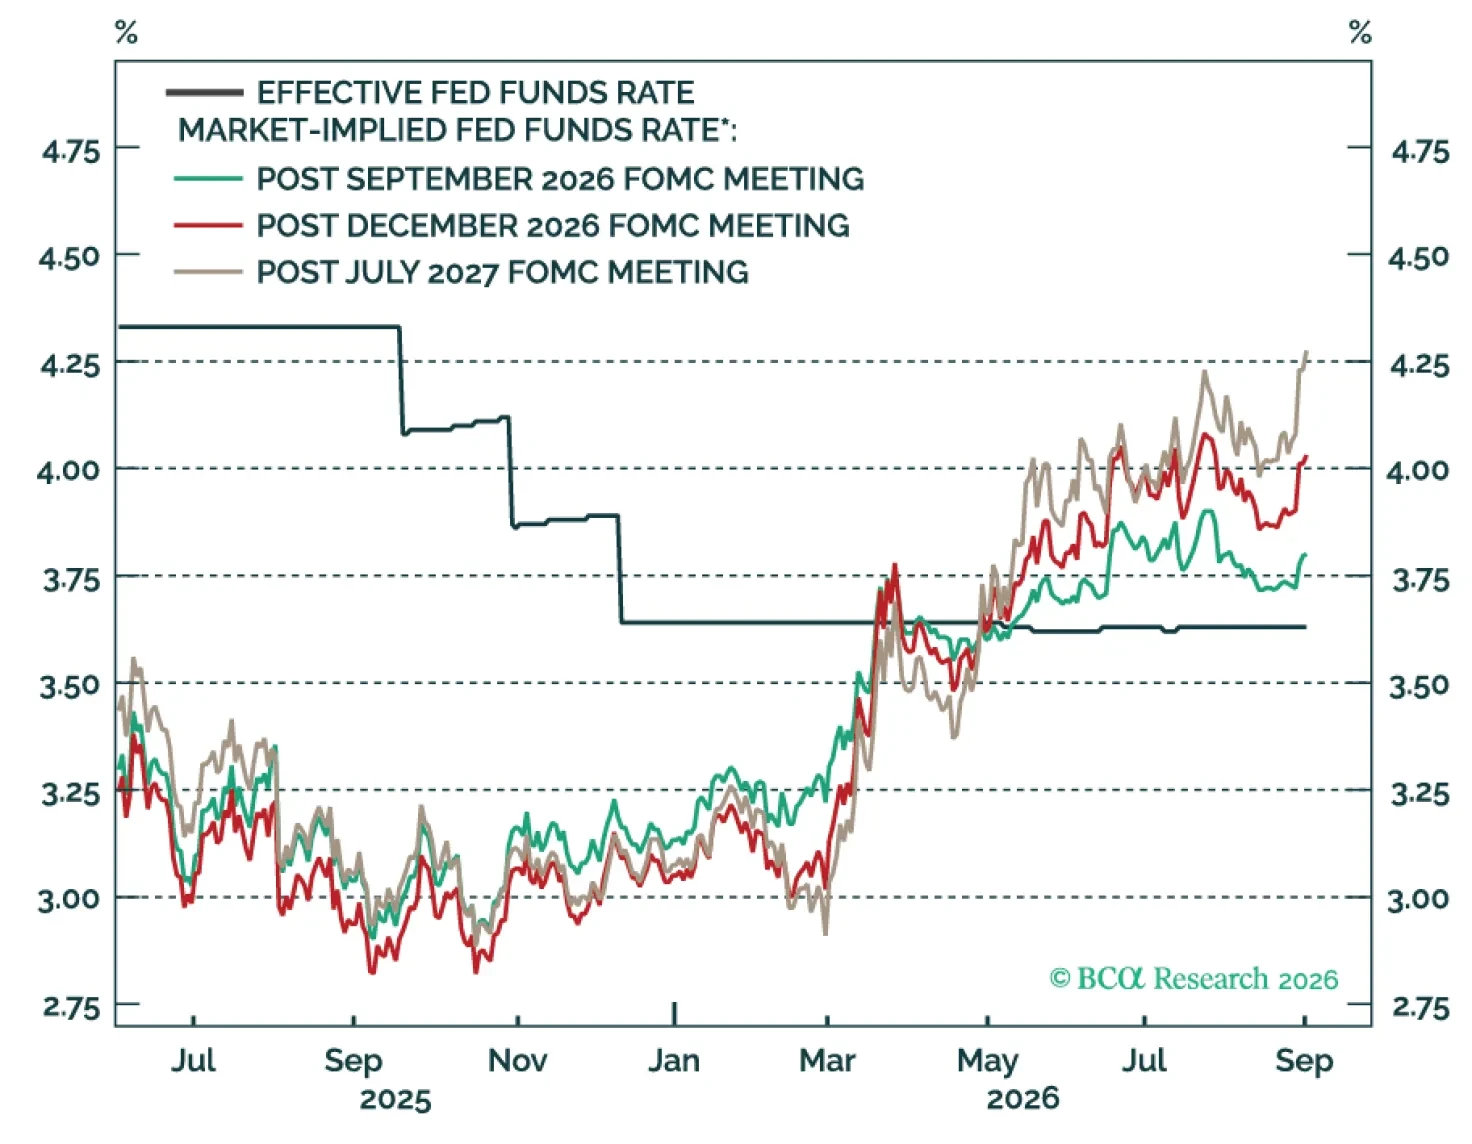
The Fed is unanimous in expecting a mild tightening cycle of no more than 75 bps, but that outcome is contingent on a rapid drop in core inflation in 2027.
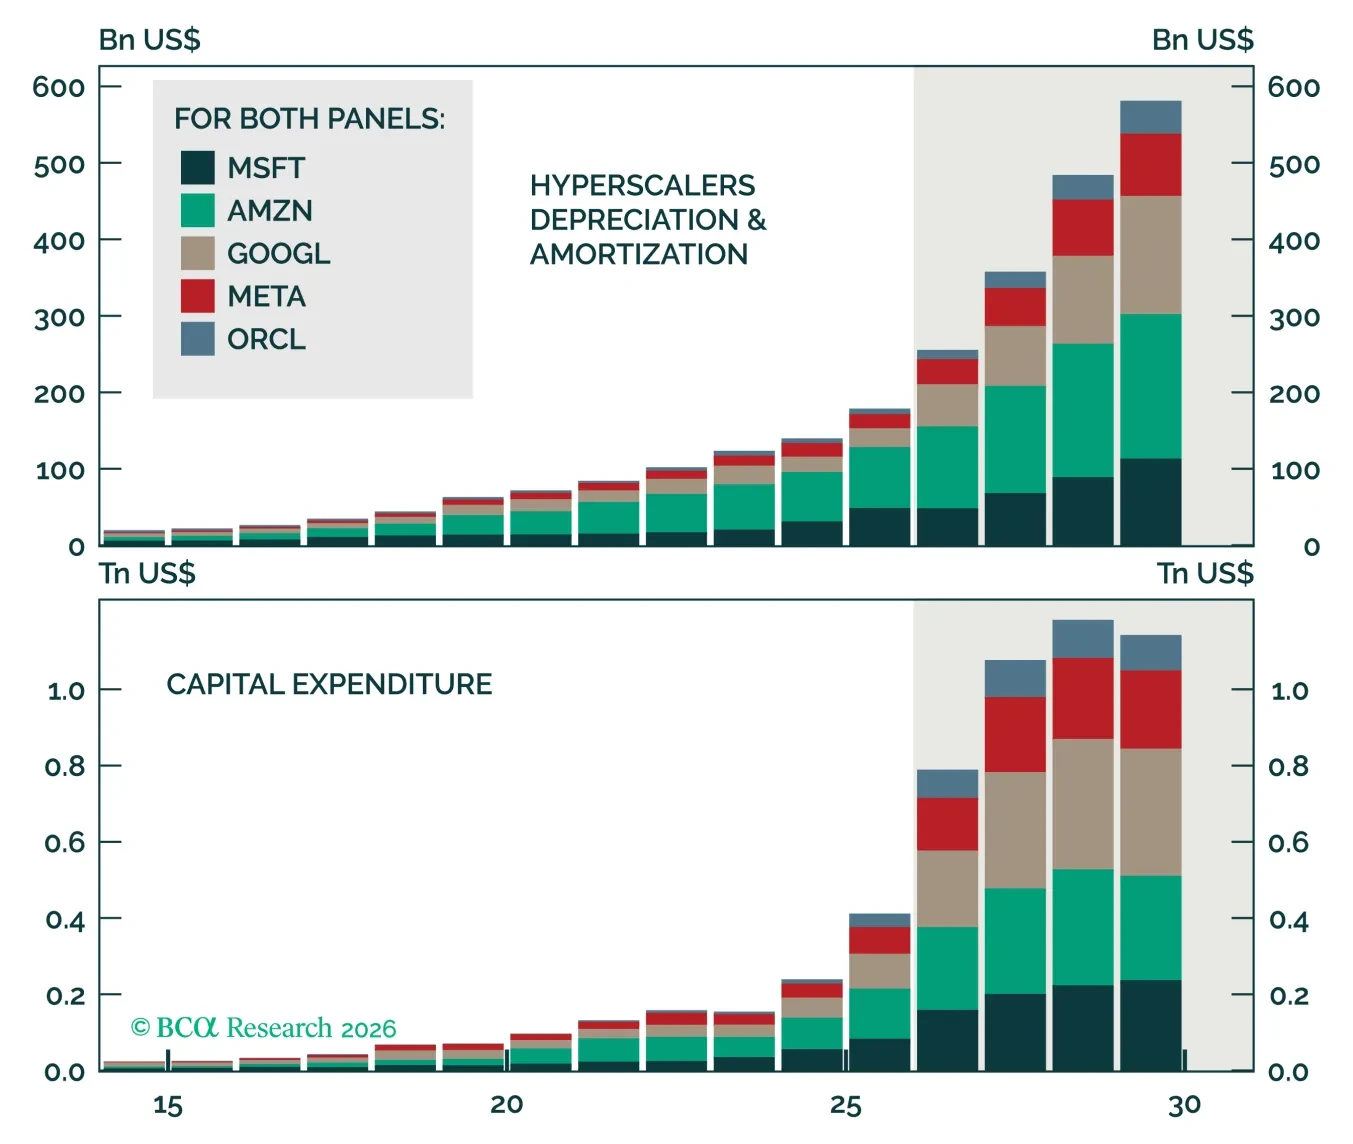
Concerns by the major AI companies that they are locked into a financially unsustainable arms race for AI dominance are likely playing as much a role in their newfound “go slow” approach as concerns over AI doom.
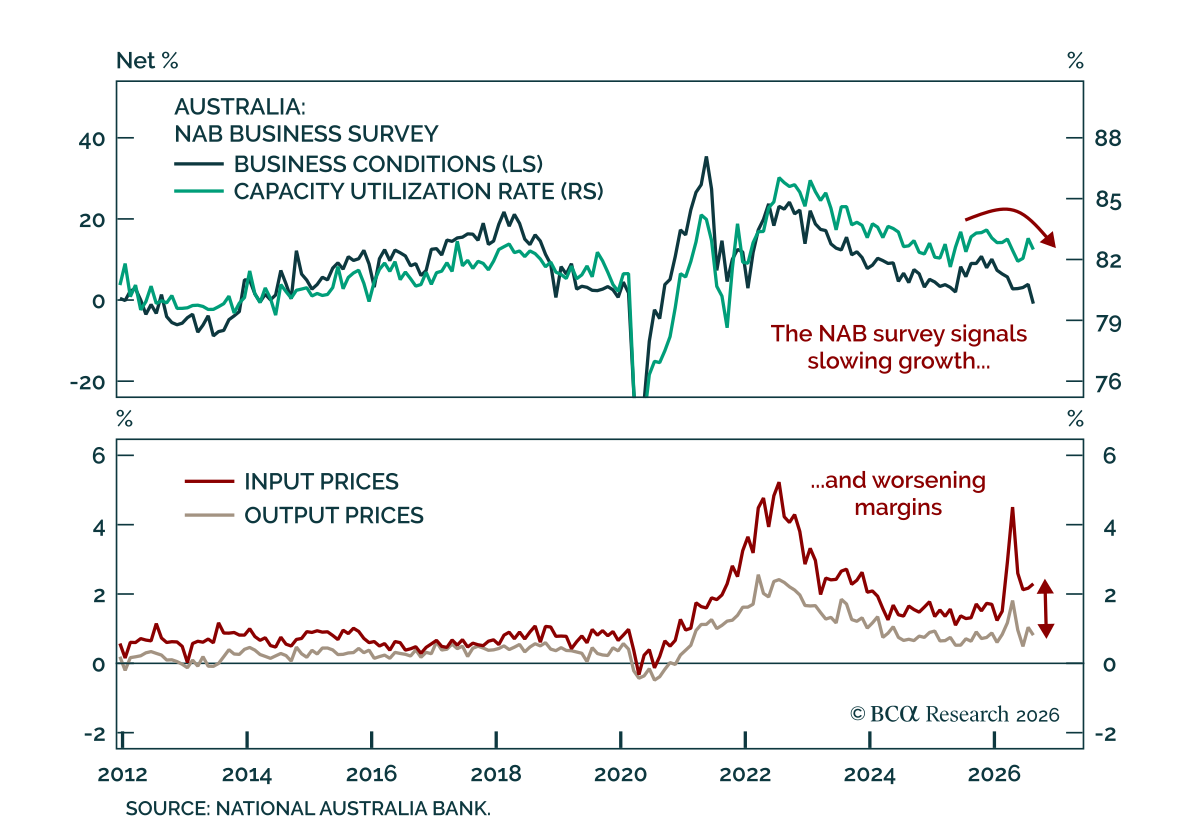
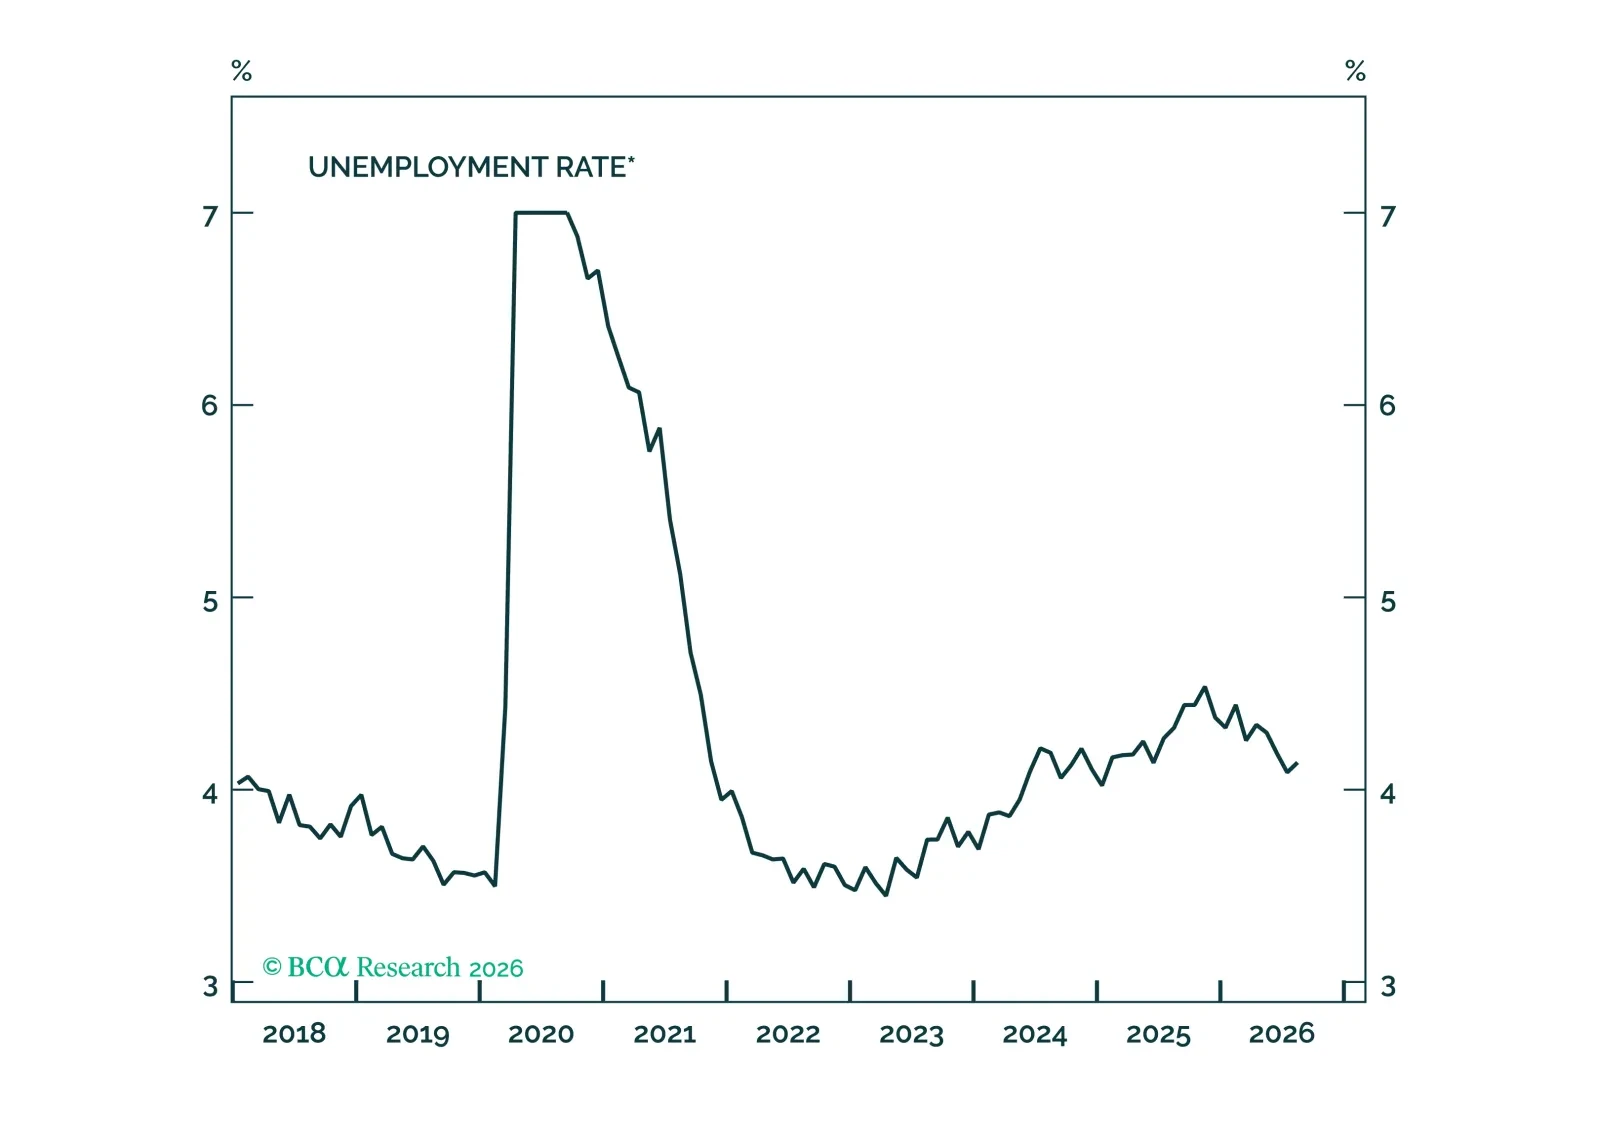
Next week’s CPI and PPI reports will be much more important determinants of the near-term Fed policy path than this morning’s employment report. However, if the trend of labor market tightening continues through year-end, it could lead to a re-acceleration of wage growth in 2027.
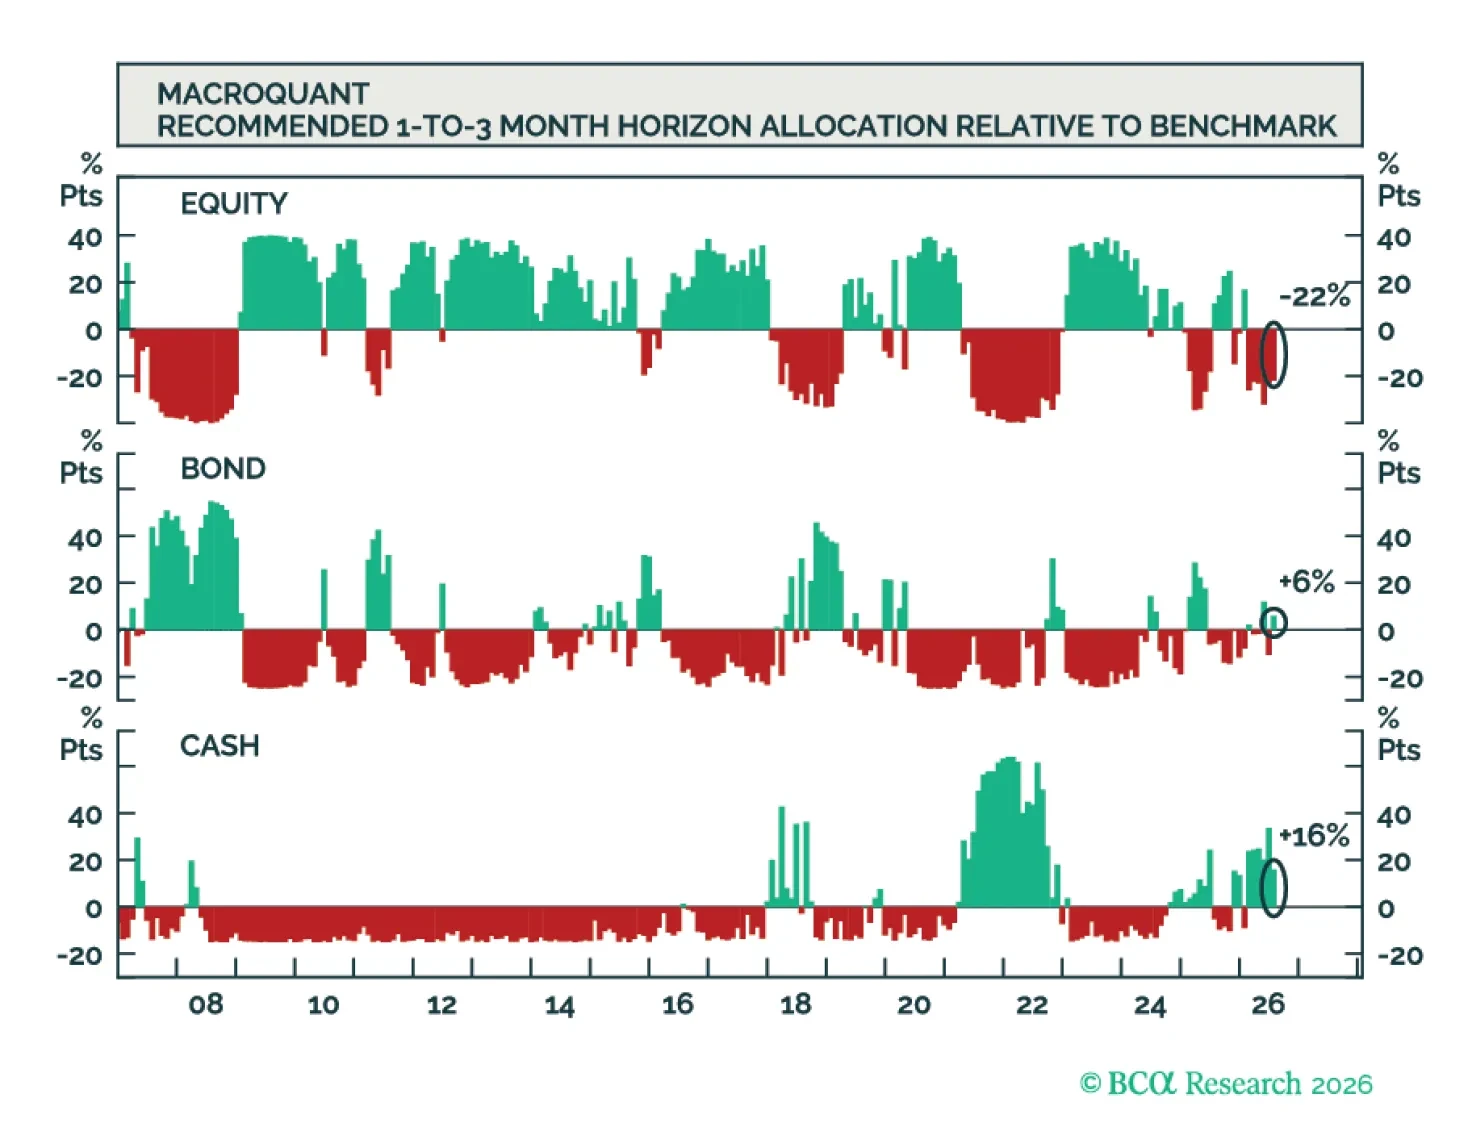
MacroQuant recommends a slight underweight position in equities, counterbalanced by a slight overweight to bonds, and a significant overweight to cash. The model is positive on the US dollar, modestly negative on gold, and bullish on copper and oil.
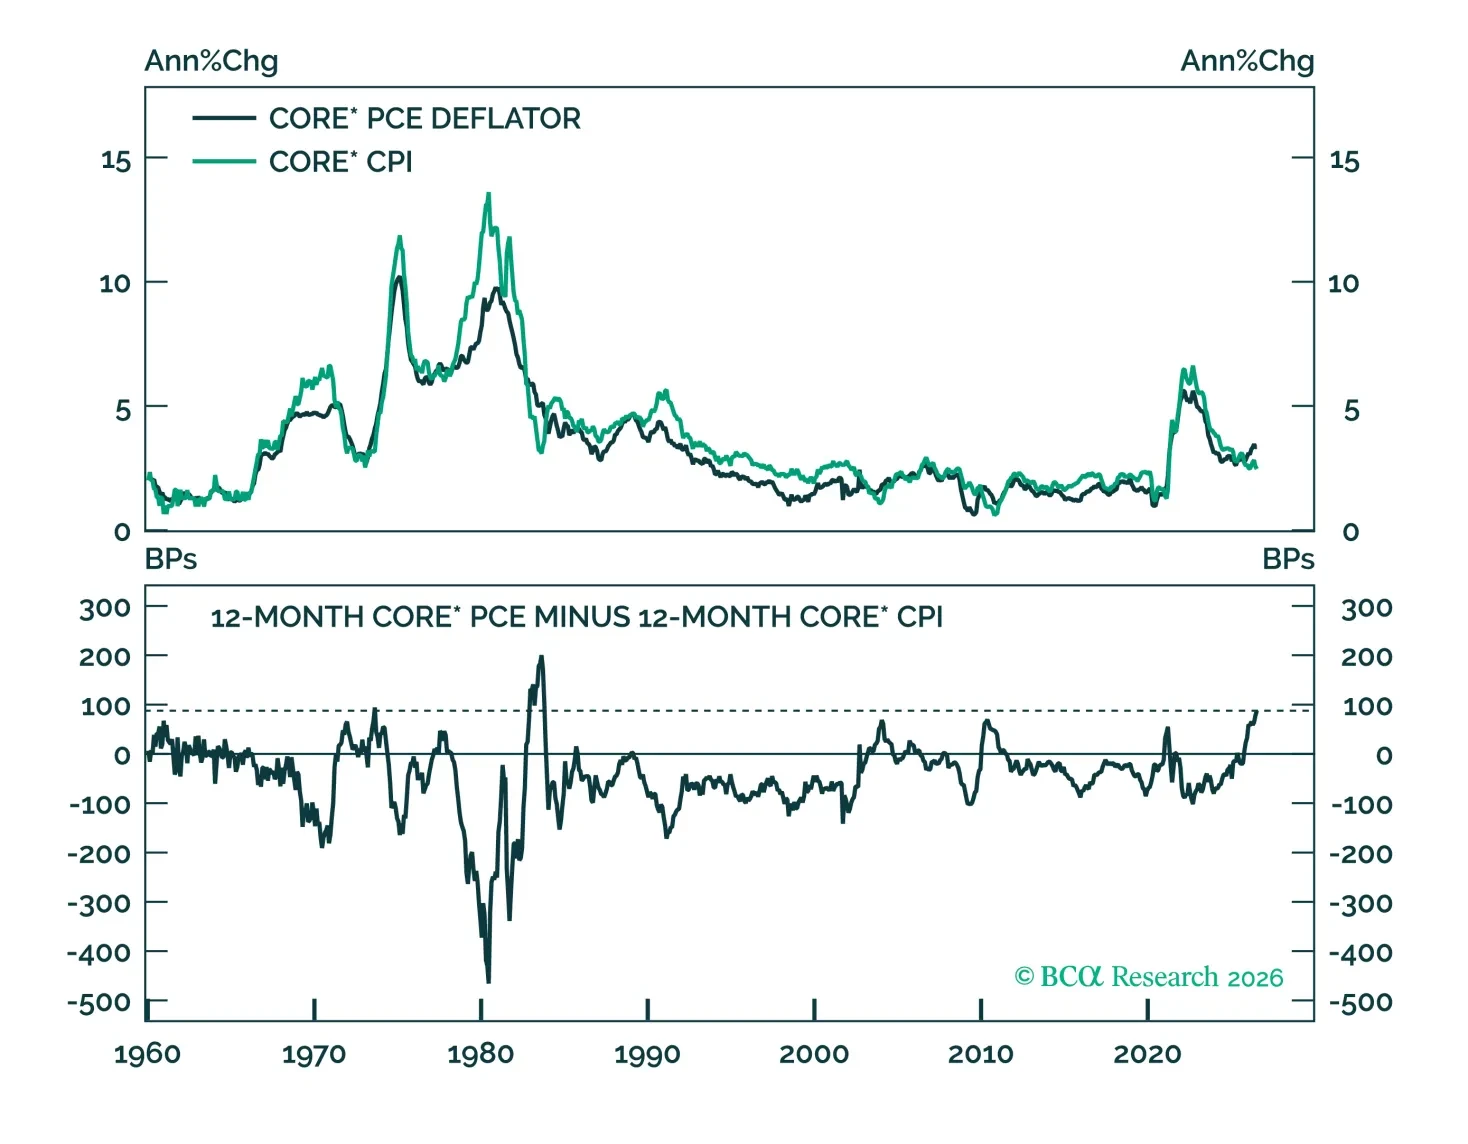
The PCE/CPI gap is an increasingly important factor driving the near-term outlook for Fed policy. We discuss the drivers of that gap and conclude that it’s likely to narrow in the coming months.
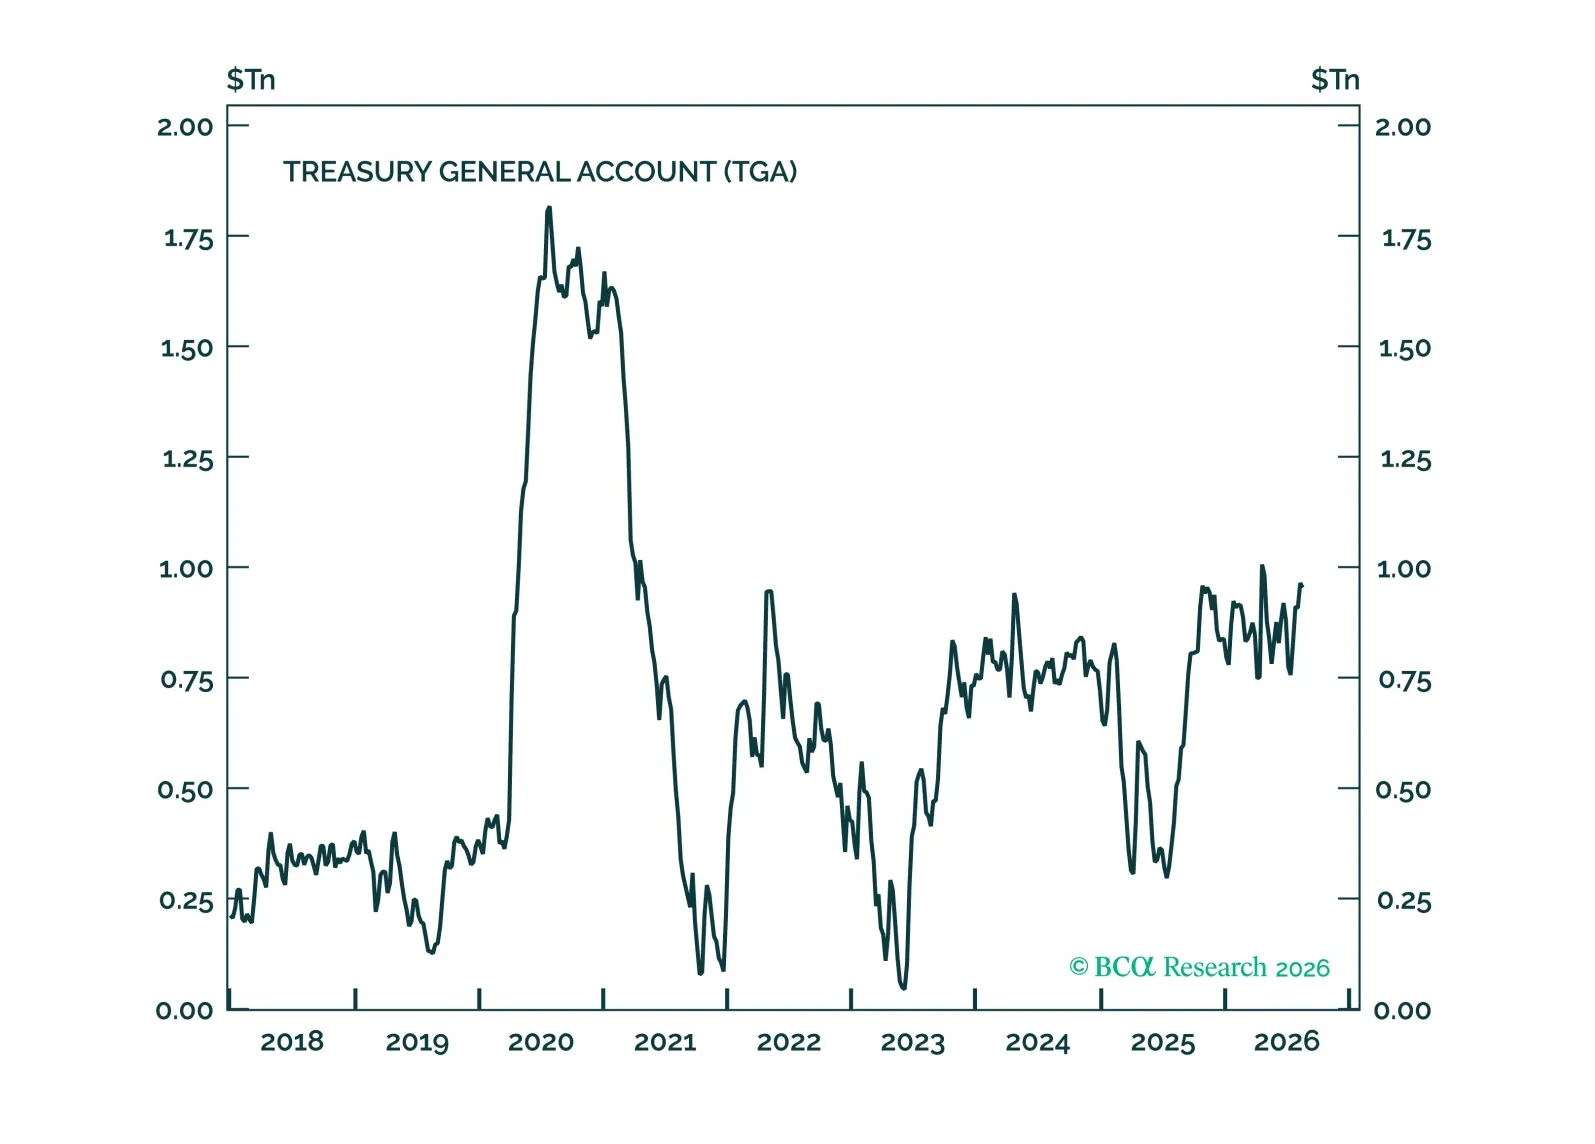
The US Treasury department’s attempts at yield suppression are doomed to fail unless the Federal Reserve gets involved.