Sorry, you need to enable JavaScript to visit this website.
Skip to main content

Fixed Income

The consensus among BCA's strategists remains overweight equities and neutral across bonds and cash on a 12-month horizon. Within equities, the US moves to underweight relative to MSCI ACWI on a 12-month view; on a 3-month horizon, we remain overweight.…
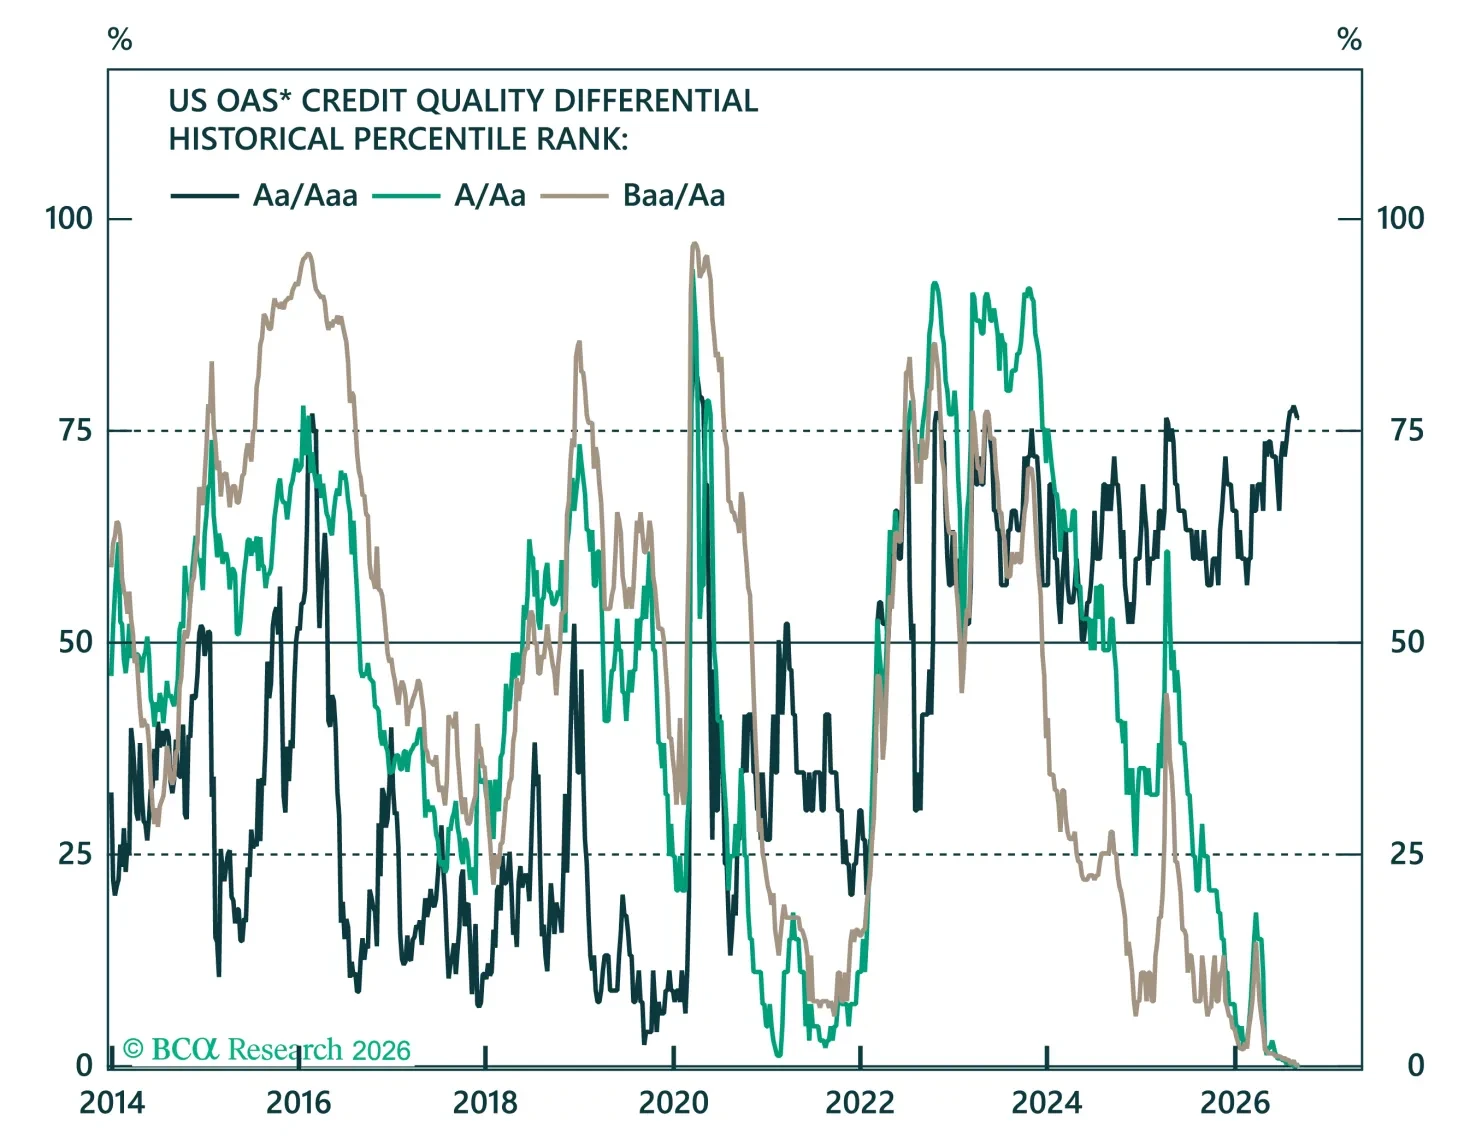
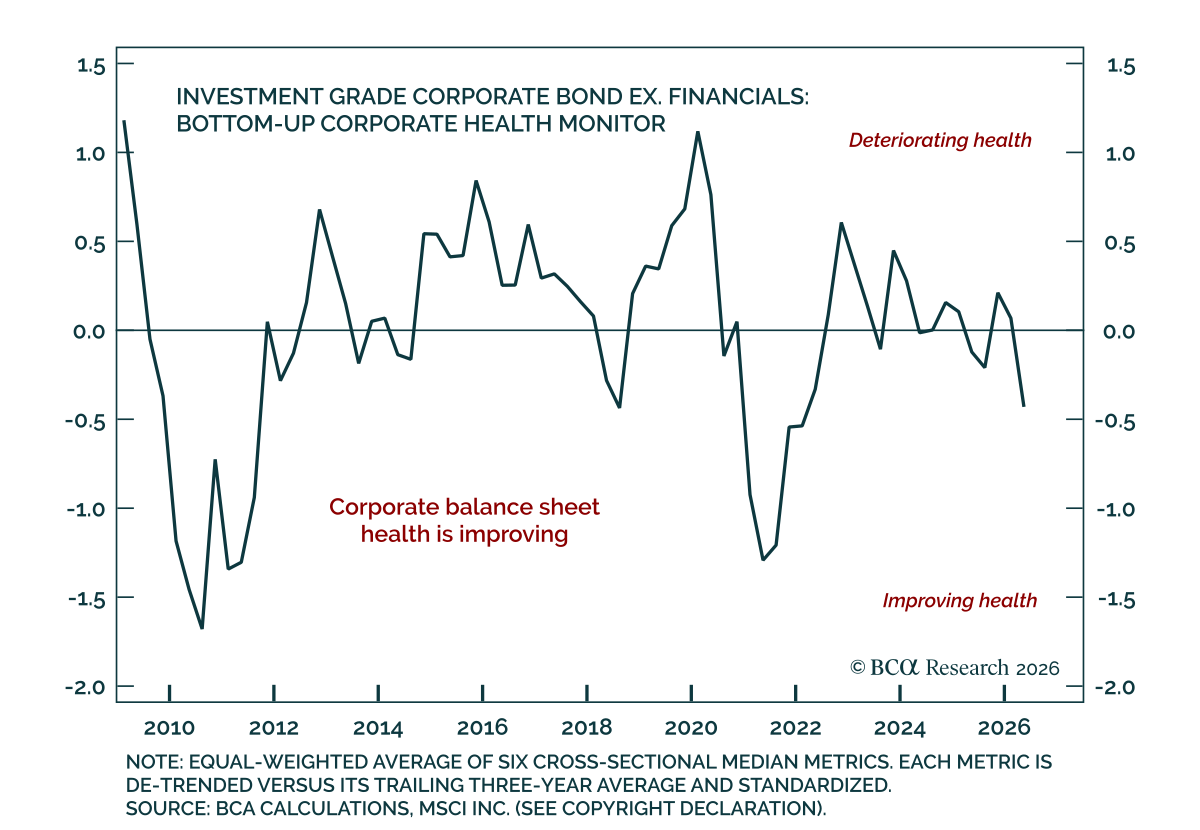
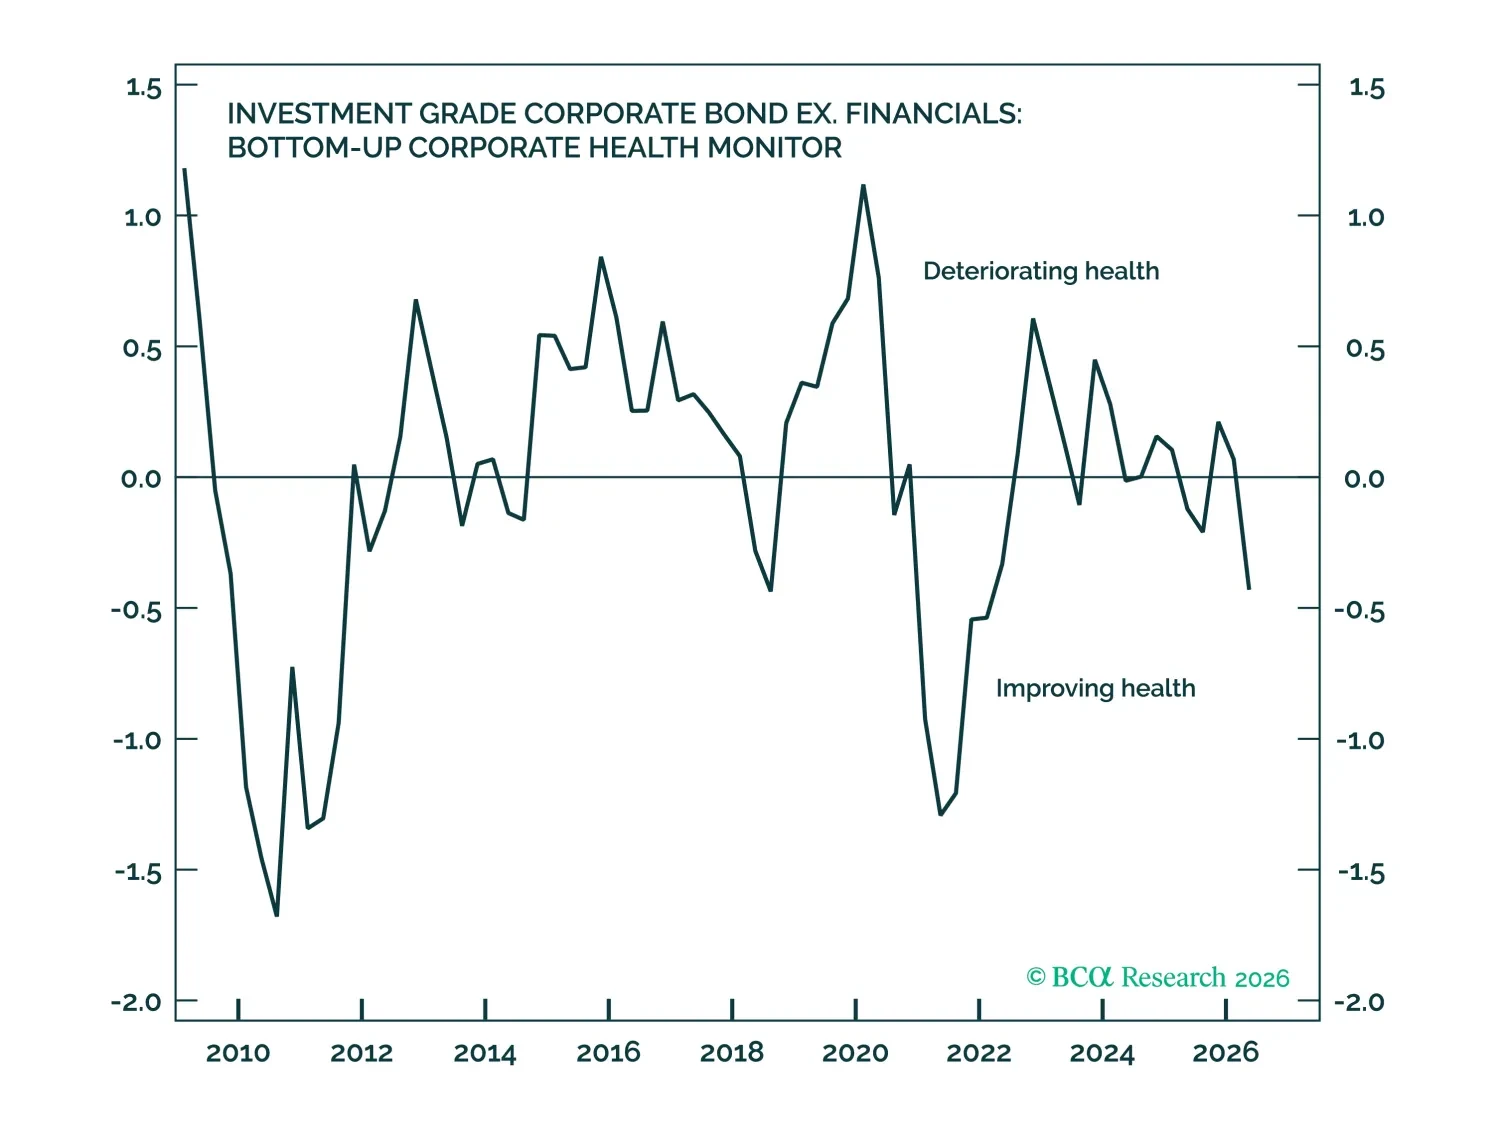
Our US Bond strategists see no sign that this year's AI bond issuance boom has eroded US corporate balance sheets. Gross investment grade issuance has already surpassed 2020 levels, yet their top-down and bottom-up Corporate Health Monitors both point to…
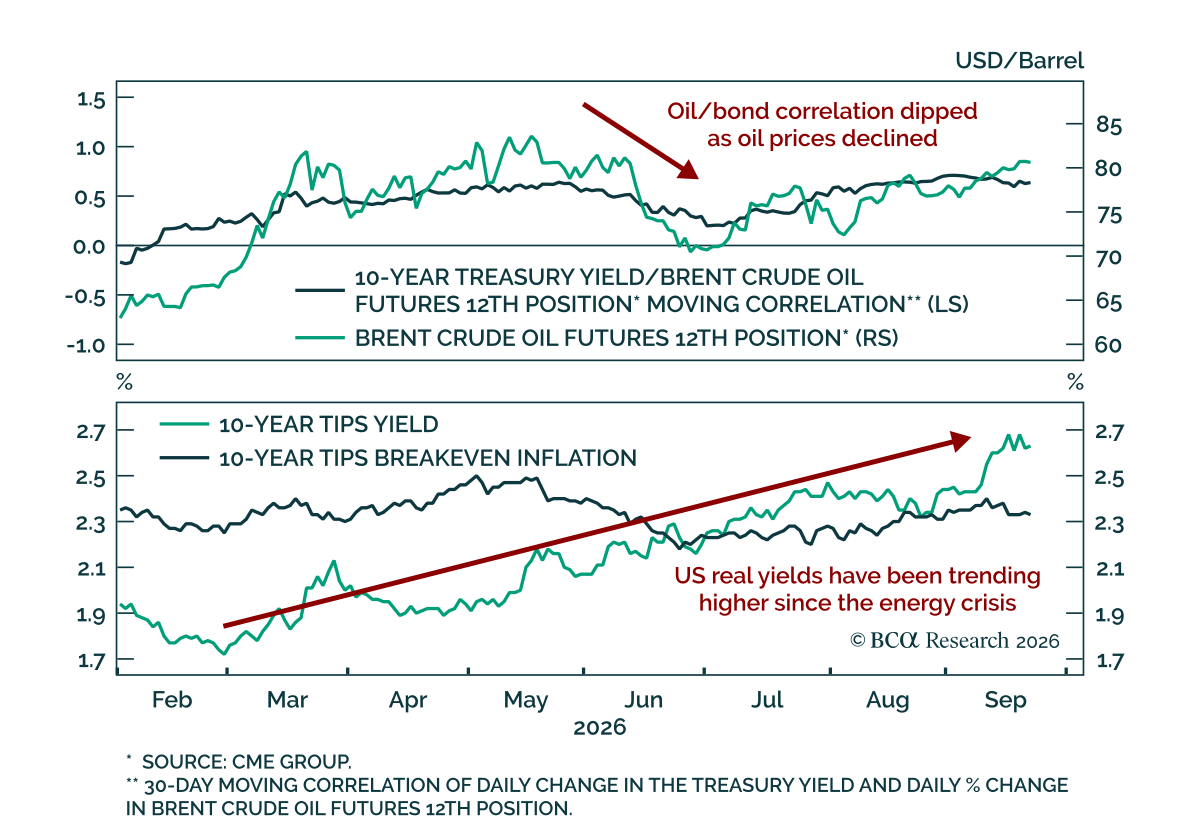
Oil prices and US Treasury yields have moved in lockstep this year, but oil matters less for US yields than the correlation suggests. The joint rise is not purely a coincidence. Higher oil prices play a role in the hawkish repricing of the Fed's policy path,…
Special Report

US corporate balance sheet health looks strong overall, and credit metrics aren’t showing any significant negative impact from the AI issuance boom.
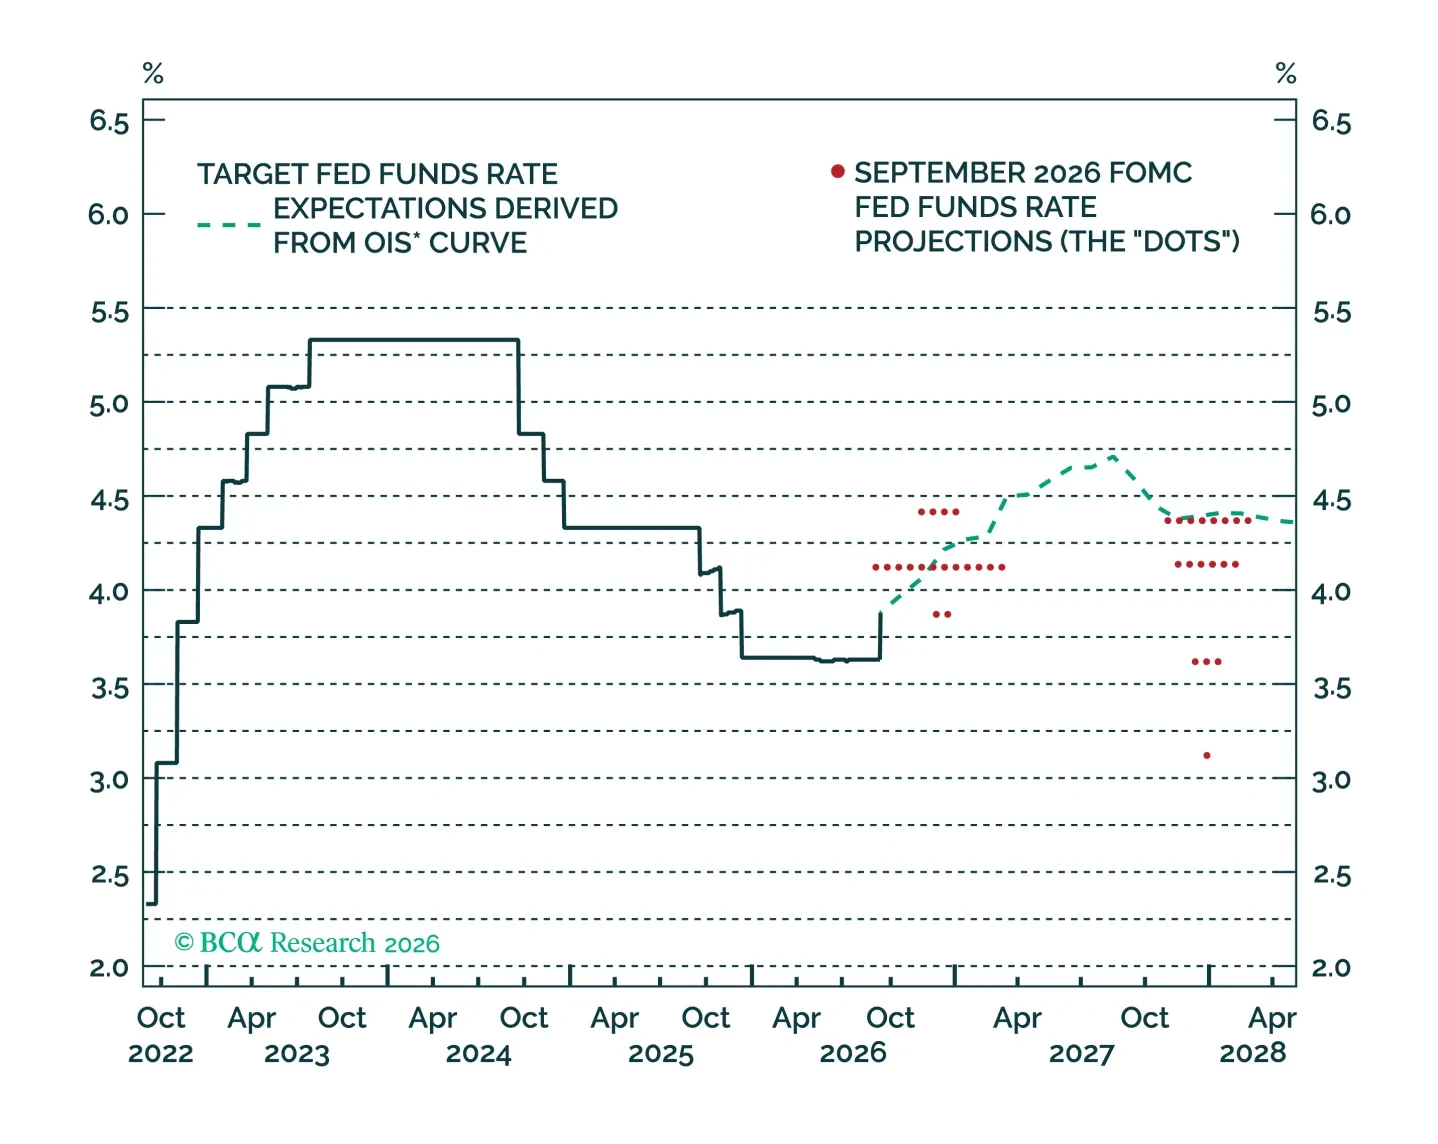
The Fed is unanimous in expecting a mild tightening cycle of no more than 75 bps, but that outcome is contingent on a rapid drop in core inflation in 2027.
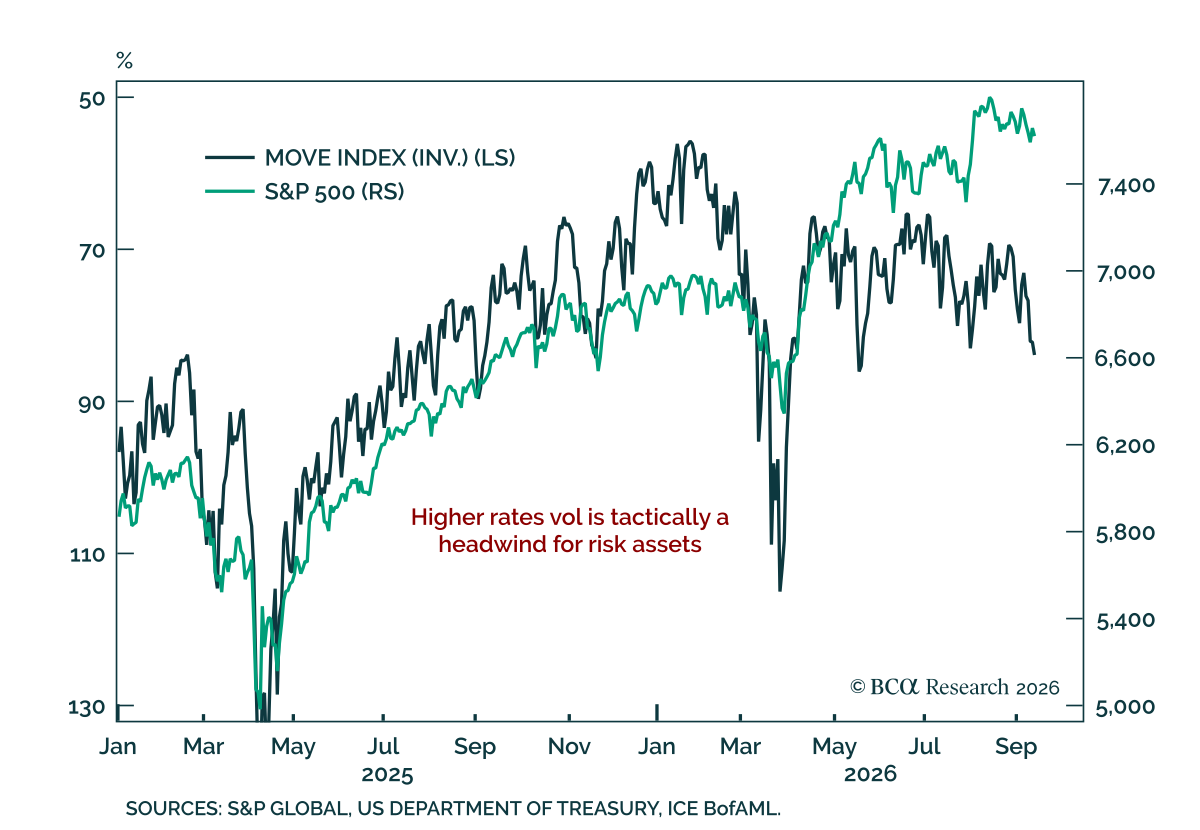
 

Higher bond yields are becoming a more important risk for equity markets, but the implications depend on whether Fed tightening remains mild or develops into a genuine hiking cycle. At our September Views meeting, our US Bond strategists outlined two…

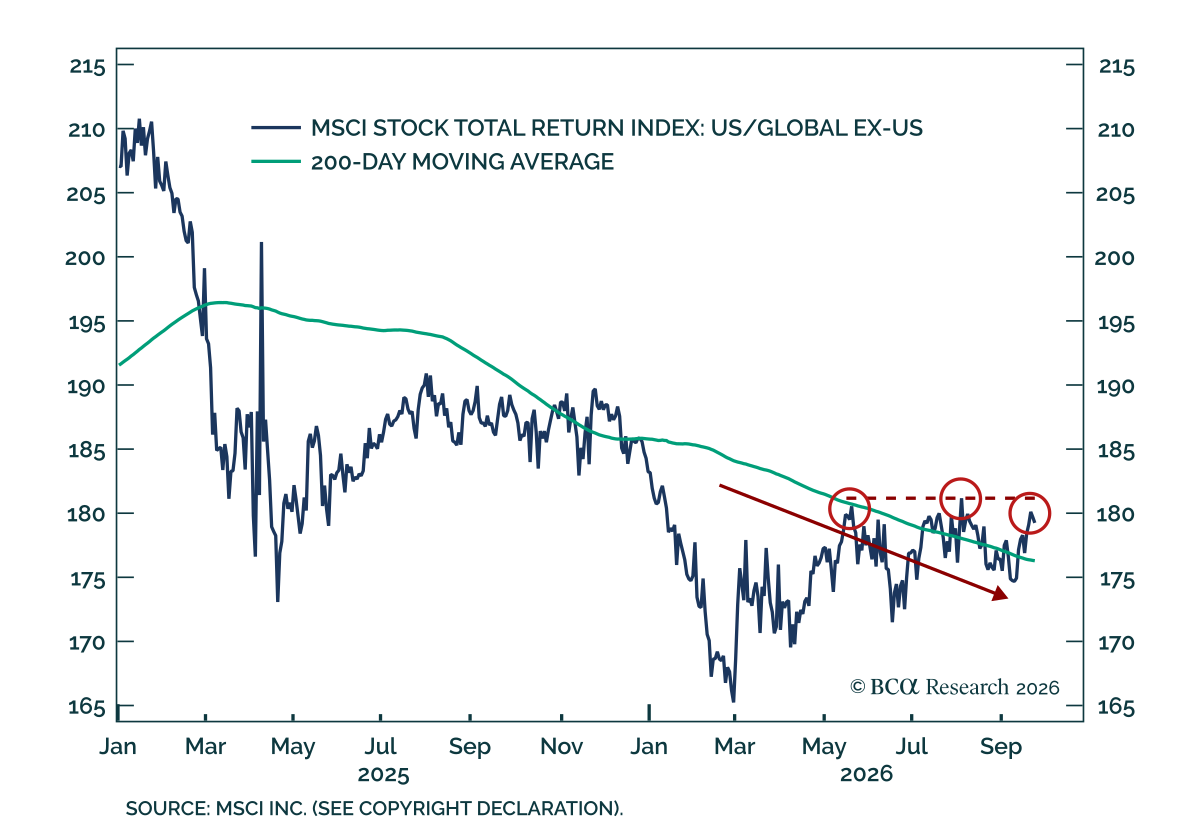
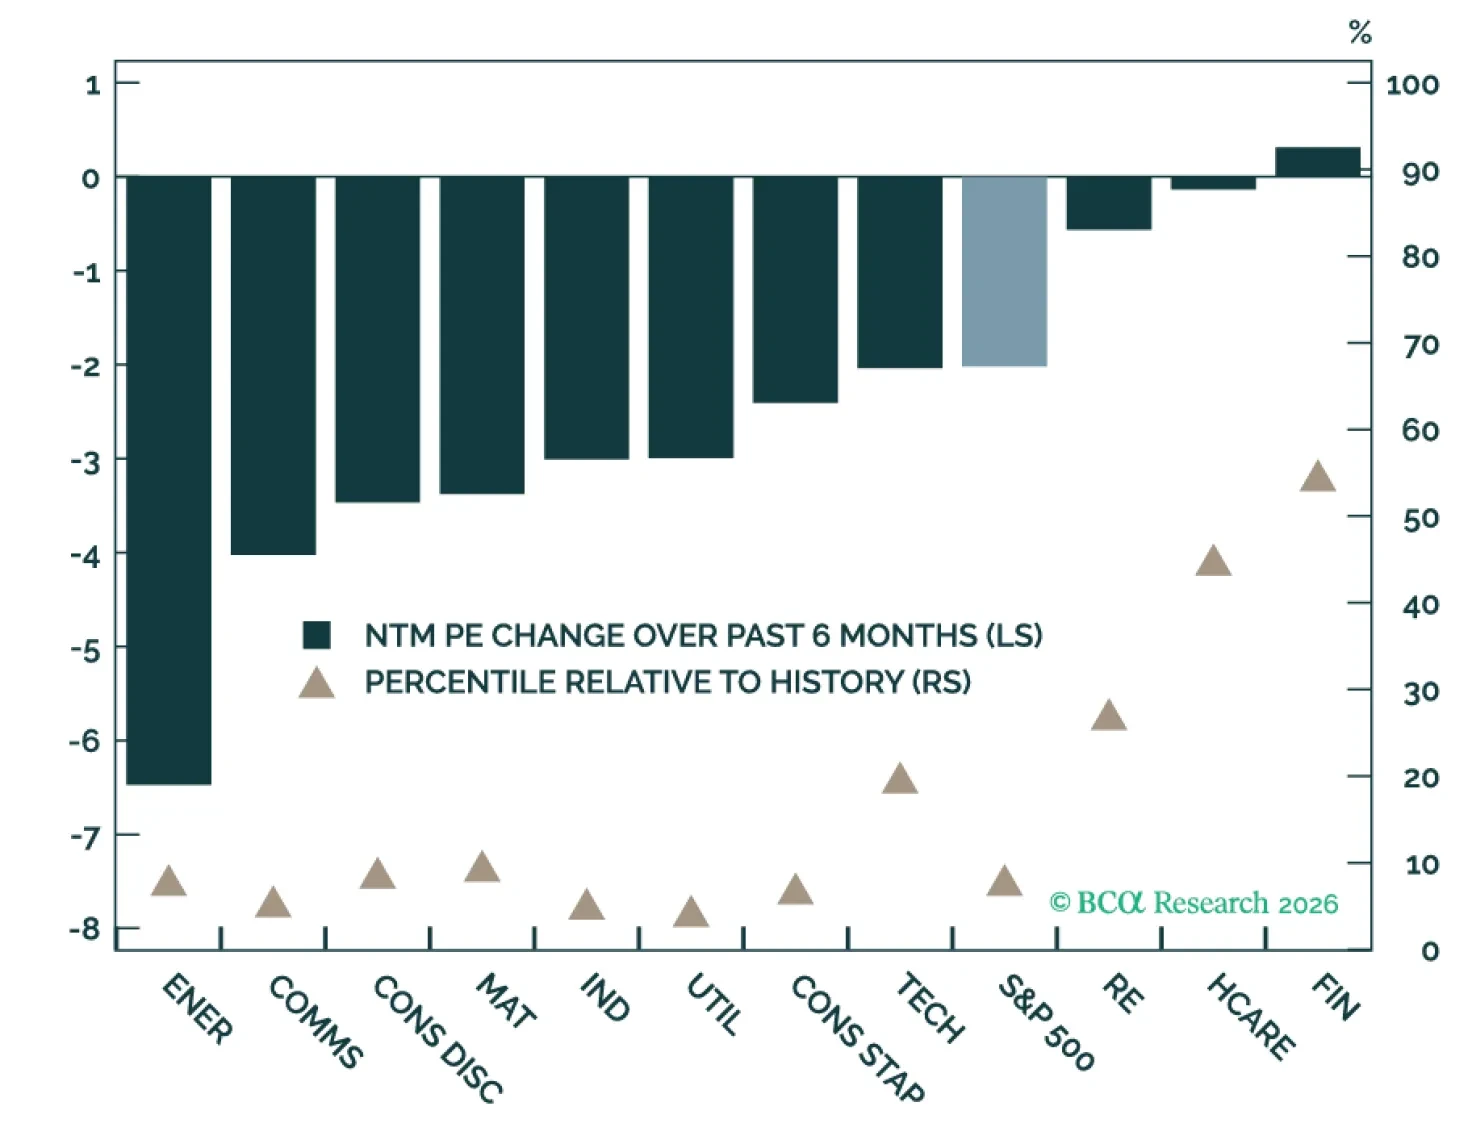
We remain constructive on US equities, but higher yields, slower EPS growth and heavy IPO issuance remain significant risks to valuations, leaving the path to our year-end target increasingly dependent on earnings. Tactically, there has already been a significant, but benign, compression in multiples, as earnings have outpaced prices. A well-communicated Fed hike could ease rather than intensify bond-market uncertainty. 
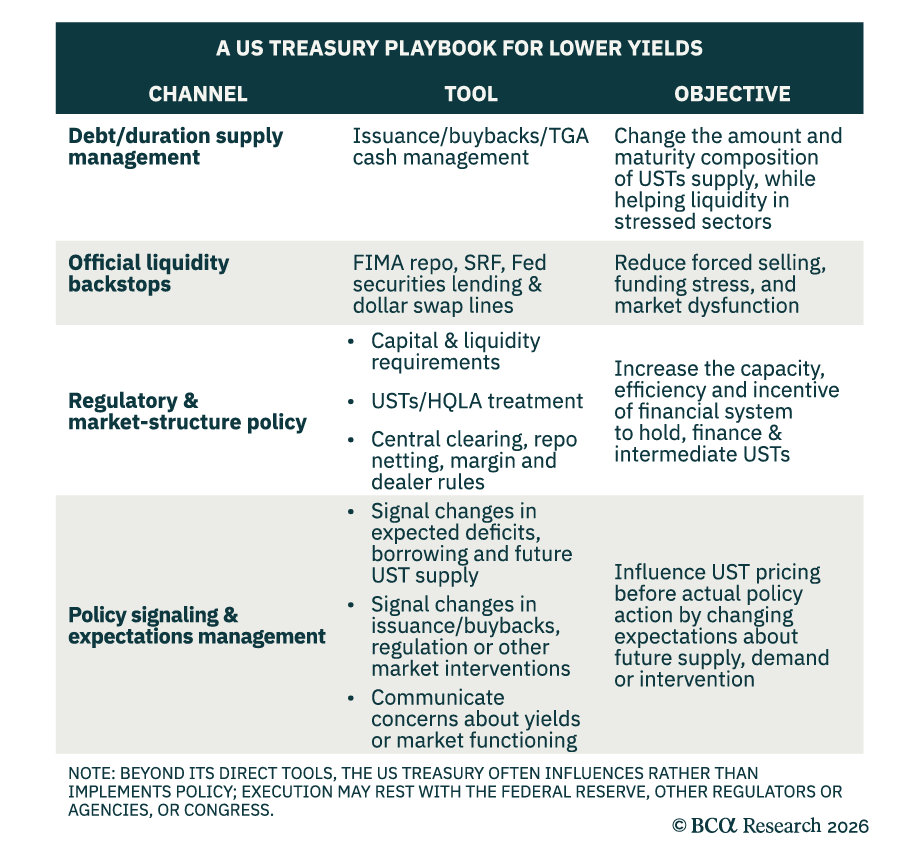
The US Treasury’s departure from regular and predictable issuance will add upside to the term premium. The 10-year Treasury yield reached its highest level since 2023 on Wednesday, touching 4.85% intraday after the Treasury announced buybacks of up to $6bln.…

After two weeks on the road talking to investors across ANZ and India, this report addresses the questions that came up most: from investment grade issuance concerns to the selloff at the long end, and what's really driving JGBs, the yen, and the outlook for Australian and New Zealand rates.
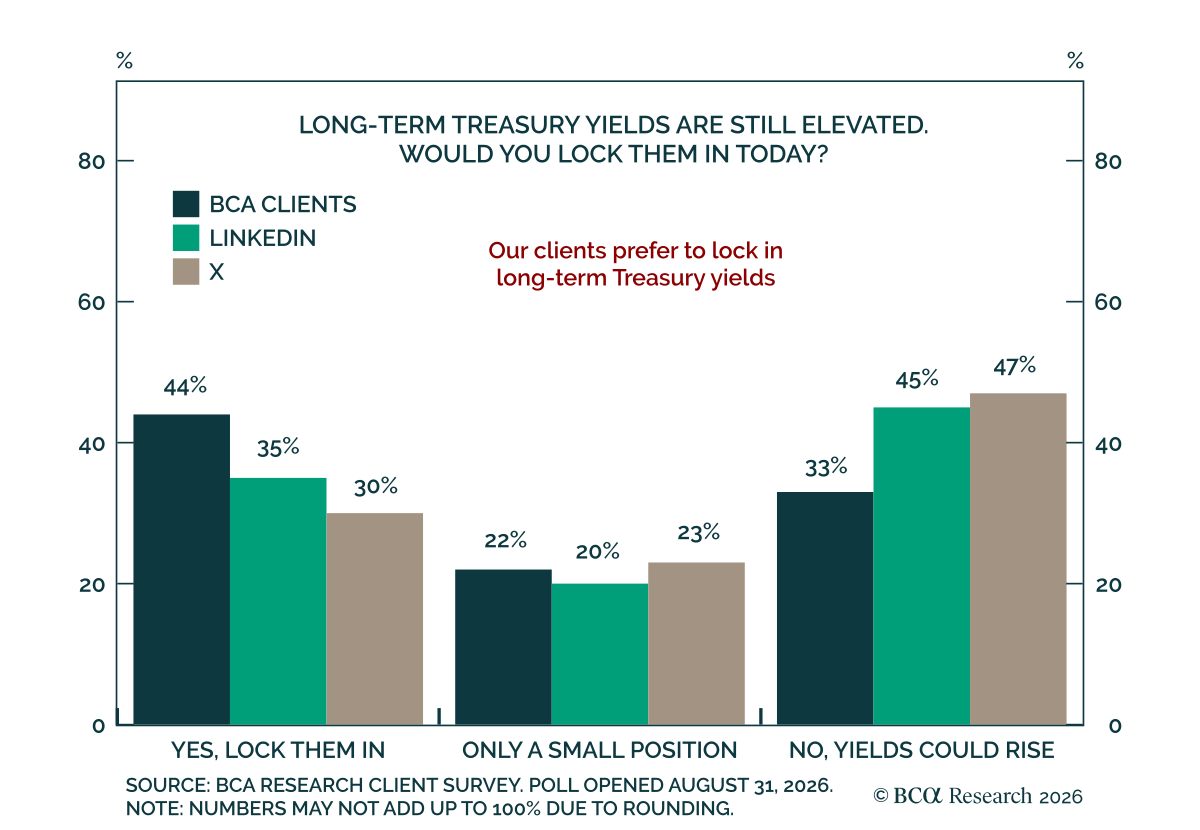
Our clients favor taking advantage of elevated long-term yields. In last week’s poll, we asked respondents whether they would consider locking in long-term Treasury yields at their elevated level. 44% of BCA clients said yes and another 22% would take a small…