Latest from BCA Research

Today’s ECB rate hike is not the beginning of a hiking cycle. Growth concerns will soon move to the forefront of ECB policy decisions, preventing further tightening.

The Bank of Canada left rates unchanged and emphasized inflation risks from higher oil prices. We discuss why inflation and labor market data argue against the tightening currently priced.
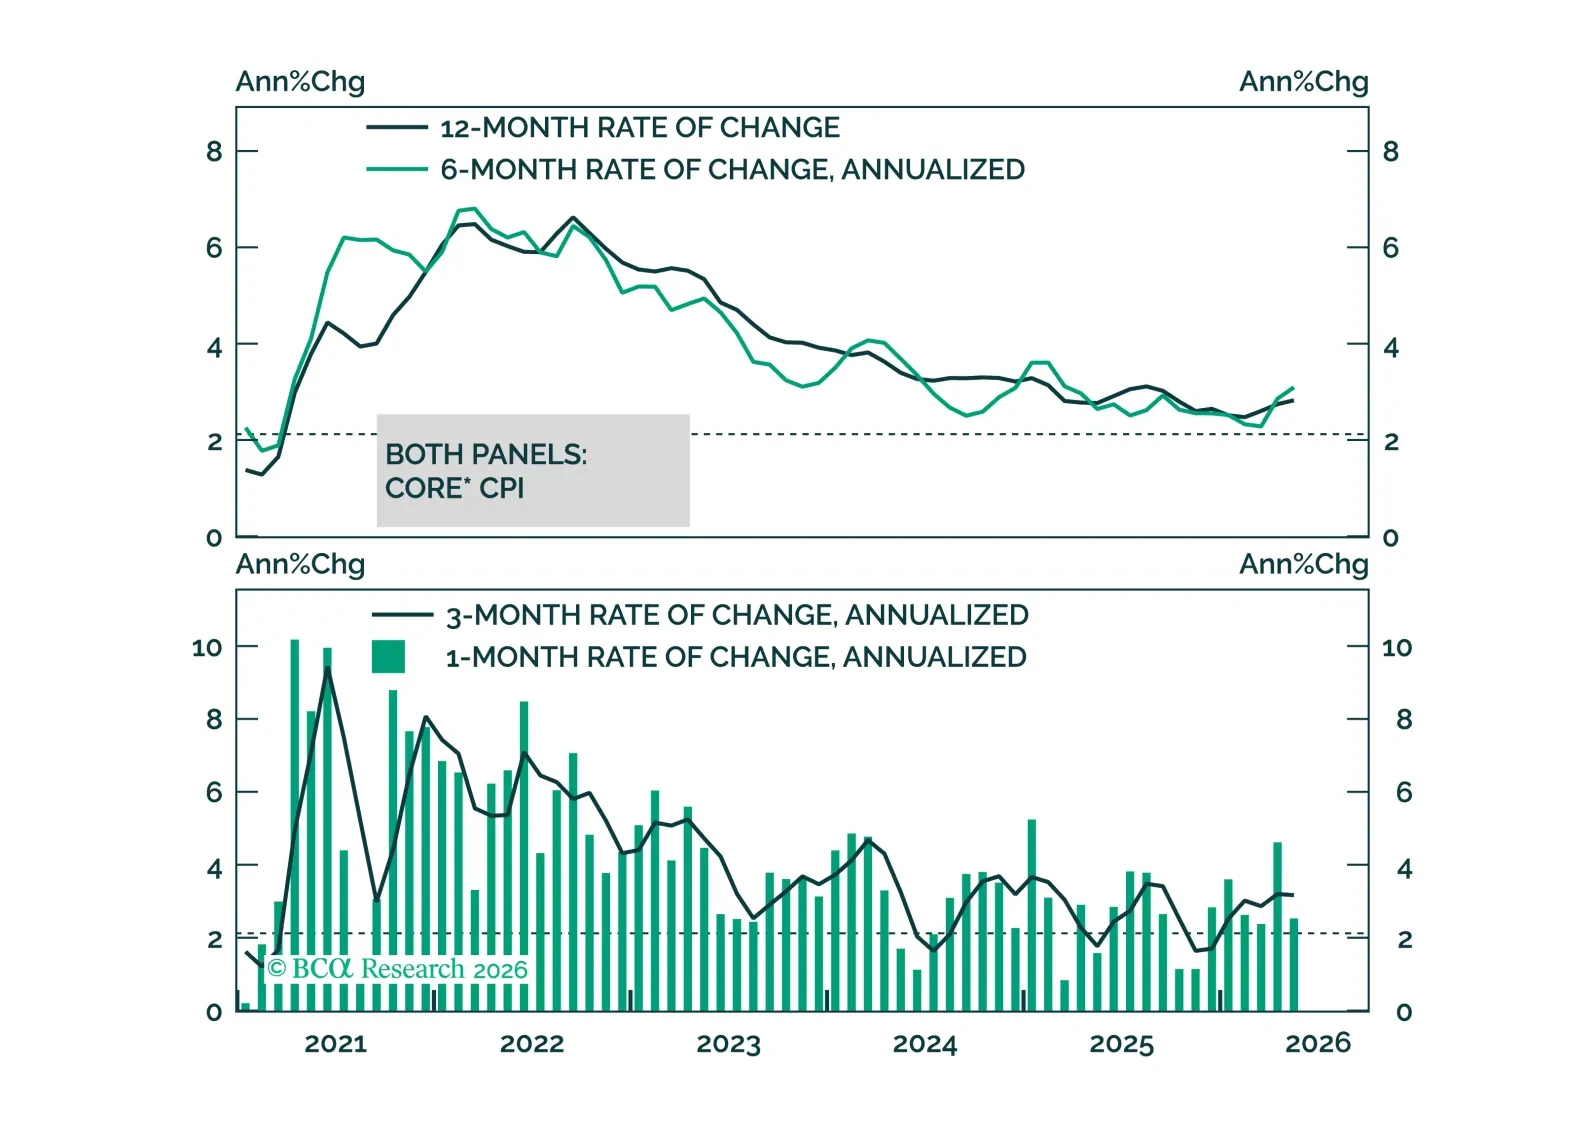
May CPI data show no evidence of passthrough from energy prices to core inflation. This will keep the Fed on hold for the time being.

Rising volatility in Korean markets captures a late-cycle surge in which euphoria and drawdown risk are rising together. While KOSPI momentum remains intact, the bigger opportunity may be emerging in the increasingly mispriced KRW, which could rally meaningfully as portfolio flow headwinds fade.
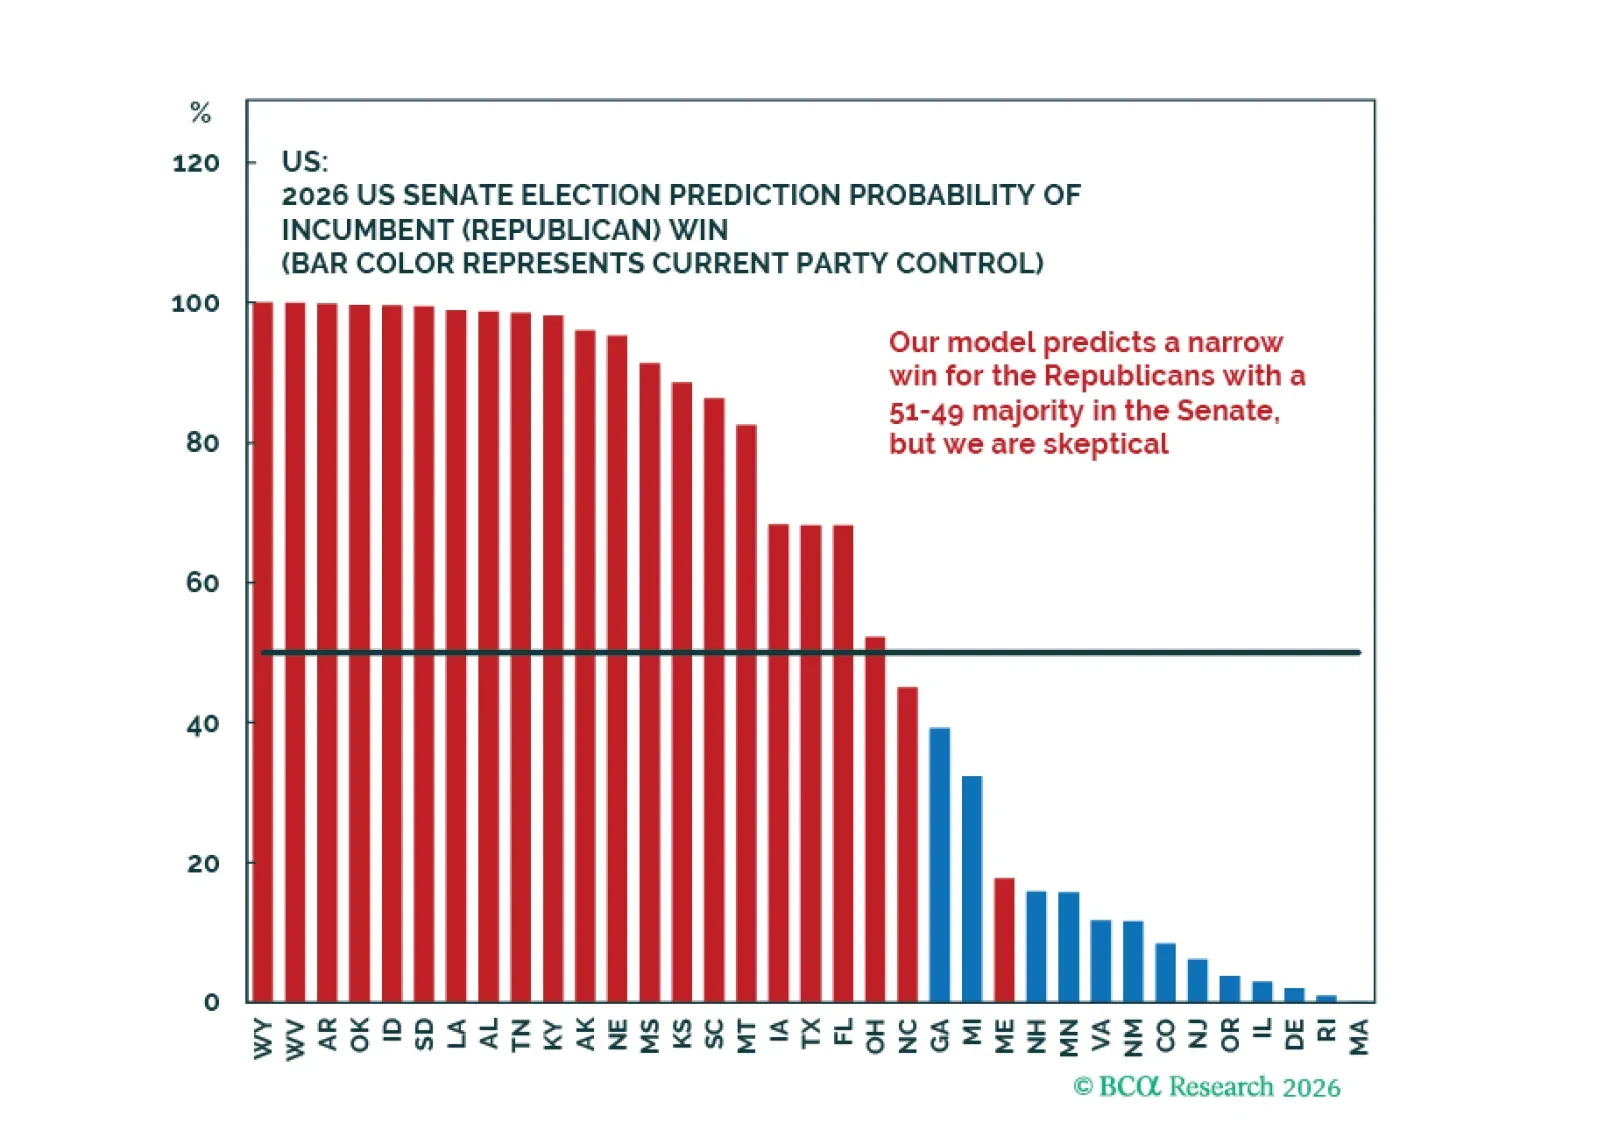
Midterms matter but geopolitics are the main risk this year. Markets will eventually refocus on geopolitical and inflation risks, raising Fed rate hike odds and supporting US dollar and stocks over global counterparts this year.
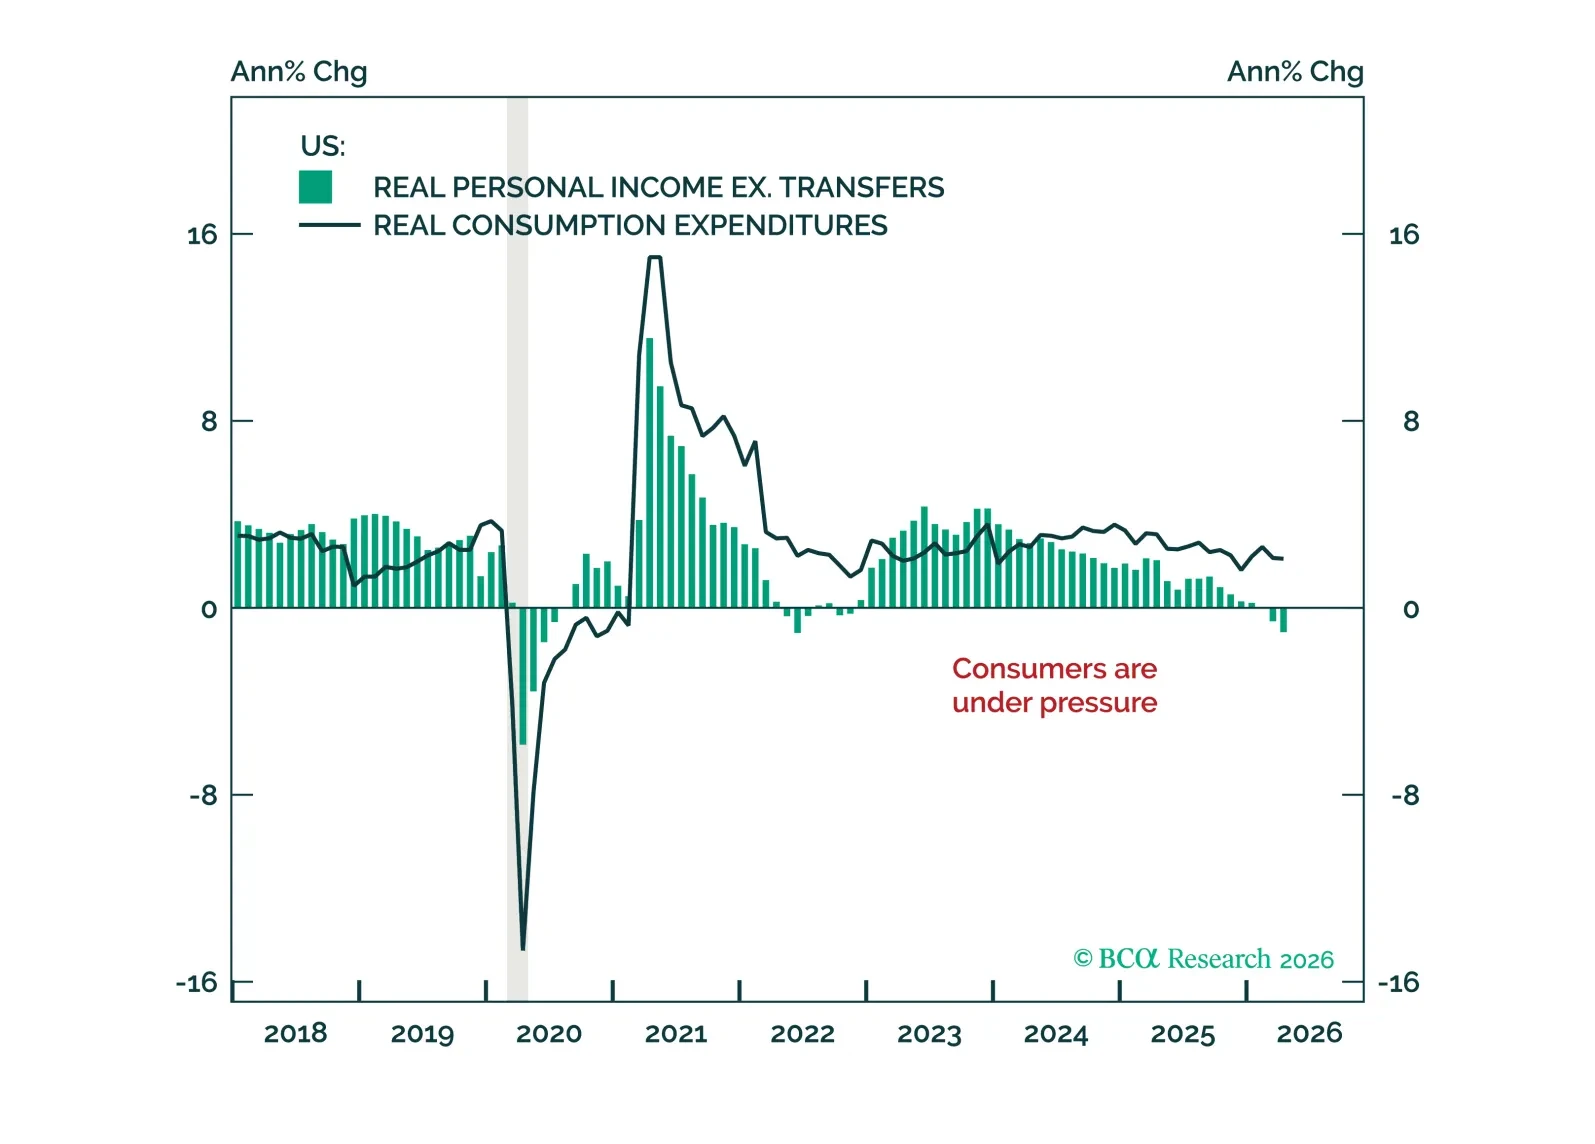
For the first time since… 2022… the GeoMacro team is starting to contemplate the end of the cycle in a serious way.
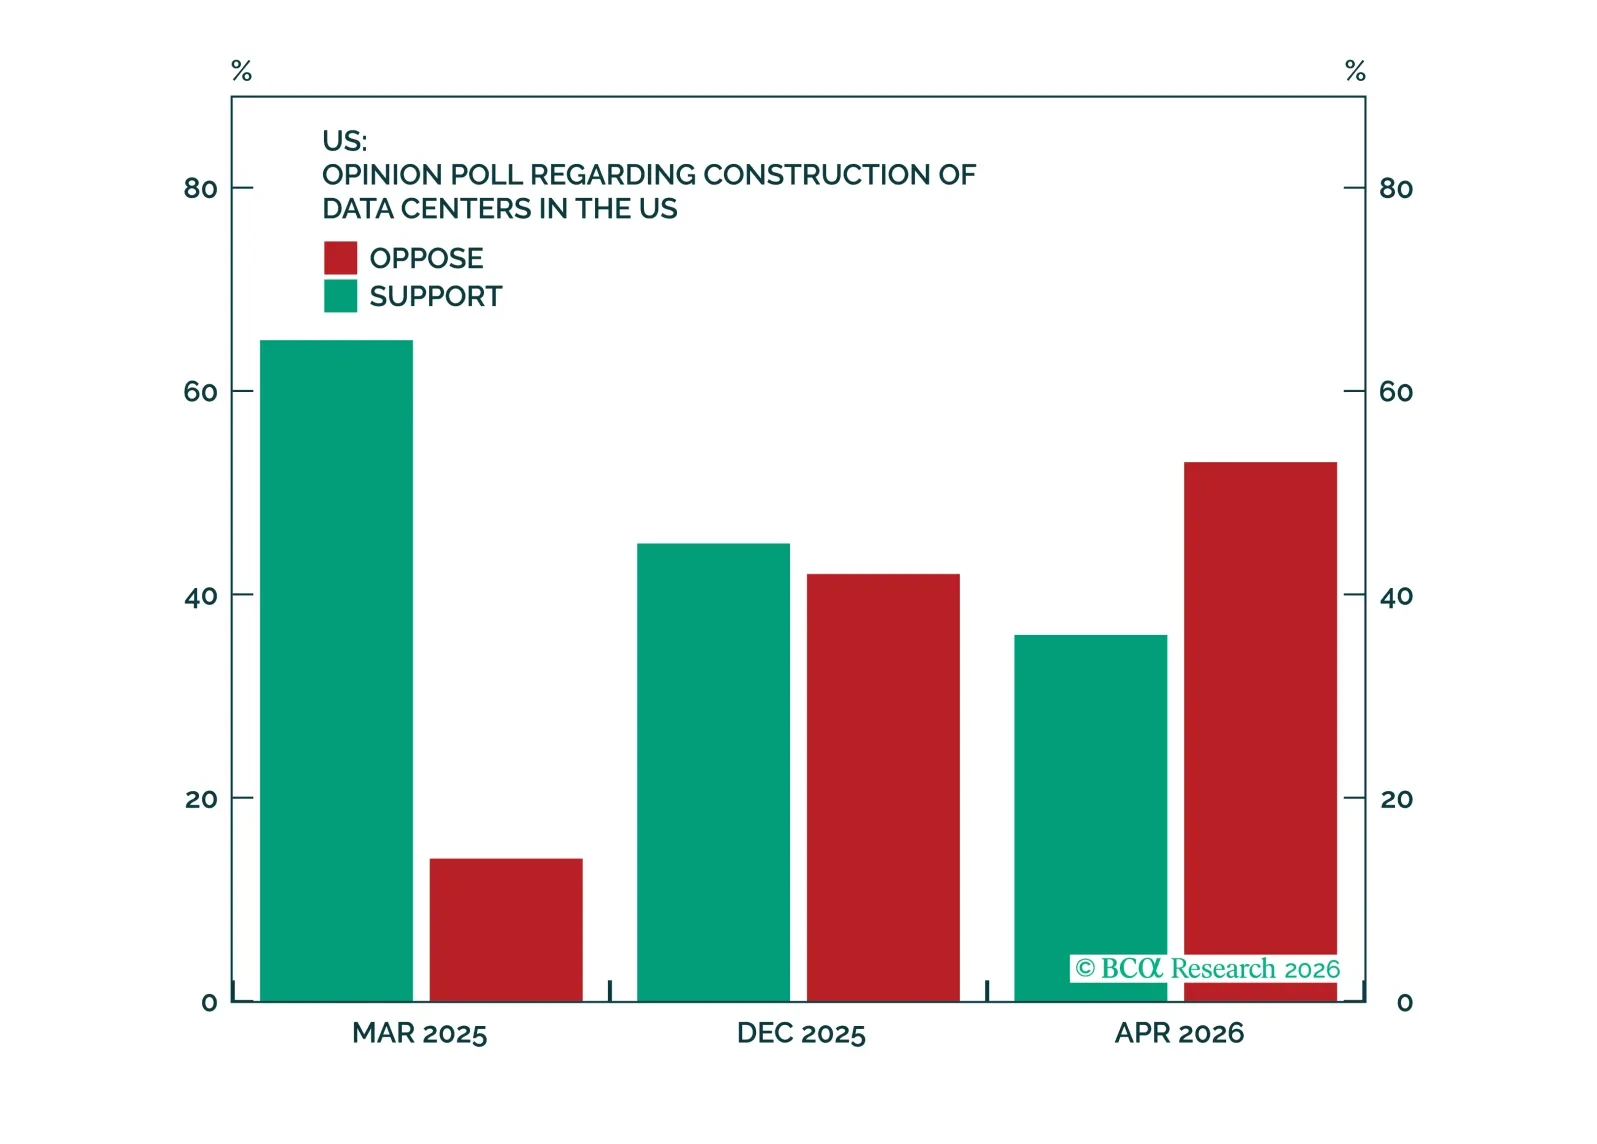
The populist backlash against AI could result in bipartisan regulation in 2027, but is especially likely to prompt tax hikes from 2029.
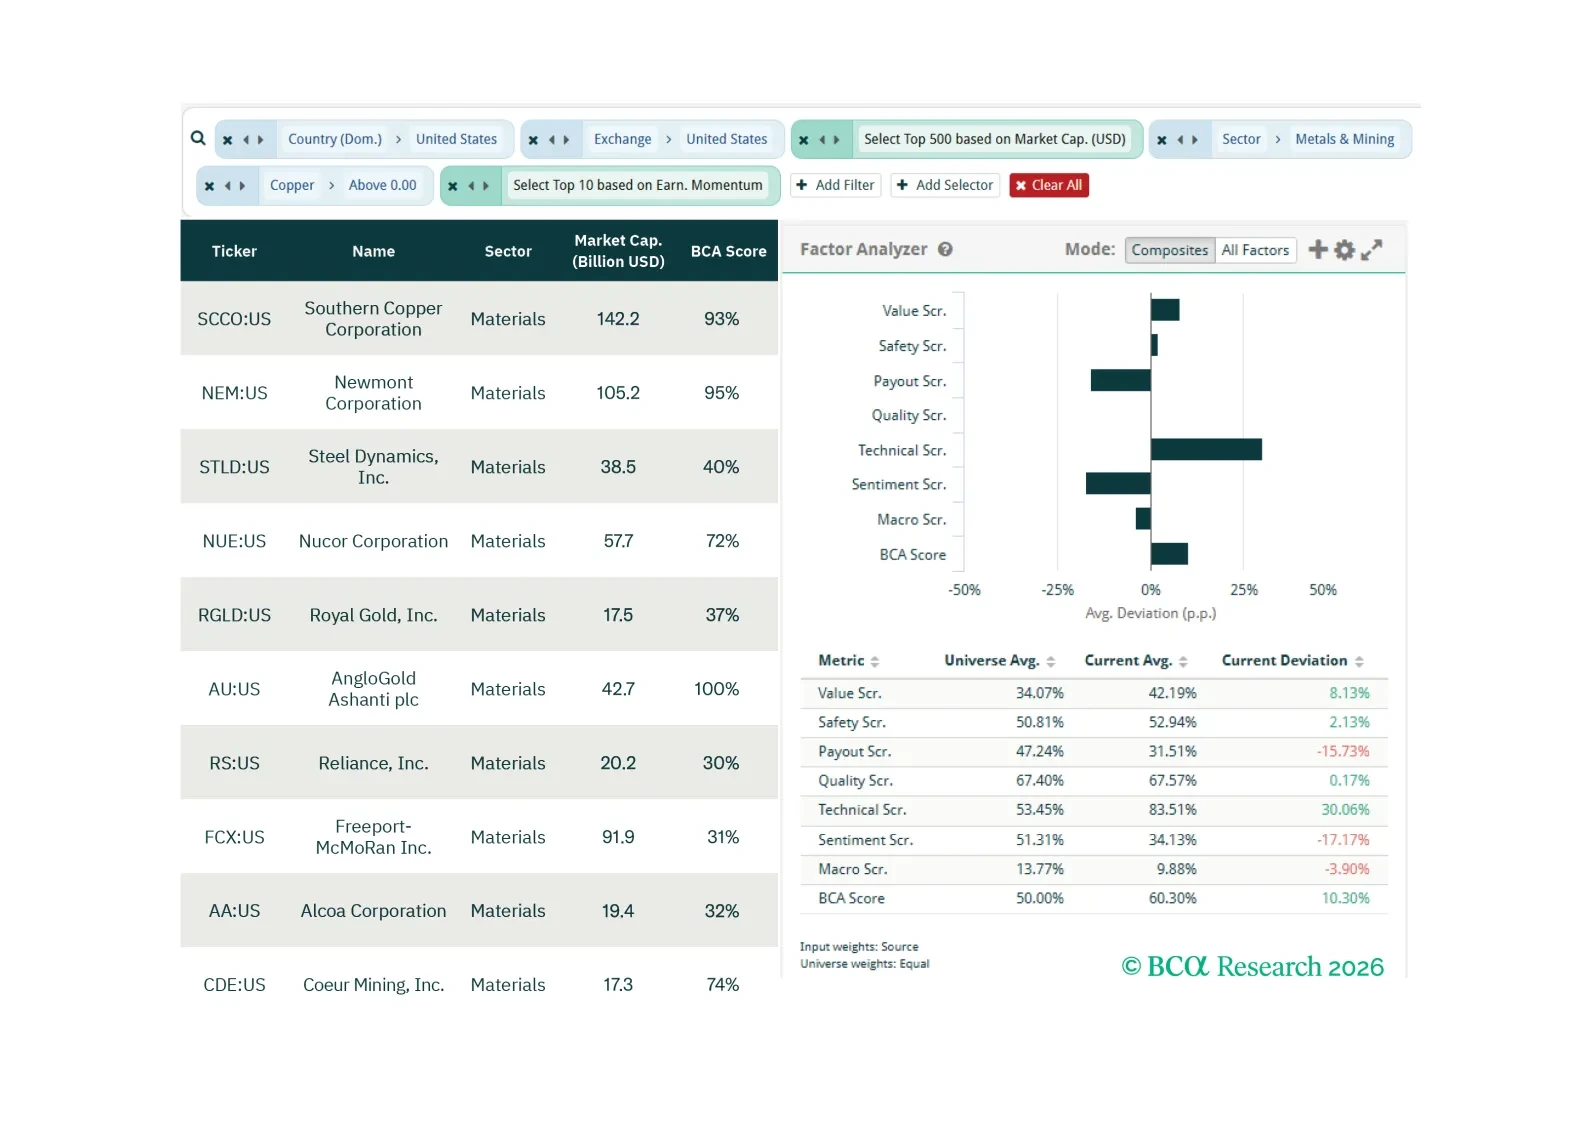
In this screener report, we explore opportunities in: US copper beneficiaries; Australian Materials, Energy, and Industrial stocks; and US reinvestment-led Tech stocks.
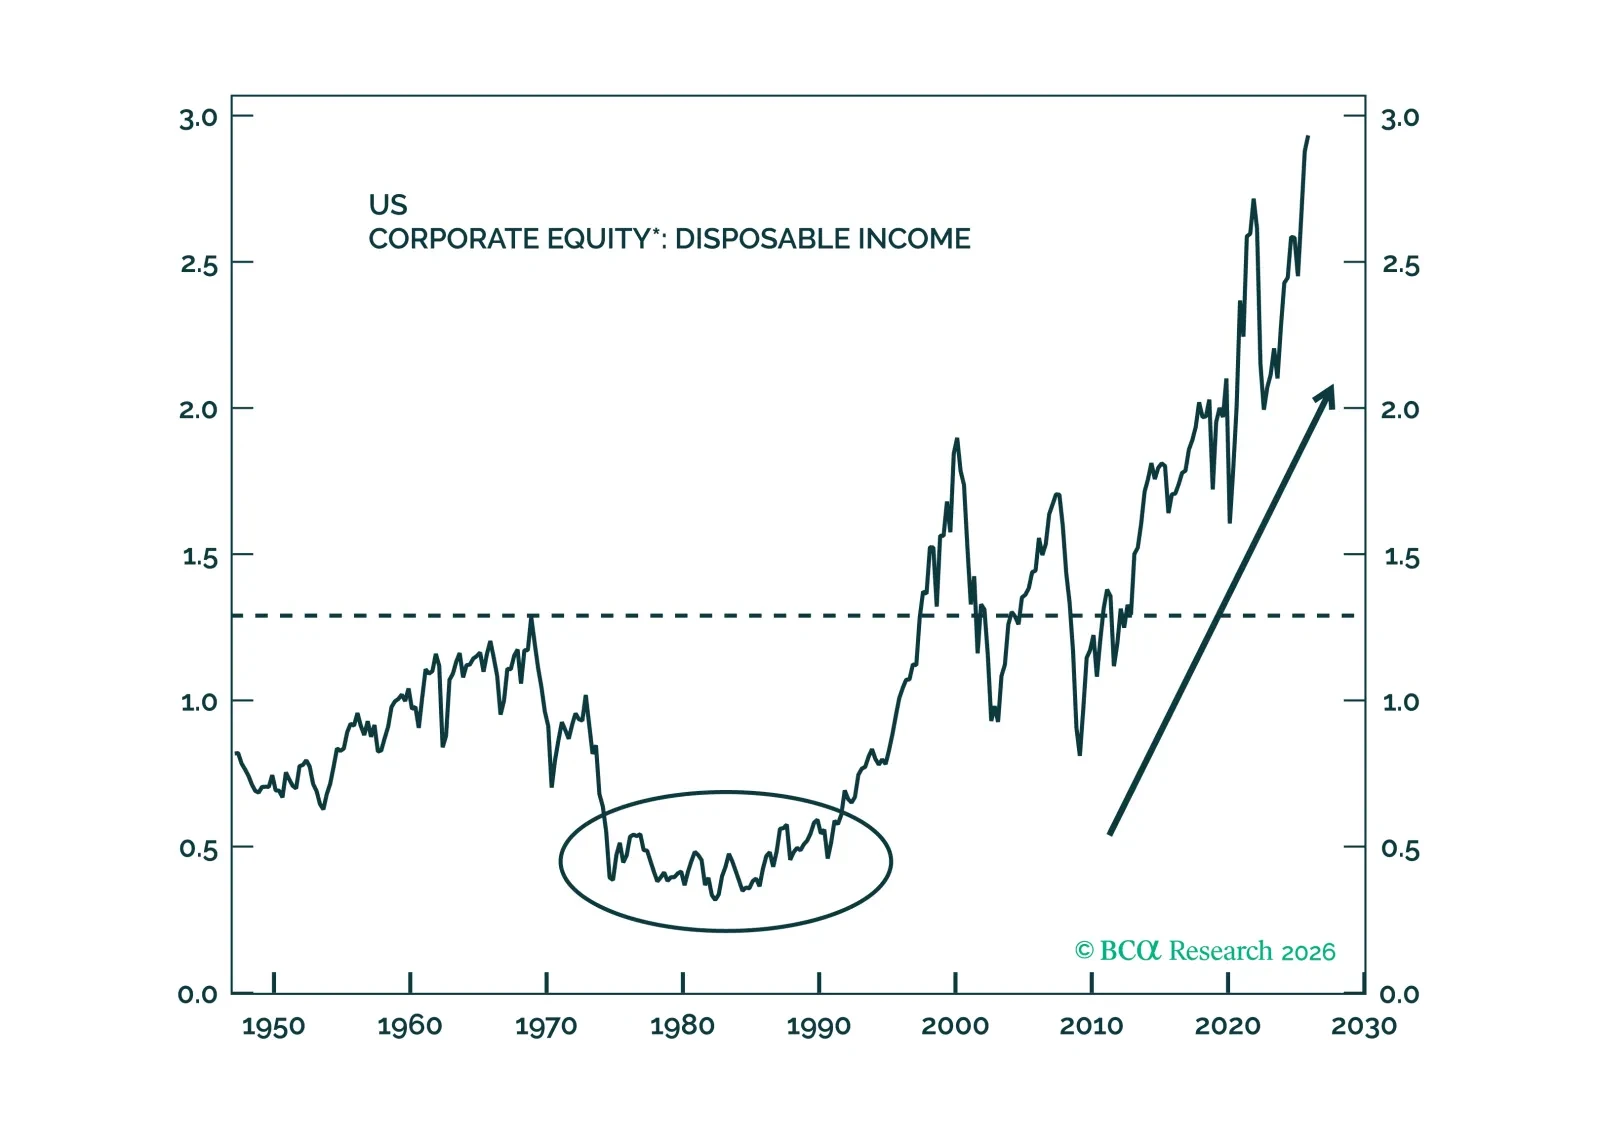
Although the multi-decade surge in the value of households’ equity holdings has made US activity more vulnerable to a stock selloff, the latest income, spending and employment data suggest that consumption growth can carry on at a 2% inflation-adjusted pace.