Latest from BCA Research
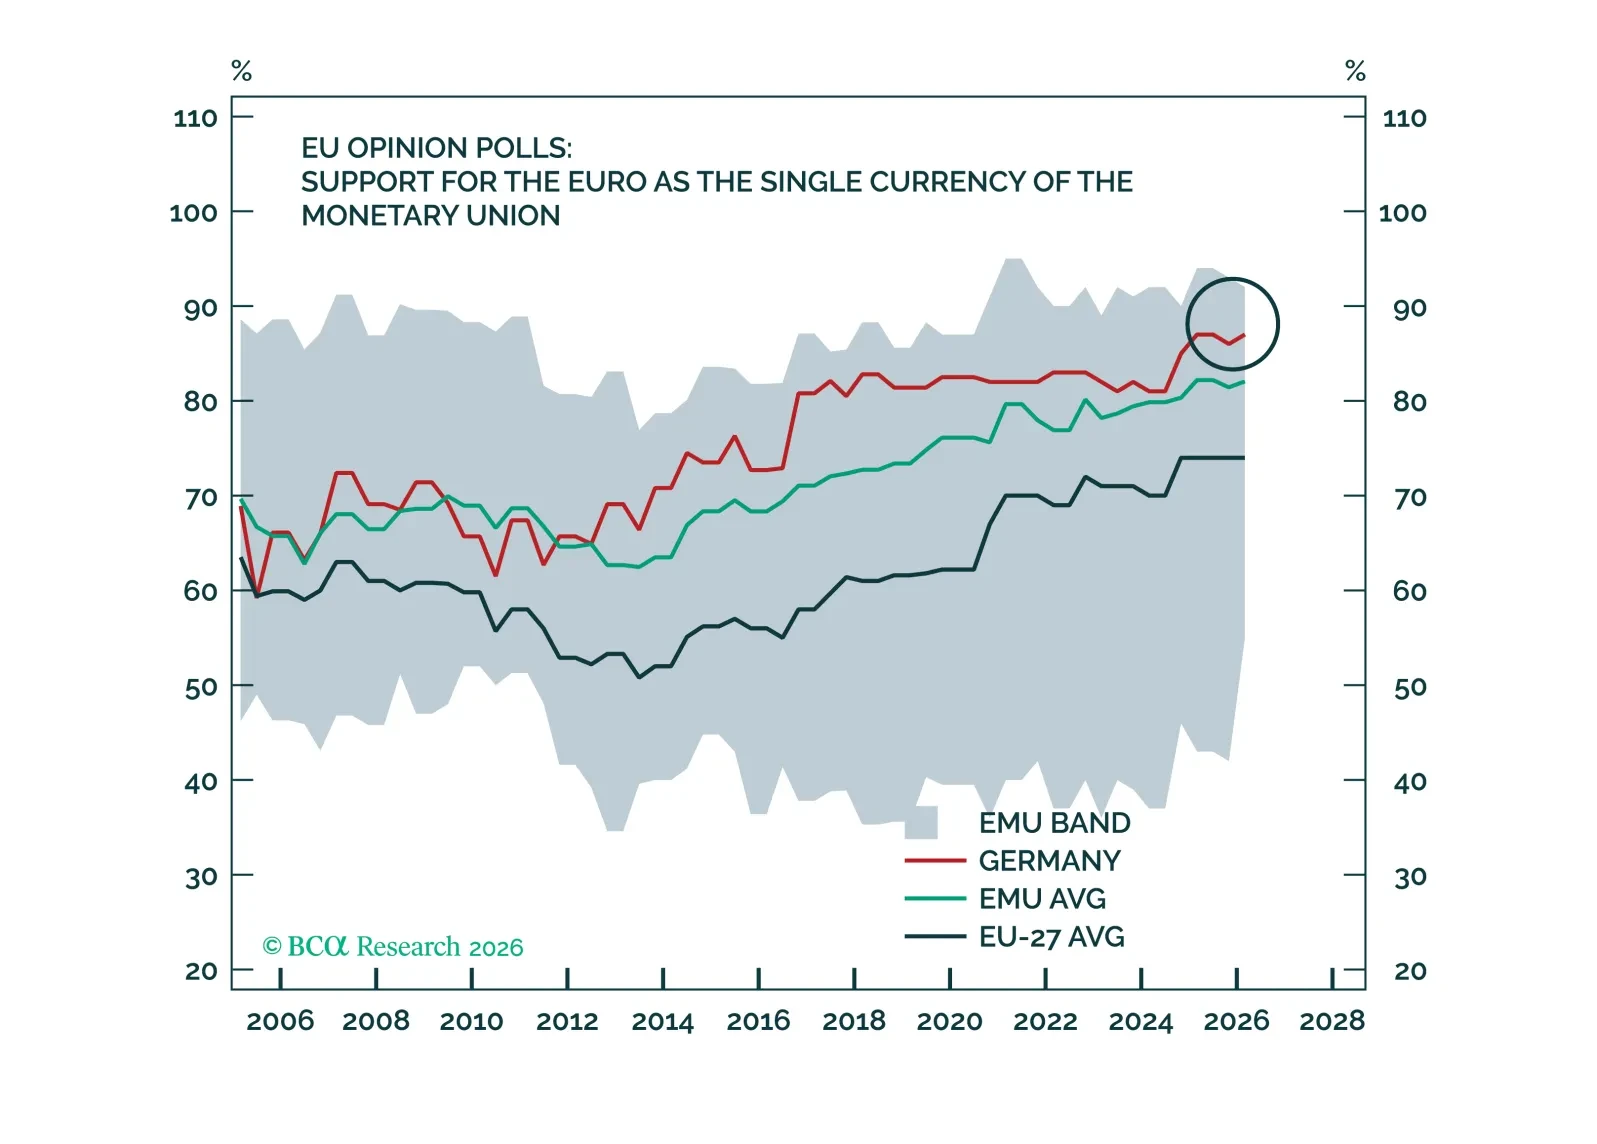
Alternative for Germany’s election win in the state of Saxony-Anhalt is overrated.
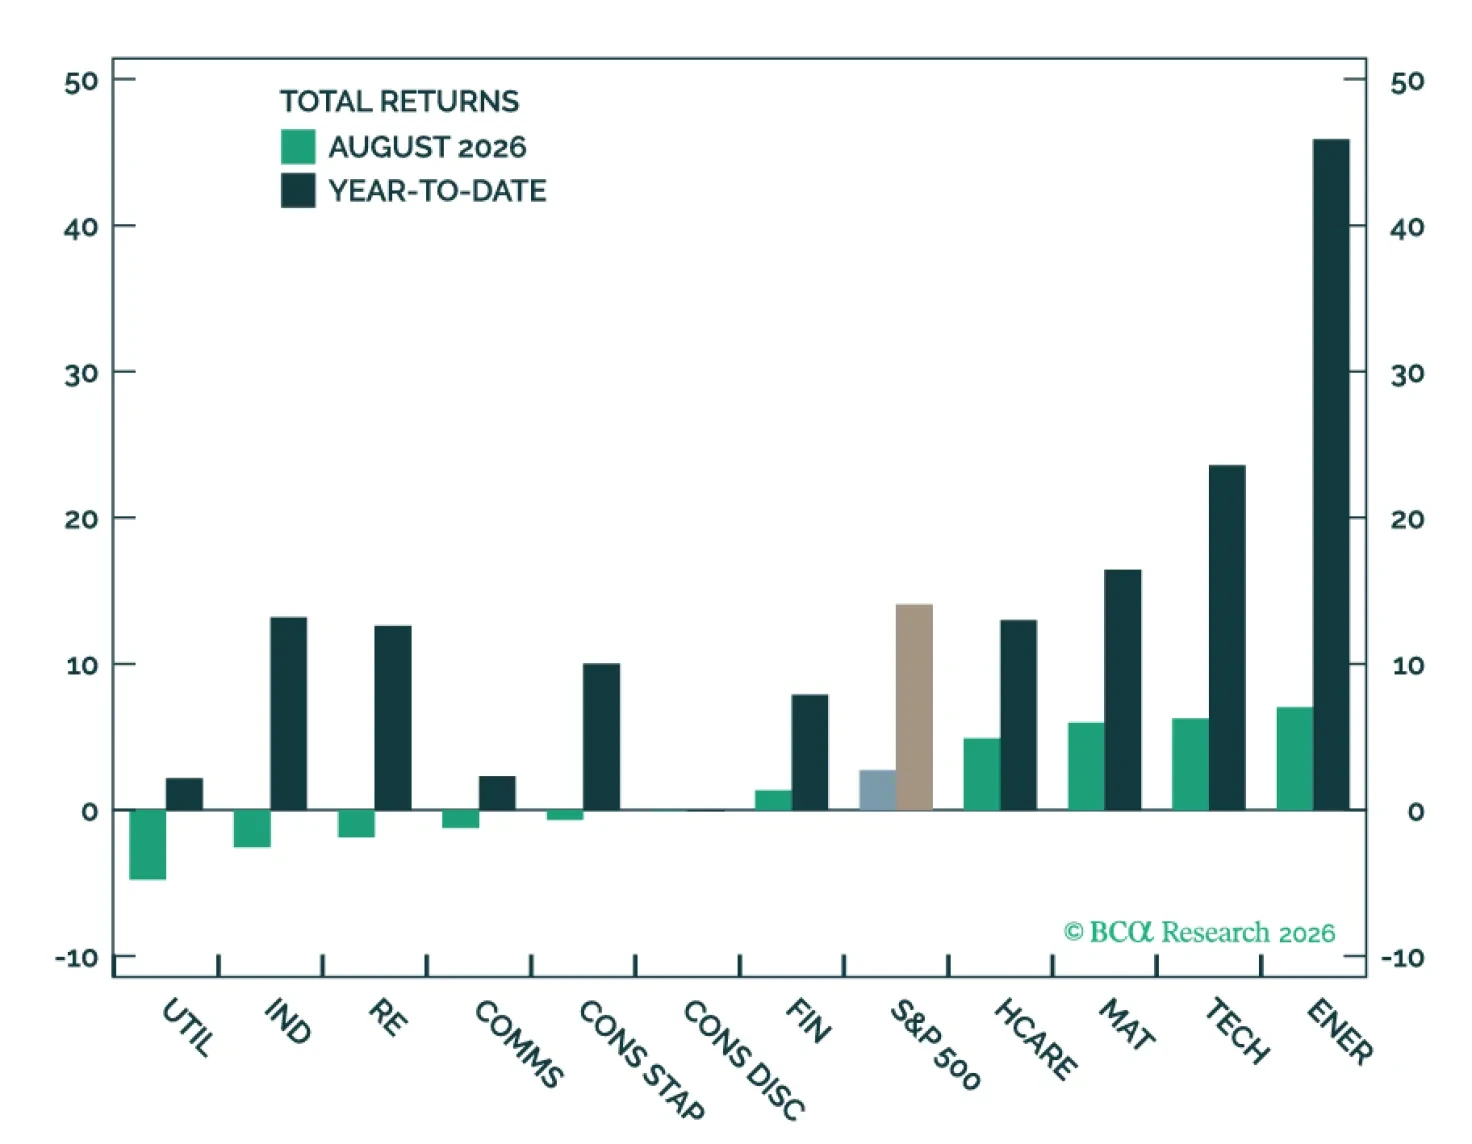
Strong second quarter earnings suggest that the AI story is intact. Buoyed in part by this strength, tech stocks have recoupled with healthy fundamentals after a late-July swoon, posting solid August gains. We continue to see upside for the S&P 500, favoring the cyclical and AI exposure of tech, materials, and industrials. But rising bond yields remain the dominant headwind.
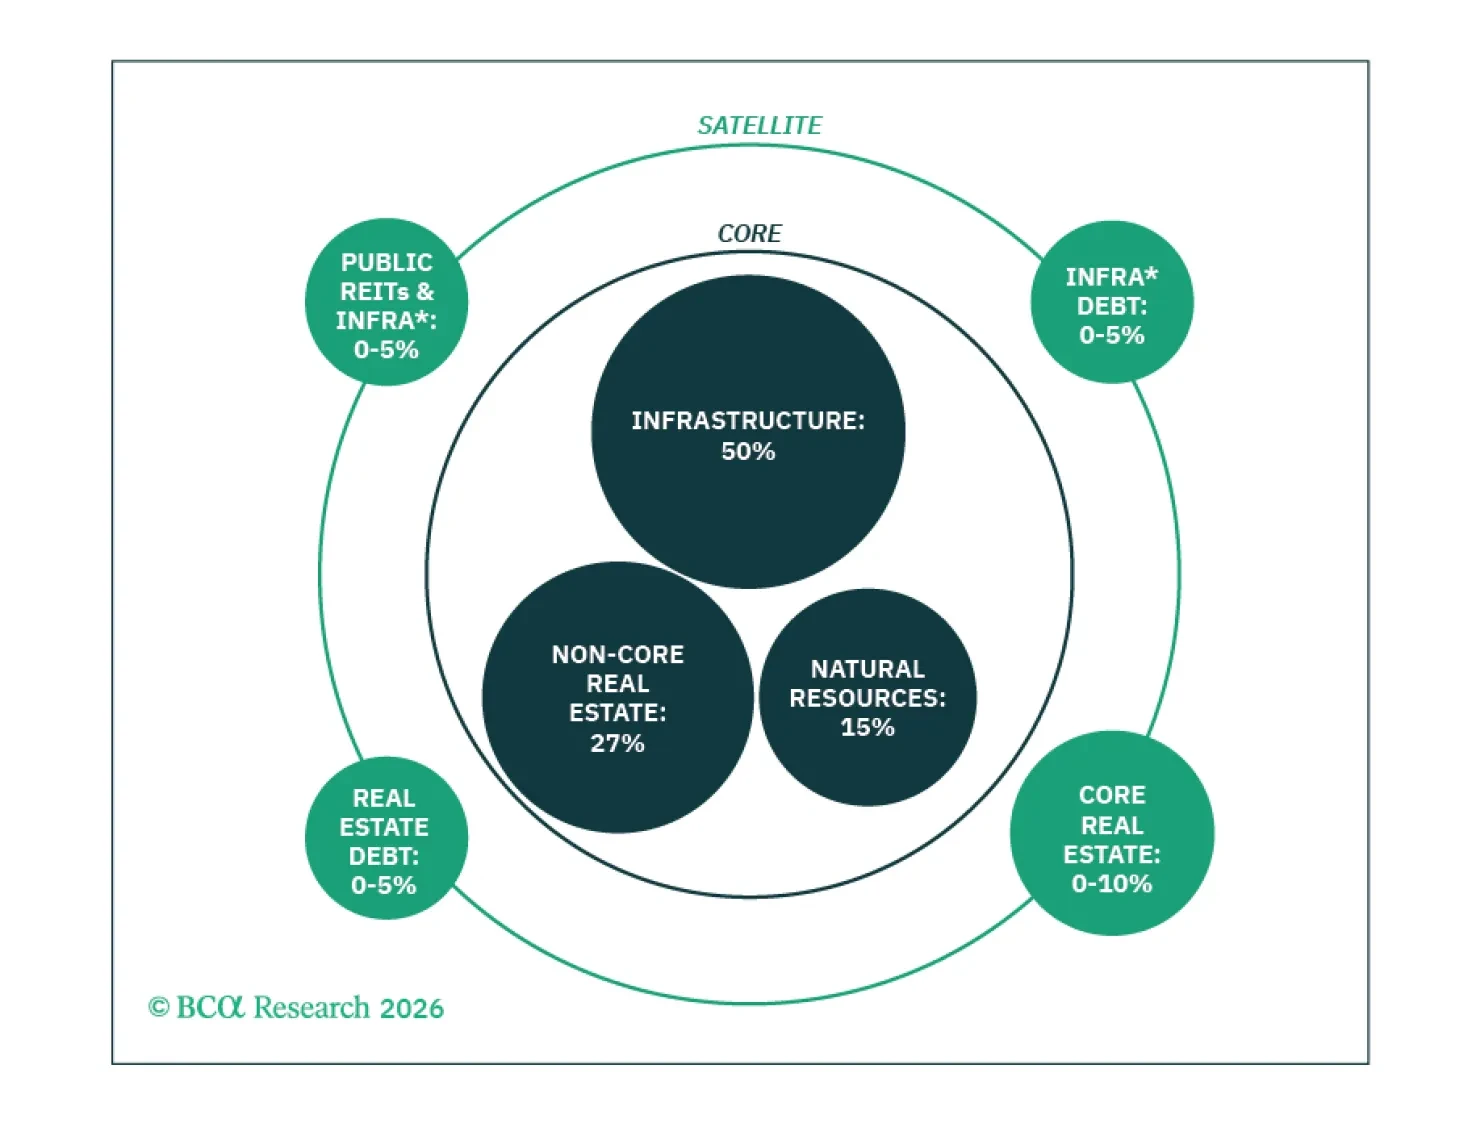
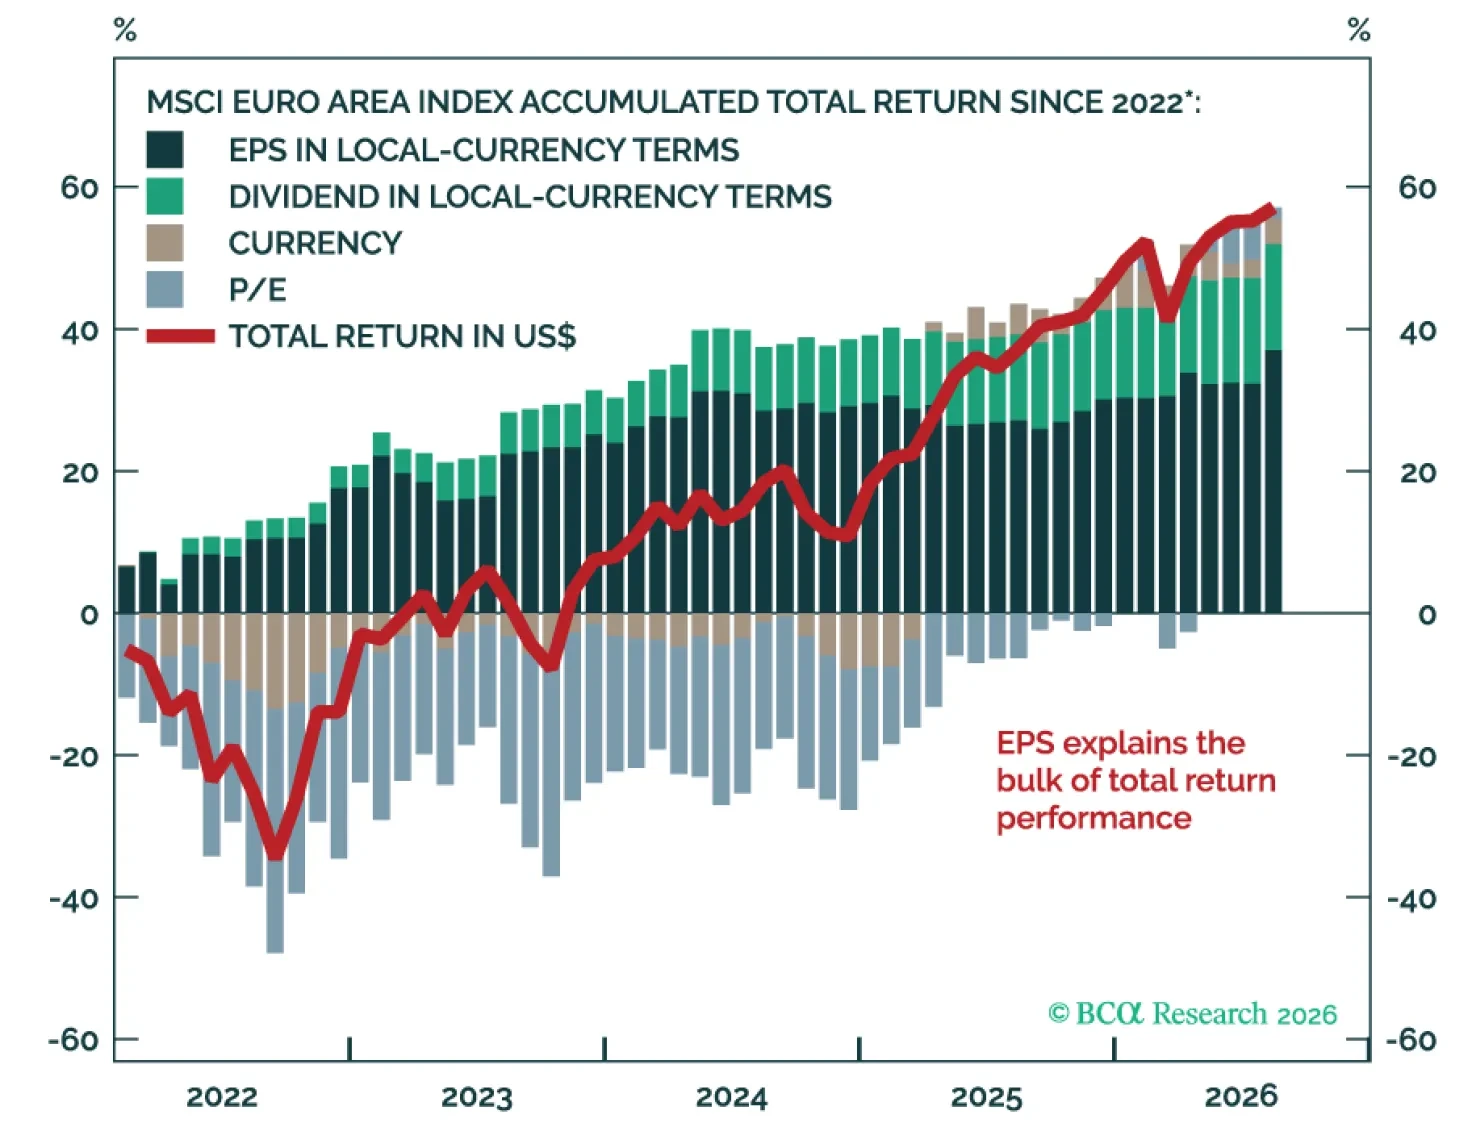
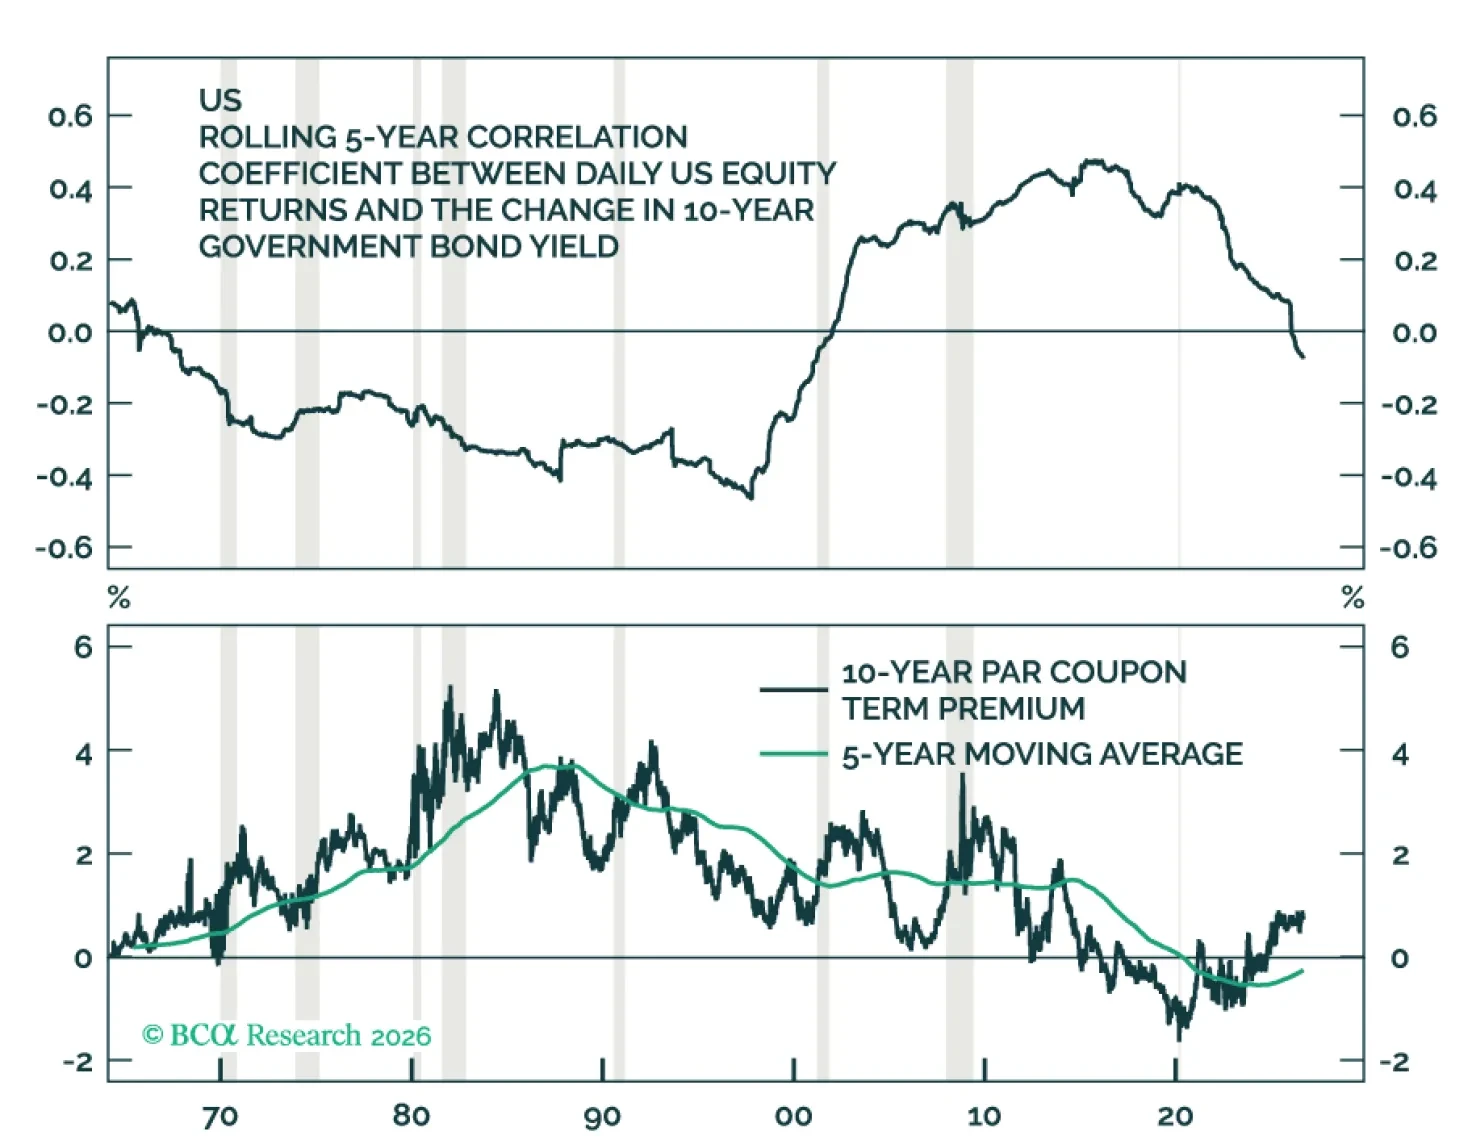
There is no evidence that there is a run on US government bonds. All the data at our disposal, and the curated views of our bond specialists, suggest that the US bond market may have 99 problems, but a coordinated run on its safe haven status is not one.
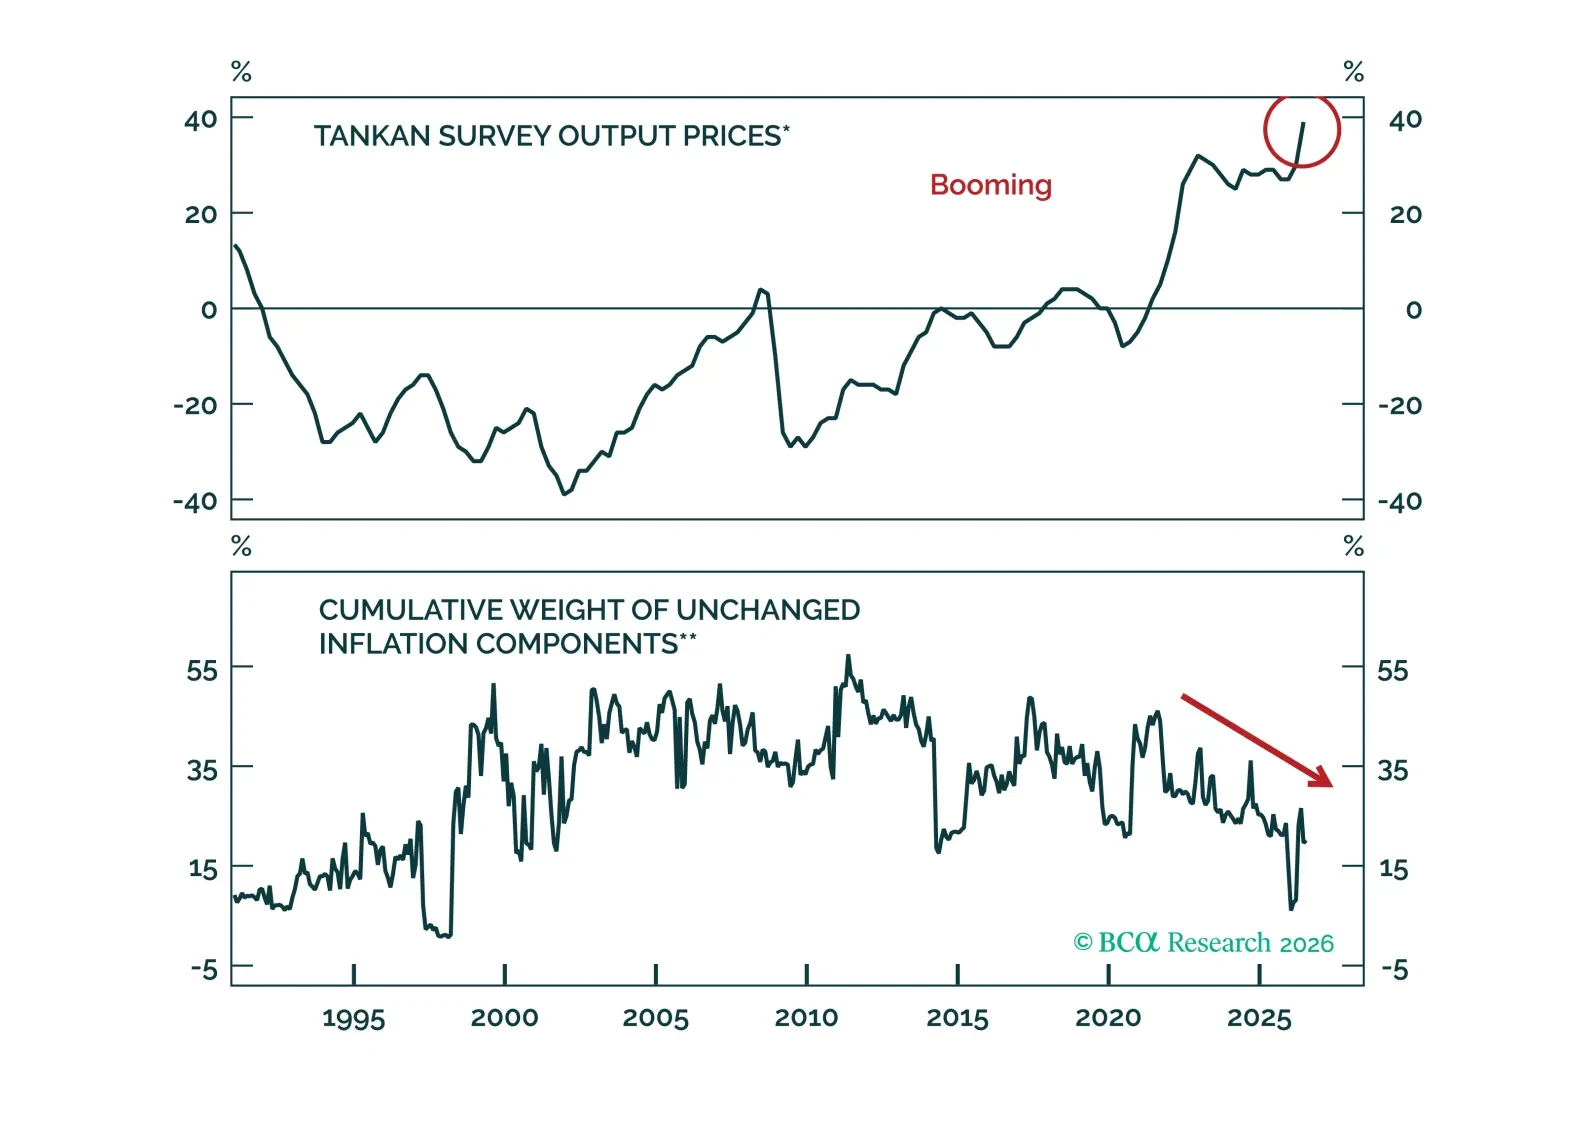
The yen's next leg isn't a fiscal story, it's an inflation one, and the BoJ is about to admit it. We lay out why a September pivot sends USD/JPY toward 99, and why global risk assets won't pay the price.
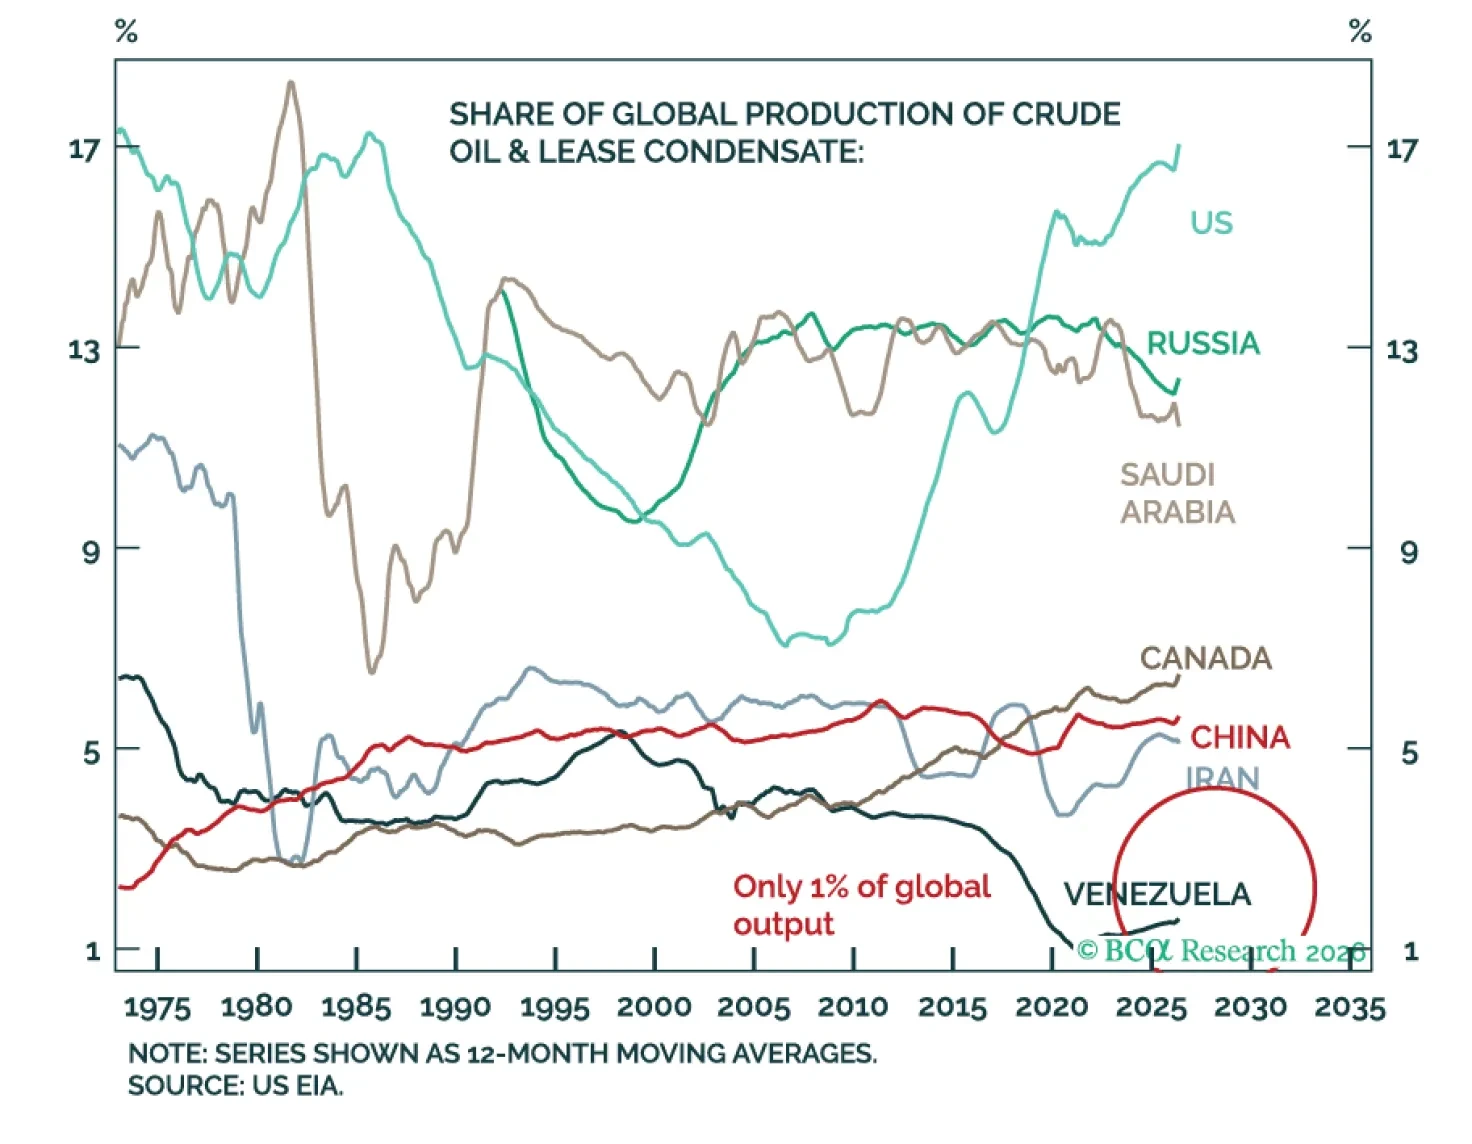
President Trump referred to the US-Venezuela agreement as the “biggest oil deal in world history.” However, oil production growth constraints limit its near-term impact on global crude markets. Instead, Middle East developments will continue to dominate oil’s trajectory over the coming months.
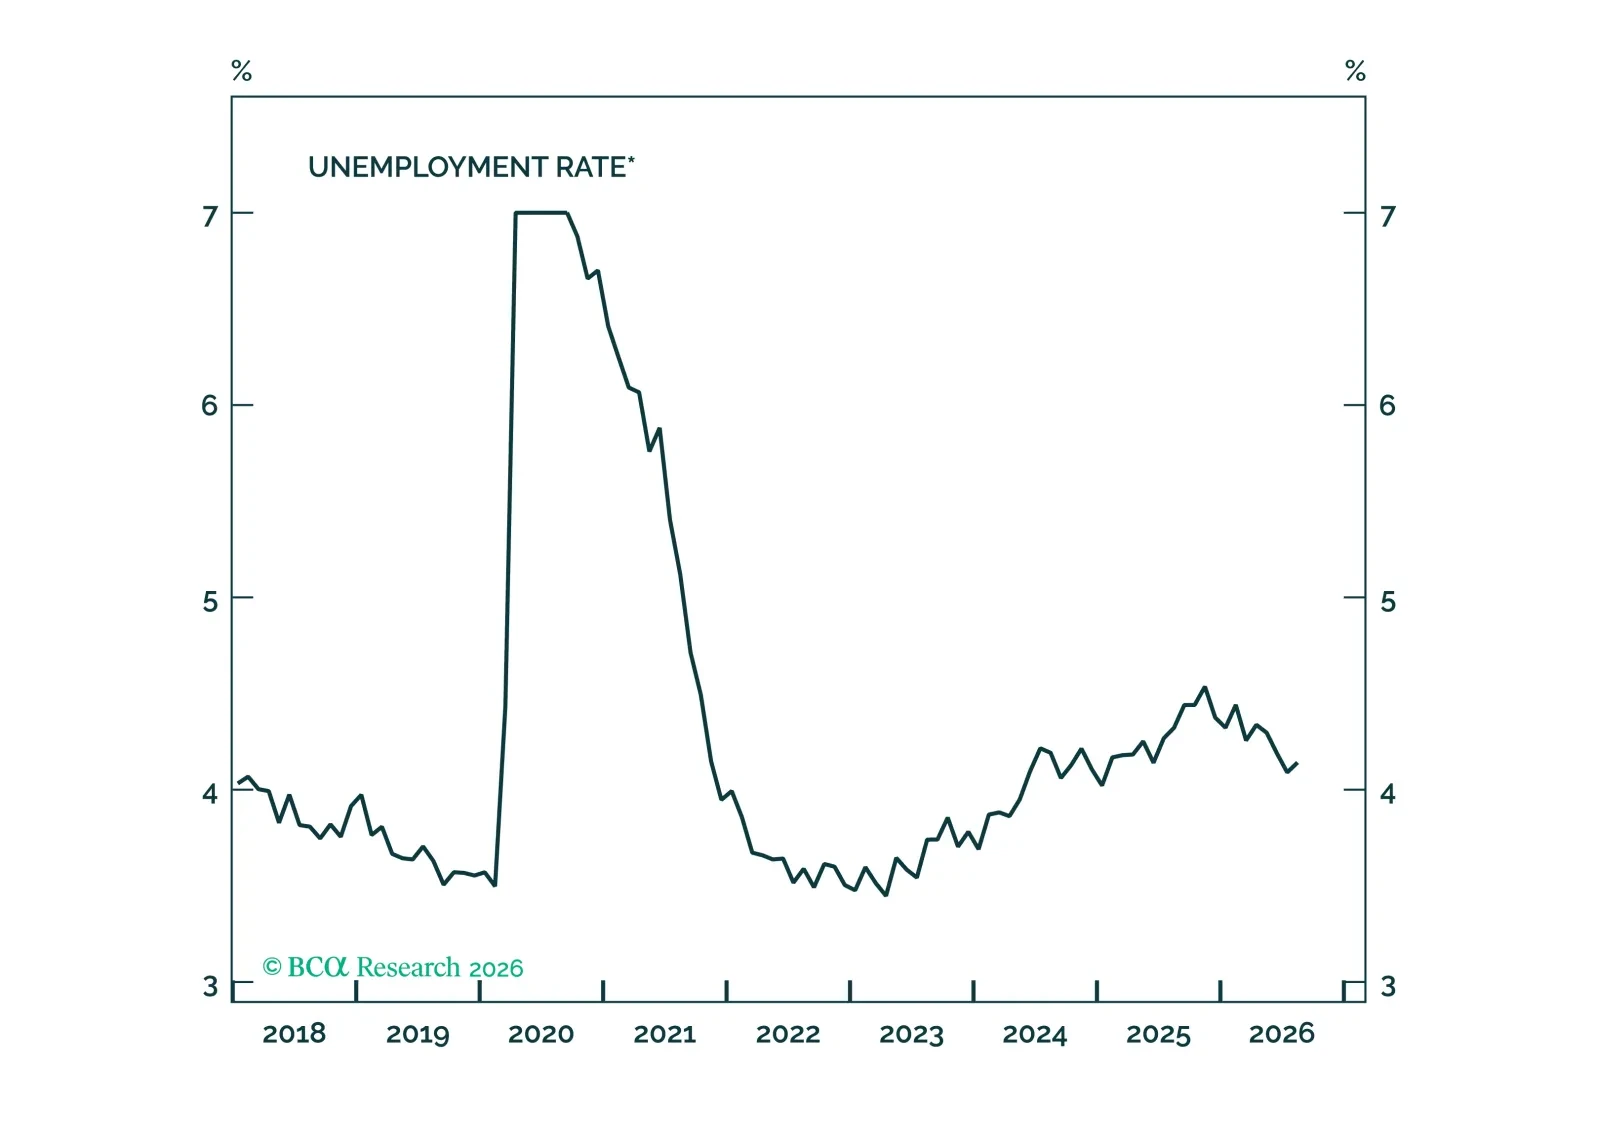
Next week’s CPI and PPI reports will be much more important determinants of the near-term Fed policy path than this morning’s employment report. However, if the trend of labor market tightening continues through year-end, it could lead to a re-acceleration of wage growth in 2027.